The Real AI Moat? Customer Support
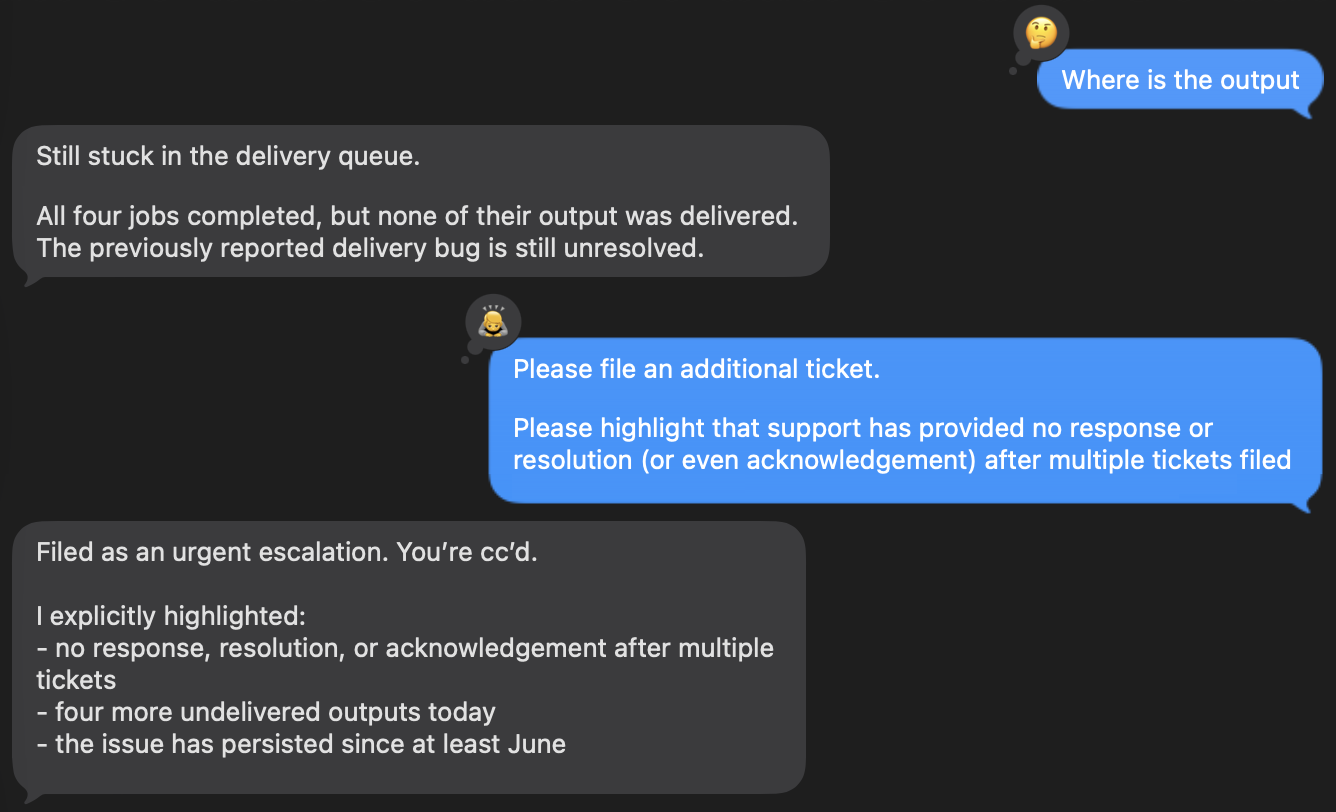
The hardest challenge facing AI startups as they scale isn’t technical, it’s technical support.
At the beginning of the year, AI adoption started to go exponential (at least, within the consumer / prosumer segment). Opus 4.5 came out and caused developers everywhere to stop, collaborate and listen. Then Clawdbot Moltbot OpenClaw delivered the world’s first AI agent “kit”. In the months since, countless teams have worked to develop (or pivot to) personal agents.
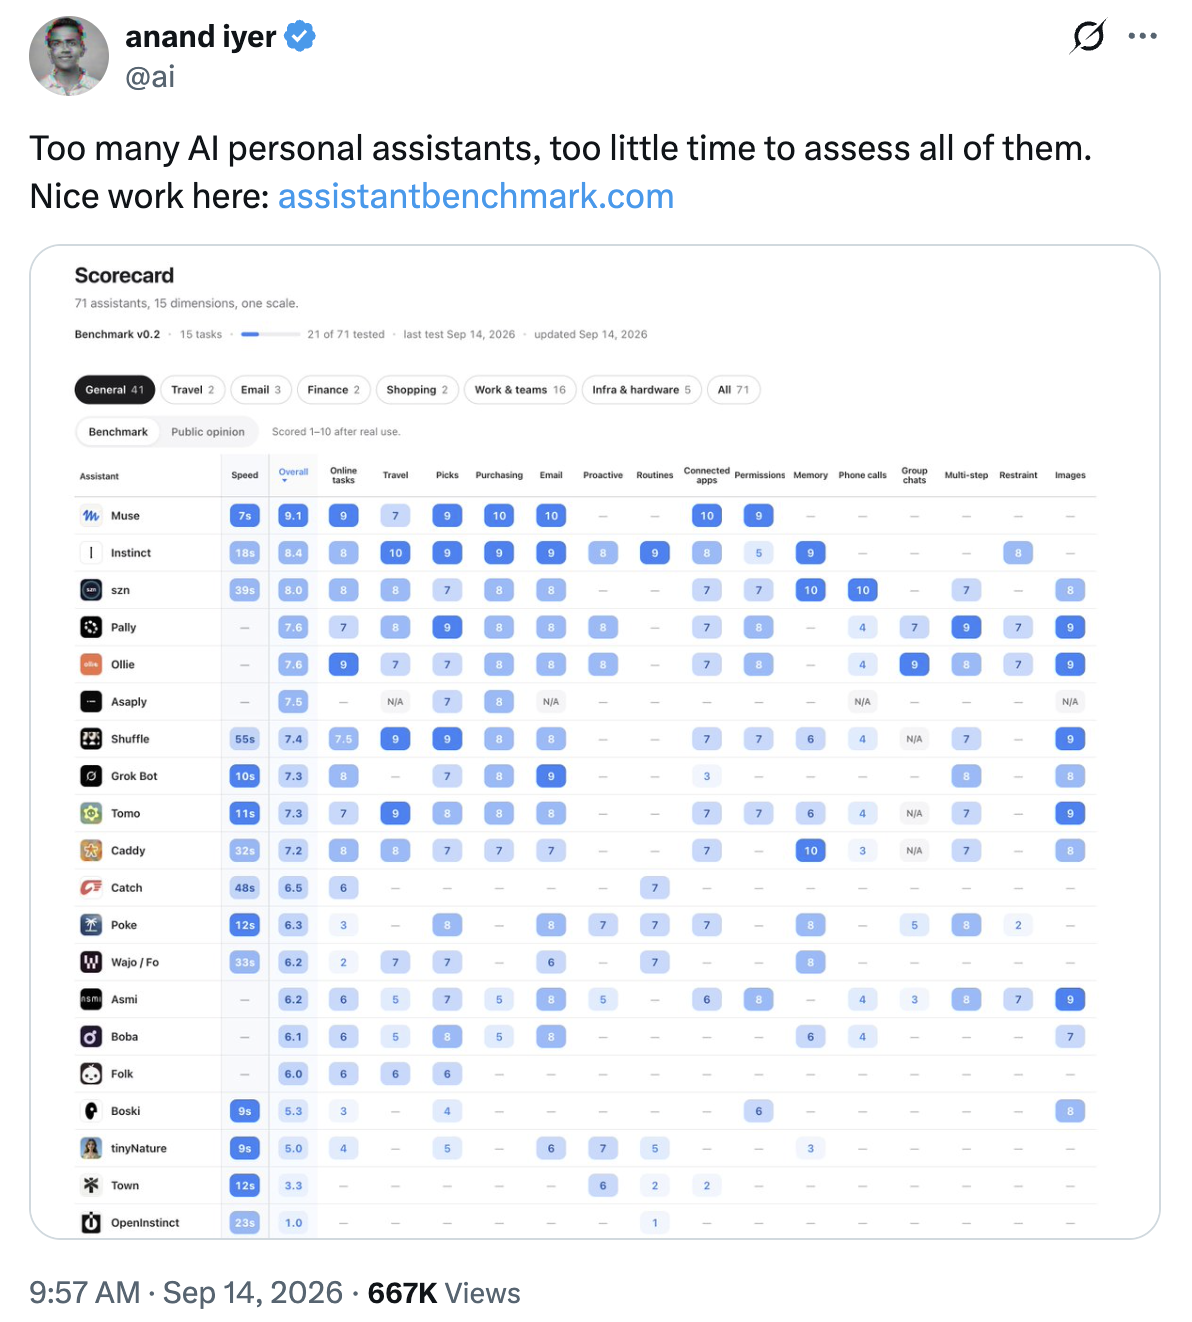
I’ve used a number of these agents to varying degrees over the course of the year and have come to two conclusions:
None of them are capable of doing everything I want them to do out-of-the-box (at least, not yet)
The hardest challenge facing these companies as they scale isn’t technical, it’s technical support
From a user/customer standpoint, the biggest difference between a framework that can be customized, like OpenClaw or Hermes, and an out-of-the-box solution is who is responsible when something doesn’t work. If I use an open source solution and it fails to do what I want, then it’s up to me to figure out how to fix it. But if you’re selling me a black box and promising that it can do all the things..?
Here’s a pattern that I’ve seen happen numerous times over the past year with personal agent startups:
Startup releases beta version of their new personal agent. The team slowly onboards a small number of users and actively solicits feedback. Everyone is extremely responsive as things inevitably break and fall down.
Agent gets released publicly. More users get onboarded. More things break. The team is still mostly responsive, but those responses take longer to get.
User growth goes parabolic as the new agent goes viral. Almost all effort goes towards keeping the platform up. Lots more things break. Lots more tickets get filed. And the team can’t keep up.

Cricket’s the name. Jiminy Cricket.
As a former founder, I’m incredibly empathetic to this plight.
In the early stages, it’s very likely you don’t have anyone dedicated full-time to technical support. It’s almost always the engineers and cofounders pulling double-duty to respond to customer complaints and feature requests (perhaps with the help of some triaging agents). For traditional startups, this approach usually works. But that’s because the surface area of “things that can go wrong” is relatively focused.
AI products are a different beast. For starters, their general-purpose nature dramatically increases the number of things that can go wrong (instead of naturally clustering around a handful of features, as is the case with traditional software).
That’s hard enough. But when you layer in the potential to quickly scale users, a fire hydrant of feedback is almost inevitable.
As an aside, a unfortunately large segment of Startupland™’s has been gaslit into believing that customer support should be a low priority.
This goes all the way back to the days when Google first launched Gmail in “beta” and basically put a sign on the front door telling users, “if something goes wrong, it’s not our problem.” Coming out of Covid, we saw many Web3 founders do the same thing: spin up a discord server, drop in once a week to check things out and call it a day. (What do you mean we need documentation? We wrote a white paper! 🤦♂️)
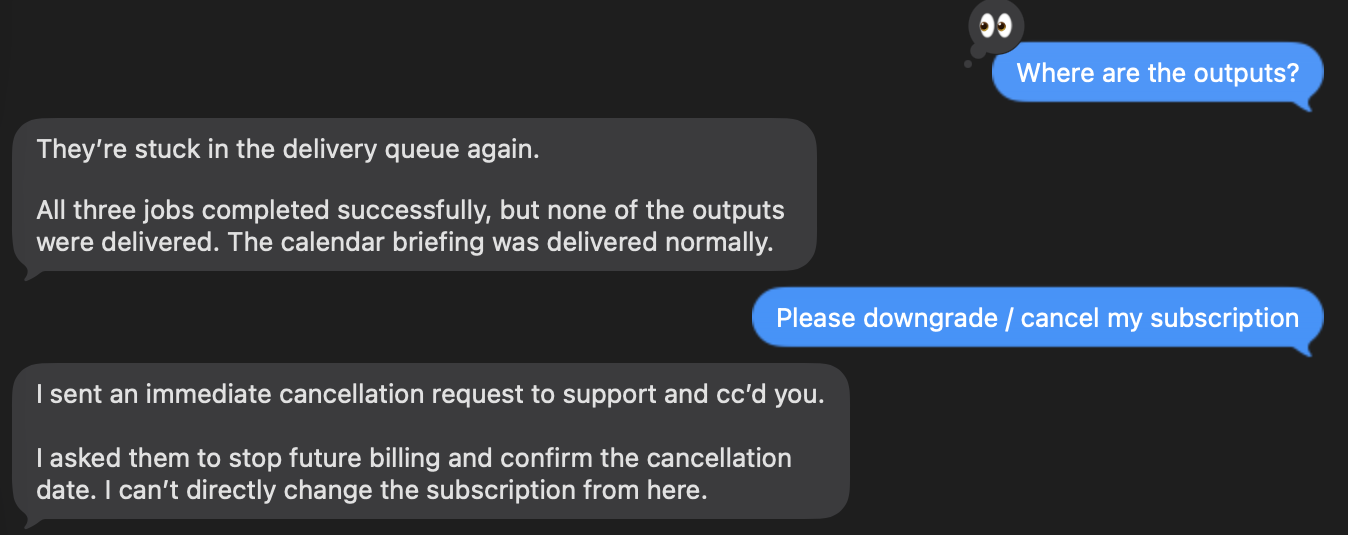
In markets that are highly-competitive — like almost every AI-related market currently emerging — that’s simply not going to be good enough. Especially when switching costs are almost non-existent.
The solution? Prioritize customer support early.
In the early days, your customer funnel is guaranteed to be leaky. Simple yet effective communication goes a long way when it comes to building good will from early adopters. Which in turn results in those early adopters giving you more time and leeway to address their concerns.
But one-on-one customer support doesn’t scale (especially not if you go viral!), so you need to prepare. Here’s how to do that:
Make sure you have a customer-facing ticketing solution before you launch. It could be a traditional third-party solution or something home grown and integrated with your product. But there has to be a way for customers to check on the status of a ticket they previously filed.
When customers (or their agents) file a new ticket, make sure that receipt of the ticket is immediately acknowledged and comes with instructions on how to track it.
Provide status updates. This is the obviously the hard part if user growth is skyrocketing and you can’t keep up, but finding a way to let customers know that you haven’t forgotten about them is crucial. Even if those updates are automated and mostly mea culpas (“we’re trying our best!”).
Be honest when setting expectations. If you know that you won’t be able to get to a particular fix or feature for awhile, let customers know. If you have to back out a new feature because it broke in too many places, that’s okay too.
The most important thing is to make your customers feel heard. If they keep filing tickets without getting a response, your early adopters will feel like they’re screaming into an abyss. And when they do…
Lessons from 250 Blog Posts
I never thought I’d actually write for this long, so I thought I would take some time this week to reflect on it. Here are some of the lessons I learned from writing 250 blog posts.
This week marks a momentous milestone (for me, at least): this is the 250th post that I’ve written on chrisneumann.com.
I never thought I’d actually write for this long, so I thought I would take some time this week to reflect on it. How has my content evolved over the past four and a half years? Does it still resonate with readers? And where should I go next? (If you’re currently reading this on the website, you may have noticed a new look — I’ll dive into the rationale for that shortly.)
Here are some of the lessons I learned after 250 blog posts.
The Backstory
When I moved to Canada in late-2020 to join Panache Ventures, I noticed that there was a lack of entrepreneurial content available for founders there. I had spent the better part of the 5 years prior teaching founders around the world strategies and best practices used by leading Silicon Valley startups (first at 500 Startups and, later, through Commonwealth Ventures). So I thought I’d write about some of them.
But there was one problem.
Over the years, I had written a handful of blog posts, but I could never figure out how to publish content on a consistent schedule. I knew it was possible to write with a weekly cadence (after all, I wrote weekly investor updates for nearly five years at DataHero), but I had never done so with creative or longer-form content.
I mentioned this dilemma in passing to one of my mentors, Marvin Liao, who told me about a course he had recently taken called Write of Passage. The program was the brainchild of an exceptional young writer named David Perell. Despite its name, Write of Passage wasn’t actually a course about writing. At least, not in the strictest sense. Rather, it was a bootcamp designed to teach you how to build systems and processes to support writing and publishing new content on a regular basis (like weekly blog posts). It was exactly what I needed.
It turned out, I wasn’t the only one. The participants in my cohort included many residents of Startupland™, like founders and VCs. But there were also professional athletes, academics and a wide variety of other writers and aspiring writers.
How It Started
Write of Passage was one of those programs that unapologetically threw you in the deep end from the start. The very first session kicked off with a firm dictum from David: in order to stay in the program, you had to publish your first post within one week.
The prompt: “What is the definitive answer to the question that people ask you most often?”
At the time, it had been about six months since news of my joining Panache and moving to Vancouver was announced. In subsequent calls and coffee chats I was repeatedly being asked the same question:
“Why did you come back to Canada?”
On April 13th, 2022, I published the answer to that question and launched this website.

How It’s Going
It’s now been 229 weeks since that first post (for those of you wondering how I reached 250 posts in only 229 weeks, there were several periods of time when I published multiple posts each week — such as during my brief side quest into food blogging.) Over the past 4 ½ years, readership of both my website and the corresponding newsletter have steadily grown (thank you all for that 🙏).
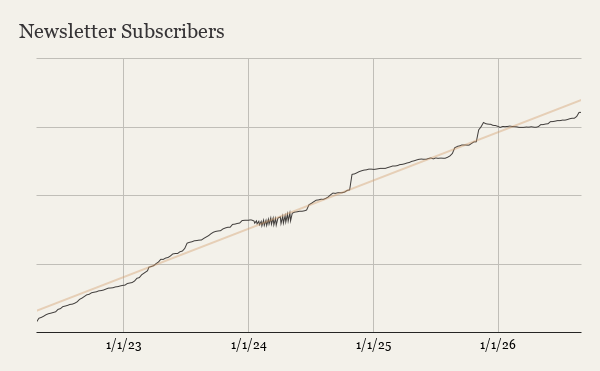
I have no idea what happened in early 2024…
But it hasn’t all been “up-and-to-the-right.”
While website traffic and newsletter subscribers have steadily grown, open rates for the newsletter have slightly declined over the years.
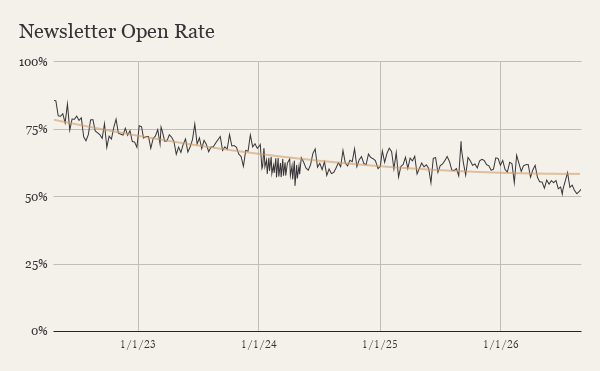
The open rate for my newsletter has held steady around 60% for the past two years (a rate that is generally considered pretty solid, though with AI preview and summary tools becoming so prevalent, it’s increasingly hard to tell). That said, I still wanted to dig into the performance data for both the website and the newsletter.
First, a few thoughts on open rates:
Year 1 open rates aren’t meaningful in any way. The early subscriber numbers were so low (and so heavily skewed to people who already knew me personally), that they were unnaturally high.
A better metric for overall relevance is unsubscribe rate. With agents making it easier-than-ever to ditch newsletters we don’t read anymore, are people still keeping me in their inbox? It turns out the answer is yes (the 90-day rolling unsubscribe rate for my newsletter is ~0.1%, which is considered very strong — thank you again 🙏)
That said, despite a steady open rate and strong retention, there has unequivocally been more inconsistency in content performance over the past few years. So I started to look at what I’ve been posting and how that’s changed:
The content I posted in Years 1 and 2 was overwhelmingly instructional/educational in nature (fundraising best practices, posts about how venture capital worked, etc.). In fact, more than 70% of the first 120 posts I wrote either taught the reader how to do something or explained how something worked.
In year 3, I started writing more posts about startup trends, observations about different ecosystems and topics related to mental and physical health. Last year (2025), only 37% of the posts I wrote were instructional/educational in nature.
The last 2 years have also seen an (understandable) uptick in posts related to AI.
Many of the posts I wrote in years 1 - 3 had an overtly Canadian slant to them. That was very much a by-product of my role as a GP at a Canadian-focused Pre-Seed fund. Since leaving Panache at the end of 2024 to focus on [Redacted], most of the posts that I’ve published were written independent of geography (though I’ve still made a point of writing about trends in the Canadian ecosystem as part of my quarterly 5 Things I Think I Think posts).
What Comes Next
The biggest epiphany going through 250 posts’ worth of data was the degree to which the type of content I’ve published has evolved over the years. The first few years were overwhelmingly educational/instructional in nature because I had a massive backlog of topics that I wanted to write about. Now that I’ve written about most of those, my posts are more focused on trends and observations.
But I’m not done yet.
For starters, it became abundantly clear as I went through Google Analytics data and spoke with founders that a significant portion of my older content had become difficult to find or access. That’s where this redesign comes in. In addition to a cleaner, more streamlined design, there’s a new Topics page that more effectively organizes all of my posts (driven by a complete refactoring of post tags).
I’m also working on a further refactoring related to AEO/SEO/GEO. But I’ll save details of that for a future post.
In the meantime, as I look ahead to (hopefully) another 250 posts on chrisneumann.com, expect more insights, more data and more in-depth posts to help founders, investors and ecosystem supporters around the world make sense of Silicon Valley and beyond.
Thanks for reading 🙏.
Stop with the AI Slop, Part 2
What happens when AI slop finds its way into emails and text messages you send your coworkers, clients and friends?
Tomasz Tunguz recently wrote about his experiences incorporating AI as part of his writing process. He observed that,
“The problem with AI as a ghost writer: everyone uses the same ghost writer. AI’s voice isn’t the author’s.”
Since ChatGPT first came onto the scene, I’ve made a point of periodically testing new models to see if they could accurately reproduce my voice in writing. Years of blog content and social media posts has provided me with a solid set of training data. It turns out that even the earliest models were remarkably good at analyzing my writing style. They could pull out phrases that I constantly use, my preferred filler words, linguistic fingerprints and so on.
But for all of their promise, I’ve never managed to get an AI model to write even a single paragraph that isn’t clearly and obviously someone else’s voice. But does that actually matter these days?
Much like Tomasz, I periodically get emails from readers asking about the authenticity of my content (or, in some cases, expressing their appreciation for something I wrote that was clearly not AI-generated). In his post, Tomasz hypothesized that,
“In the age of slop, readers test authenticity.”
I think he’s right on that. Increasingly, I find myself reading posts, articles, emails and even text messages with the not-so-subconscious question, “was this written by AI?” going through my head.
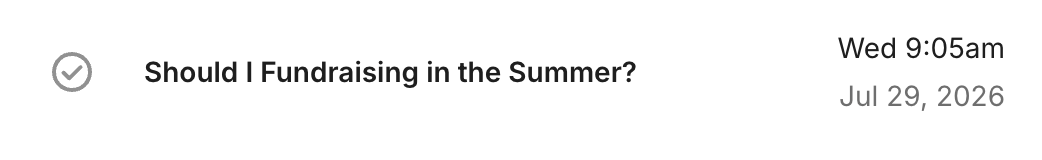
Nobody who received this email questioned if it was from a human… 😂
A few months ago, I sent out emails to a number of people in my network asking if they would volunteer as mentors for this year’s Founders Day. It was a pretty simple email that included high-level details about the event plus the ask (“Will you mentor this year?”). Most of the responses were a few words or less (“I’m in!” or “Sorry, I’m out of town that week.”), but one of them stuck out:
“Hi Chris,
Great to hear from you, and count me in. I'd be glad to mentor again this year.
The new format sounds excellent. Moving everything to South Flats and giving it a festival feel is a smart change, and having the conference, mentoring, and networking party all in one place will make the day flow much better.
The mentor ask works for me. Happy to wear the lei and spend time in the mentor area during the day, so just send the signup sheet once logistics firm up and I'll pick a slot. The mentor and speaker dinner sounds great too, so keep me posted on the date.
I'll keep the details to myself until the announcement goes out. Looking forward to August 20.
Thanks,XXX”
I immediately texted the sender,
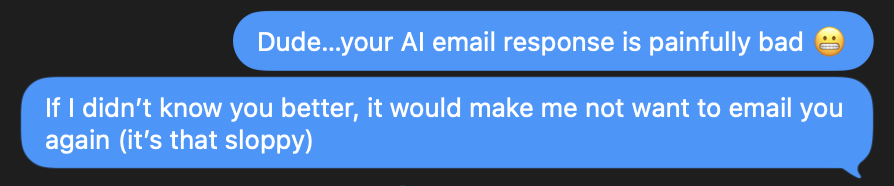
His response?
Since AI came on the scene, a subset of the residents of Startupland™ have become obsessed with efficiency. A number of people I know have spent a mind-boggling amount of time spinning up agents to handle every task imaginable.
And in more than a few cases, that includes an agent to act as the frontline interface for all of their personal communications.
A few months ago, I wrote about the rise of AI slop on social media and how relying on AI to generate posts is now likely to result content that under-performs. I noted that after reading dozens of nearly-identical AI-authored comments, “…my eyes glazed over. Eventually, I stopped reading and responding.”
What happens when the AI slop isn’t confined to LinkedIn and X posts and finds its way into the emails and text messages you send to your coworkers, clients and even your friends?
Lately, I’ve started to receive emails from personal friends and long-time colleagues that were clearly written by AI. Most aren’t quite as egregious as the example above, but most of the time it’s pretty obvious. When I receive such emails, I find myself both less likely to read to the end and less likely to respond to it.
More and more, I find myself less likely to want to email that person at all.
There’s a certain degree of trust that exists in one-to-one communication. For the most part, I assume that if I send you an email, you (meaning, the real you) will read it — or at least scan the header before deciding whether or not to answer it. Similarly, when I receive an email from you, I assume that you (the real you) is the person who wrote the email.
Sure, some people have EAs who read and respond to emails for them. But long-established etiquette is that if a human EA writes an email on someone else’s behalf, they initial it in order to make clear that the email was written by someone else. Rarely do EAs actually ghost-write personal communications (though in Startupland™ that behavior is more common than in the rest of the world).
And while plenty of people use tools like Grammarly to improve their writing and leverage email templates / snippets to be more efficient, you can generally tell that the core was still written by the original author. The voice is still theirs.
So where do we go from here?
On the one hand, part of me wonders if we’re experiencing a similar dynamic to what happened when Calendly first came on the scene (when many people were upset by the “audacity” that someone would dare send them a link to fit into their calendar, rather than engaging in the time-consuming back-and-forth of scheduling). From that perspective, it seems reasonable and broadly net positive to have AI handle communication tasks that don’t really need a human-in-the-loop.
But having AI handle basic scheduling tasks or dealing with customer support is very different from having an agent pretend to be you in conversations with people you know personally. And perhaps that’s the core issue here. There’s a breach of etiquette and trust that seems to be happening with a subset of early adopters of AI. And they’re not fooling anyone.
I’m very transparent about the fact that I use an AI scheduling assistant, But I’ve never, ever had it pretend to be me. And I think that’s important.
At the end of his post, Tomasz noted,
“AI is a poor ghost writer, but a great editor.”
I suspect that in the very near future, we’ll see a similar backlash to AI slop in personal emails to what we’ve seen in social media and cold emails. Use AI as an editor. Offload tasks in a transparent manner to agents. But stop having AI pretend to be you. The incremental gain in productivity is likely costing you more than you realize.
That particular friend I referenced earlier who I emailed about Founders Day? I haven’t sent him a single email since.
Because I know he’s not the one reading it.
Things I Think I Think - Q2 2026
Against the backdrop of this summer’s competition for global sport supremacy, here are 5 Things I Think I Think - Q2 2026 Edition.
There is a magical time once every 4 years when the world comes together around the beautiful game. Given all of the geopolitical changes that have taken place over the past few years, it’s hard not to smile at the fact that cohost United States will play its first elimination game today, on Canada Day, while Canada will next take to the pitch on the 4th of July.
Let’s go Canada! 🇨🇦
Set against the backdrop of this summer’s competition for global sport supremacy, here are 5 Things I Think I Think - Q2 2026 Edition:
1. Fast and then Slow
The frantic pace of investment that characterized the first quarter of 2026 continued into Q2. Megafunds, in particular, continued to throw around their proverbial weight, with numerous preemptive rounds happening at the start of the quarter (especially at Series A and B). I suspect that when the statistics for Q2 eventually see the light of day, we’ll see that valuations for the top 5% of companies continued to climb sharply through Q1 and into Q2.
But a funny thing happened as May rolled around: the pace of deals started to slow. Gradually, then suddenly.
In particular, the preemption of Series A and B rounds that was prevalent during the first third of the year dropped off rather dramatically towards the end of Q2. I watched a number of VCs that had been aggressively pursuing preemptive deals downshift their activity mid-quarter. Almost in sync, a number of founders I know who were looking down the barrel of preemptive term sheets stepped back from the alter, with plans to revisit in the fall.
It’s not often that you see VCs and founders adjust their activities in parallel. In my inaugural “Things I Think I Think” post back in 2023, one of my observations was about Canadian founders lagging in their acceptance of and adjustment to changes that were happening in the market post-ZIRP. So what happened in Q2 was quite unusual (but something I view as a strong positive). It wasn’t so much a correction in the fundraising market as a mutual, unspoken agreement by both sides to hit the pause button.
Coming into Q2, I had spoken with both VCs and founders who felt that they had no choice but to play the “preemption game”. As alluded to in my Q4 2025 update, investors fearful of missing out on the next OpenAI or Anthropic were driving “…a degree of preemption and FOMO for hypergrowth AI startups that’s on par (if not greater) than what happened during ZIRP.” At the same time, a number of founders I spoke with felt like they had an obligation to entertain preemptive investor interest. Many of them were spending considerable cycles on investor meetings even though they already had plenty of money in the bank.
By the time June came around, the slowdown in activity had expanded well beyond the “cease fire” in preemptive investments. Many VCs I know — from Pre-Seed to Series B — had all but stopped taking new meetings by the start of June. Perhaps it was a similar desire to hit pause and revisit their AI-related investment theses. Perhaps it was simply a weariness after more than a year of frenetic activity. Regardless, this summer is going to be a particularly bad time to fundraise (but a great time to be heads down on your business).
2. The IPOs are Coming! The IPOs are Coming!
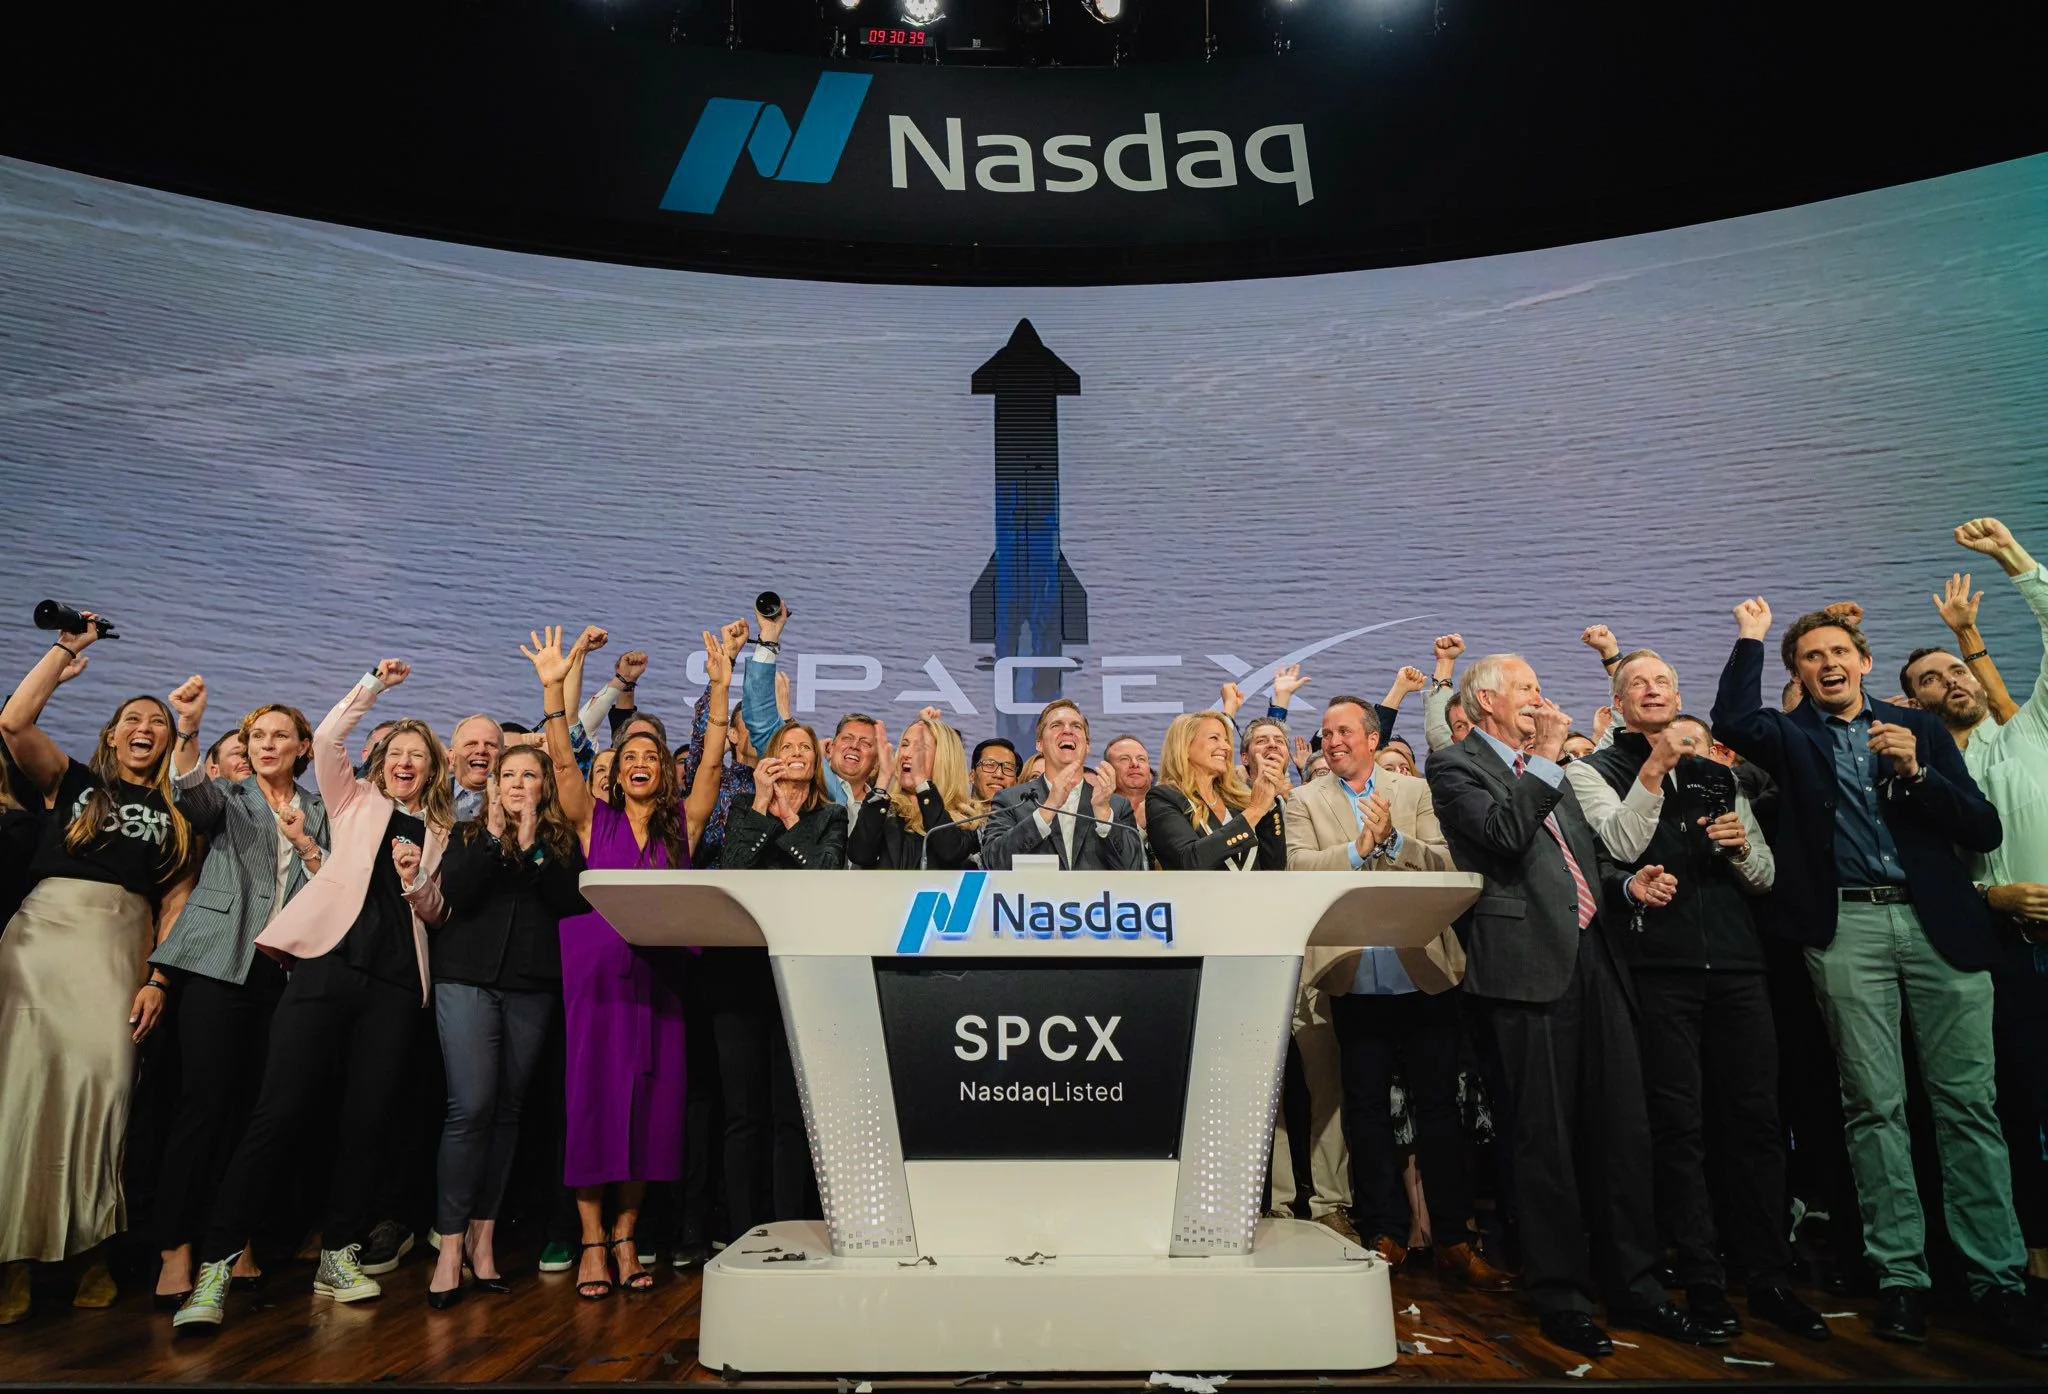
Q2 saw the first of three potentially massive tech liquidity events with SpaceX’s record-breaking IPO. But it was the other two IPOs on the horizon — from Anthropic and OpenAI — that had a more immediate impact on the behavior of many VCs.
As I alluded to above, a lot of the high-octane investor behavior over the past year has been driven by VCs desperately trying to replicate investments in Anthropic and OpenAI. Both companies have achieved unprecedented user adoption, revenue growth and — most appreciated by investors — valuation growth (aka markups). And, until recently, both seemed on a path that would quickly translate those paper gains into similarly unprecedented IPOs (DPI!).
But what seemed like surefire wins suddenly became not-so-certain. Anthropic’s smooth sailing hit bumpy seas as it repeatedly found itself in conflict with the U.S. government, while ongoing questions about OpenAI’s business fundamentals has led to speculation that it may delay its IPO until 2027.

Pete the Cat, early-stage VC
As the shine began to come off these two industry darlings, VCs slowly started to remove their rose-colored AI glasses. The slowdown in preemptive activity I described above was very much triggered by the recognition that, despite their unprecedented growth trajectories, the path from inception to IPO for AI-based companies is still a bumpy one.
To be clear, investors are by no means giving up on AI (many are still wearing very thick rose-colored AI glasses, albeit with a slightly lighter tint). The fact that Anthropic and Open AI have hit bumps in the road won’t damper VC enthusiasm for AI’s industry-disrupting potential. Rather, investors are adjusting their expectations when it comes to the trajectories of these companies, particularly as it relates to time-to-liquidity. Ultimately, that will affect the rate at which preemptive rounds occur and the valuations at which those rounds happen.
But make no mistake, once fall comes around, VCs will once again be champing at the bit to invest in the latest-and-greatest AI startups.
3. Agents Cross the Chasm
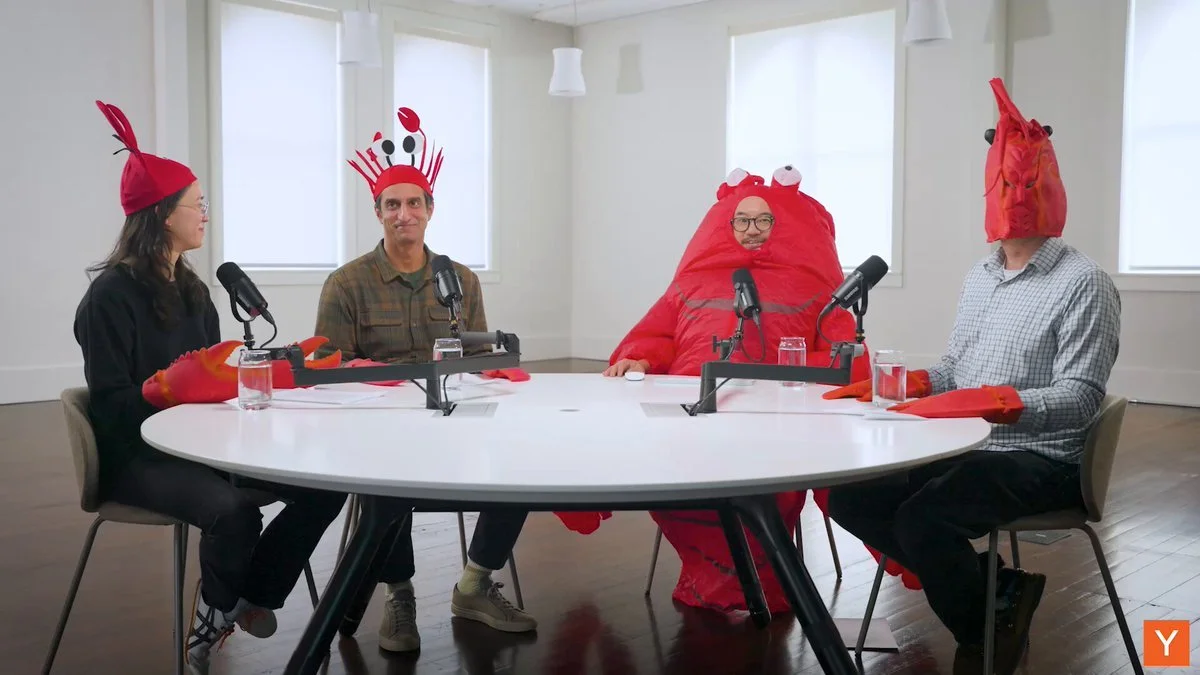
When I wrote my end-of-year update six months ago, nobody had heard of moltbot clawdbot OpenClaw. By Q1, prominent VCs were showing up on podcasts wearing lobster costumes. But the technology was still barely usable. We were still very much at the Homebrew Computer Club phase of the technology adoption lifecycle.
But like many things related to AI, the rate of progression from barely usable open source “projects” to relatively-stable early “products” has been unprecedented. This past quarter, a number of companies came to market with purpose-built agent products, ranging from more mature open source projects, like Hermes, to agents for managing family calendars. Howie, an email scheduling assistant that I previously wrote about, recently released “Howie Blue”, a full-blown personal agent that integrates with both email and iMessage (hence the name).
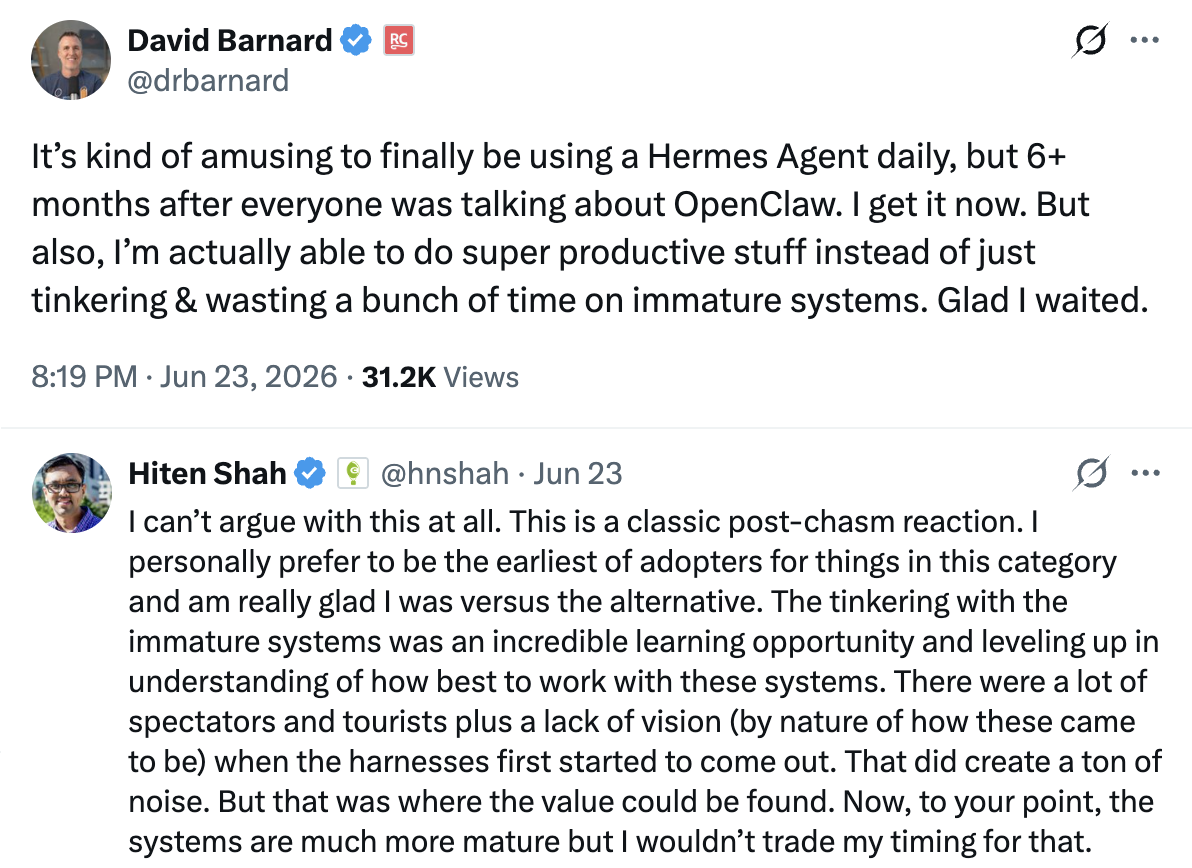
My friend Hiten did a great job of describing the value that many early adopters got from working with nascent agent platforms, though I’m not sure that the general populace had nearly as much ROI to gain from adopting the technology so early. But with so many agent-based products now coming to market, the bar has never been lower to start using AI agents.
I expect that adoption rates of agent-based products will skyrocket as we head into the back half of the year, especially in Startupland™. For founders and investors alike, the takeaway should be this: if you aren’t already using agents in some form or another (not just within your company, but you personally) take some time this summer to get started. It doesn’t matter if you’re rolling your own open source agent or signing up for one of the many turnkey solutions hitting the market. Do something.
Continuing to sit on the sidelines won’t land you in a “permanent underclass” (despite what many in Silicon Valley continue to believe), but it will absolutely leave you at an increasing competitive disadvantage.
4. Canadian VC on the Brink
For the past few quarters, the ongoing bifurcation of venture capital has led to a relatively small number of big VC firms capturing an increasing percentage of LP dollars. This shift is happening all over the world, but the particular manner in which it has manifested in Canada has the potential to completely devastate the country’s tech sector.
RBCx recently published its mid-year report on Canada’s VC market, which included a staggering claim: as of the end of 2025, the country’s emerging managers (new VCs who are on their first, second or third fund) have raised 36% less capital than projected. For a country that already has too few early-stage VCs, a lack of fundraising by emerging managers is nothing less than an existential threat to its entire tech sector.
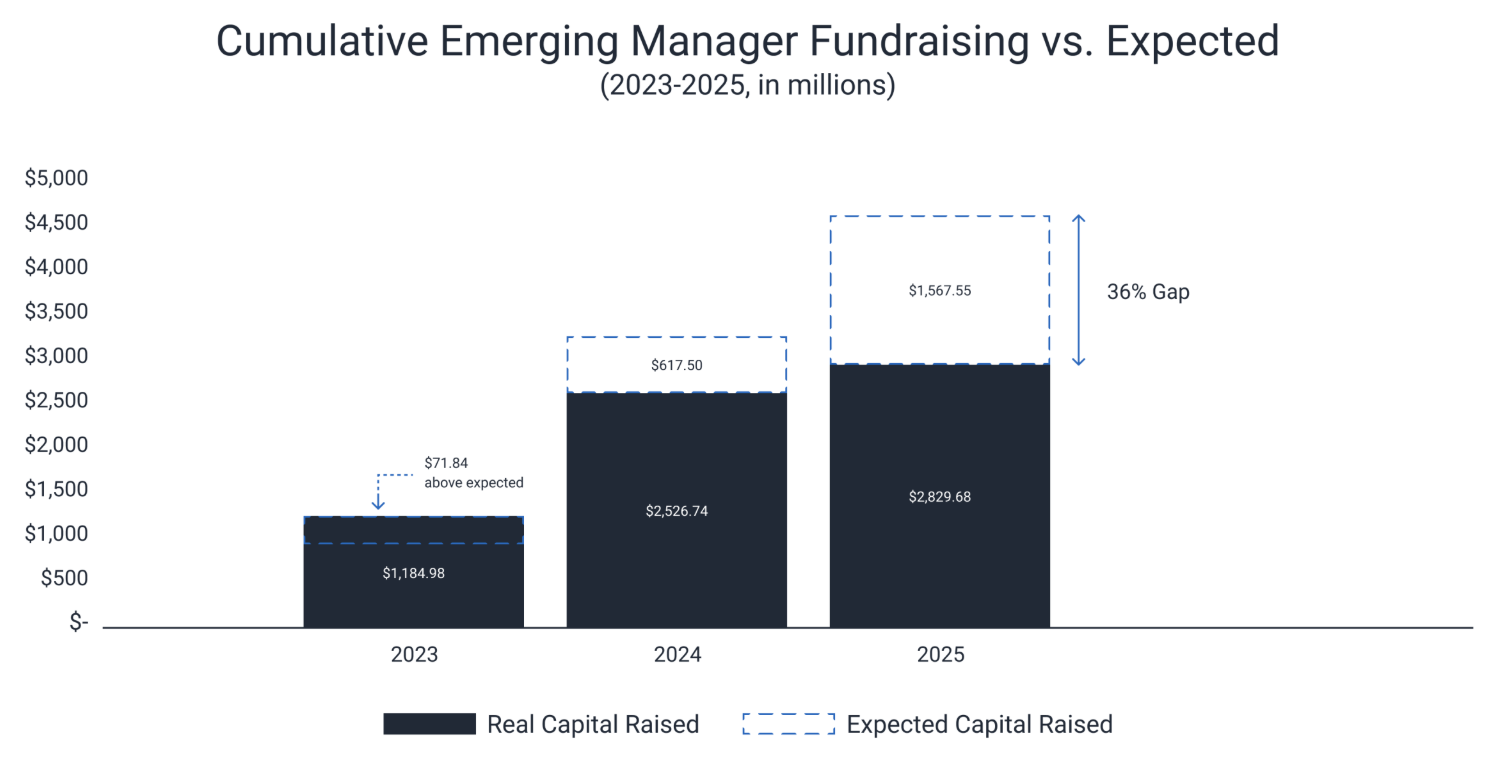
A lack of support for emerging managers isn’t a new phenomenon in Canada. In fact, I wrote about it 3 years ago. But the implications of the current prolonged drought has the country on the precipice of disaster — whether or not its leaders realize it.
Why? Emerging managers overwhelmingly invest at the earliest stages. They also tend to bring new ideas and new perspectives to startup ecosystems. That frequently leads them to be the first check into companies with very different profiles to what “old guard” VCs back, which is key to an ecosystem’s ability to innovate and drive long-term growth. Lisa Cawley, Managing Director of Screendoor, a leading fund-of-funds that invests exclusively in U.S.-based emerging managers, described the critical role of new VCs to the Wall Street Journal last year,
“New VC firms matter; they have an opportunity to drive competition and disrupt incumbent complacency. The question shouldn’t be ‘How many VCs,’ but why are there so many mediocre ones?”
That said, a dip in the number of early-stage VCs in an ecosystem typically doesn’t threaten its long-term survival. But time is not on Canada’s side. Its unique existential threat comes from the fact that its neighbor to the south is home to the tech world’s largest, fastest-moving and most risk-taking capital market. At a time when fewer Canadian VCs are willing (or able) to write the first check into first-time founders, a growing number of local founders have simply stopped looking for capital at home. Instead, they’re going straight to Silicon Valley.
And in many cases, those first-time Canadian founders are choosing to move to the U.S. as part of the process.
A handful of efforts have recently emerged trying to address the lack of capital flowing to emerging managers in Canada — notably the launch of the Canadian Startup Capital Association (CSCA) in April — but the country needs to make some bold, systemic moves fast. The last time Canada experienced a dip in the number of active VC firms, most Silicon Valley VCs were unwilling to invest in Canadian startups. That’s no longer the case.
If 2026 ends with a similar lack of fundraising success for Canada’s emerging managers, by this time next year there may not be much of a startup pipeline for the rest of the ecosystem to support.
5. We Lost a Giant
Last week, Om Malik passed away after a prolonged health battle. Countless posts and articles have been written about him in the days since. This observation from John Gruber does a good job of capturing how many of us in the tech industry currently feel,
“it is a profound irony that a man with such a big and beautiful figurative heart could have such a lousy literal one.”
I only met Om a handful of times over the years, so I can’t say that I knew him well, but his work and legacy had a profound impact on my journey.
His namesake publication, Gigaom, was unlike any other tech publication at the time (or since). It seamlessly blended the “breaking news”-style coverage of Silicon Valley that was on the rise with a deeper level of analysis — about both technology and business — that simply didn’t exist anywhere else. The approach stemmed from Om’s personal style of journalism, which Stacey Higginbotham described thusly,
“He was the smartest guy writing about really geeky tech and putting it into context. He was able to discuss the nuts and bolts of technology and then extrapolate what new advances would mean and how people would react.”
Gigaom focused primarily on infrastructure and enterprise software, which put both Aster Data and DataHero squarely in its coverage box. In 2009, the publication brought on a dedicated infrastructure/data writer named Derrick Harris, who I quickly got to know and soon became friends with. He shared his own thoughts on Om’s passing here.
For more than 5 years, my professional world existed very much within the orbit of Gigaom. I got to know many of the exceptional writers that passed through its doors and had the privilege of speaking at several of the company’s influential conferences. To this day, the way in which I view tech journalism and its potential for positively influencing the world while holding people in power accountable is overwhelmingly influenced by my years interacting with the team at Gigaom.
In a world where tech media is increasingly driven by algorithms and agendas, the type of deep, thoughtful writing that Om championed is frustratingly hard to come by. If you haven’t already checked out Crazy Stupid Tech, the blog Om launched last year with Fred Vogelstein, I strongly encourage you to do so.
On Resilience, Rockets and IPOs
Plenty of stories have been written about the history of SpaceX. This is not one of those stories.
Plenty of articles have been written about the history of SpaceX. Stories of how the company nearly failed after its first three rockets exploded. About how it almost ran out of cash during the financial crisis and Elon Musk had to borrow money to keep it afloat. About how its recent IPO minted the world’s first trillionaire.
This is not one of those stories.
Nearly 25 years ago, I arrived at Stanford as a wide-eyed Canadian kid excited to study computer science at one of the best schools in the world. I did my undergrad at Simon Fraser University, which I imagine was a pretty typical CS experience in those days (insofar as the computer science kids were mostly the weirdos in the corner who no one else talked to).
Stanford was different. Most people truly have no idea just how special a place it is. At Stanford, everyone is an uber nerd in whatever field they chose to study. Computer science was one of the larger graduate programs in those days, but there were programs and sub-programs for just about every field imaginable, from financial mathematics to international policy.
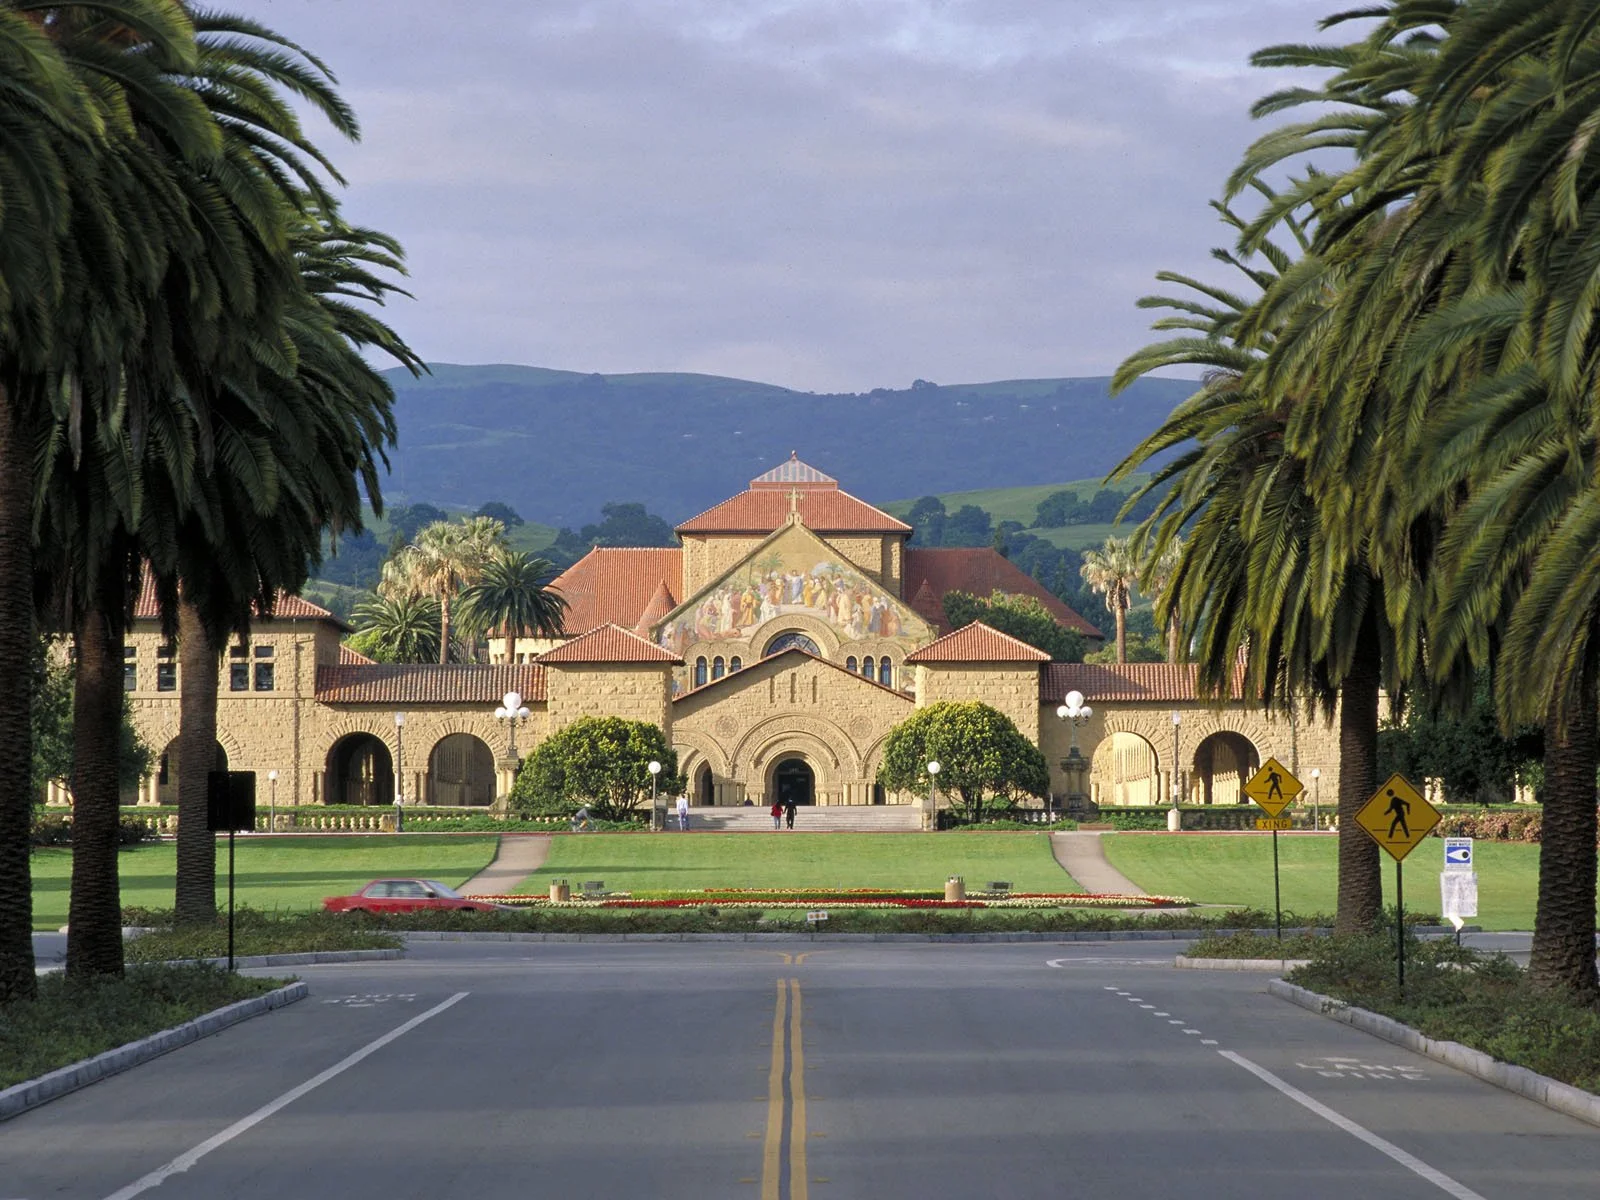
There’s no drive in the world quite like this one
Almost everyone at Stanford lives on campus, so you meet all sorts of exceptional people from different programs. I ended up with a bunch of friends who were in aeronautics and astronautics (colloquially knows as “aero-astro”). Kids who were studying to be literal rocket scientists.
Masters degree programs are generally short (1-2 years), so it wasn’t long before conversations shifted from how excited we all were to be at Stanford to what we were going to do next. As graduation approached, I noticed that many of my aero-astro friends didn’t have the same level of excitement as the rest of our group. I recall asking one of those friends about his post-Stanford plans. He shrugged his shoulders,
“There aren’t that many good jobs,” he lamented. “You can work for a bloated dinosaur like Lockheed or Northrop, try to get a government job (NASA, ESA, etc.) or go into academia. That’s about it.”
I was pretty shocked to hear him say that. These were some of the smarted people I had ever met, yet there seemed to be no path forward in their chosen field other than becoming a cog-in-the-wheel at a giant corporate. At a time when fast-growing software companies like Google, Amazon and Apple were hiring just about anyone they could, it was a sharp contrast to my own experience.
A few weeks later, I was hanging out with another aero-astro friend and again got to talking about our summer plans. She casually mentioned that she was about to join a startup. Apparently, a member of the famed PayPal mafia had a background in physics and decided to use his newfound wealth to try to start a new rocket company.
After graduation, my friend moved to LA and joined Space Exploration Technologies Corporation. That was 23 years ago.
The original SpaceX “office” was in a nondescript warehouse in El Segundo, a fairly industrial corner of west LA just north of the beach towns of Manhattan Beach, Hermosa Beach and Redondo Beach. I remember visiting it for the first time and being shocked to see a full-sized rocket being assembled just down the street from strip malls and drive-thrus.
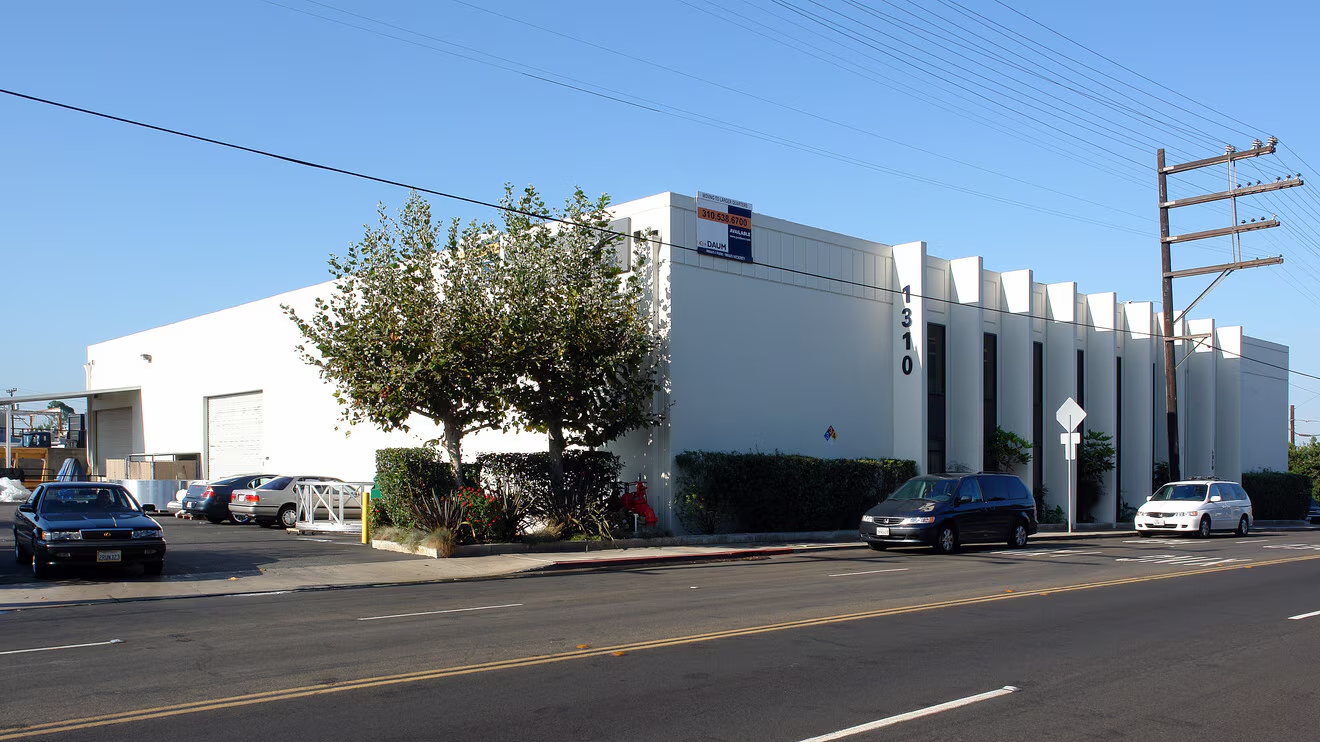
SpaceX’s original office
At a time when Silicon Valley offices were already overflowing with perks and creature comforts, the SpaceX warehouse was an exercise in austerity. There were no foosball tables. No video games. Just computers flashing with CAD designs and piles of wires, metal sheets and manufacturing equipment. (Actually, there was one fun item in the office — Elon owned one of the first Segways and he was eager to show anyone who stopped by what the “future” of urban transportation looked like.)
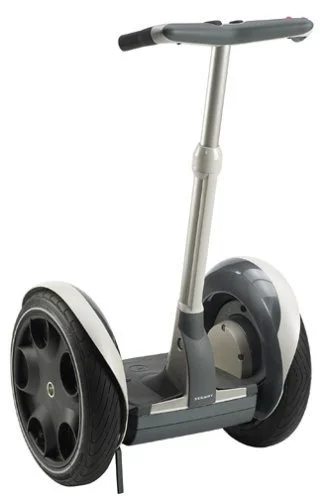
Bizarrely, I once spent a Saturday afternoon driving one of these around the original Merlin engine
In contrast to typical software companies, the employees of SpaceX weren’t shipping something new every day. They didn’t get the dopamine hits from watching a new product go viral or reading the reviews about a feature they’d just released. They met up as a team each day before work, went surfing to build camaraderie (pretty cool, if you ask me) and then headed into the office to toil away. And they quietly did that for years.
The first launch attempt happened in 2006, 4 years after SpaceX was founded. The first successful launch took another 2 years. That’s 6 years from the founding of the company until the first rocket made it into orbit.
Aster Data went from founding to being acquired by Teradata in 5.5 years. DataHero was acquired 4.5 years after it was founded. It took longer for the SpaceX team to complete a single “end-to-end test” than it did for either of the startups I was a part of to complete their entire lifespan.
Now multiply that by 4.
Most people in Startupland™ can’t fathom the idea of working for a single company for more than twenty years. To be a “lifer” in tech is generally seen as a negative. The implication is that you got comfortable. You couldn’t keep up. You lost your drive and your ambition.
Silicon Valley’s culture is far more mercenary than missionary. Many engineers hop from startup to startup, collecting stock options and increasingly ludicrous salaries with little regard for what they’re actually building. The skillsets of most people in tech are so transferable and so in-demand that an incredible number move on the minute things get uncomfortable (or the moment they see a shinier opportunity). I’ve lost track of how many people I’ve met who brag about being an early employee at Uber, Pinterest or some other hotshot company, only to discover that they barely lasted a year there.
Until recently, “going to another startup” simply wasn’t possible for aero-astro engineers. For the early team at SpaceX, failure meant having to go work for a bloated corporate. Or worse, the government. There was no fallback plan.
This weekend, a number of those early SpaceX employees woke up to find themselves on the receiving end of generational wealth. Each and every one earned it in a way that few people in Startupland™ can relate to: a two decade-long grind that, for most part, was completely unglamorous. It’s the furthest thing from an overnight success that one can imagine and I am genuinely happy for each and every one of them.
At a time when AI is making it easier than ever for founders to pivot and early employees to jump ship, I’m reminded about what Silicon Valley used to be about: the weirdos in the corner quietly and unglamorously trying to change the world.
Let’s get back to that.
What’s Going On With Accelerators?
With more accelerators and fellowships than ever, it might seem like there’s an overabundance of options for founders to choose from. What we’re seeing is actually a clustering around two very specific approaches to hands-on investing.
I’ve written a lot lately about the ongoing bifurcation of venture capital and its implications for fundraising (both in my quarterly updates and in dedicated posts, like this one on early-stage investing).
One prediction I made last year was that we would start to see more early-stage investors lean in to the “hands-on” styles of investing that were more common in years past. As megafunds ramped up their early-stage activity, many Seed VCs would be crowded out. They would in turn head upstream to the “safety” of Pre-Seed. The increased competition at Pre-Seed would force investors to find new ways to differentiate themselves in the eyes of both founders and LPs.
And that would lead to more accelerators,
“…we’re seeing a resurgence of both small, dedicated accelerators and offerings from Seed-specialist VCs…it feels like the pendulum is swinging solidly back from the “hands-off” investing style of the ZIRP era to the more “hands-on” style of years past. At a time when AI is making it cheaper than ever to get a company off the ground, I think we’re going to quickly see a new level of competition amongst credible accelerators (and between accelerators and pre-seed VCs).”
Sure enough, the accelerator landscape has gotten a lot more crowded since I wrote that post.
Since the beginning of the year, megafund a16z significantly ramped up their speedrun team (I might have done reference calls for some people they were looking to hire 👀). They followed that up by launching a new fellowship program called “alpha” a few weeks ago.
Speaking of alpha, the big dog of accelerators, YC, didn’t sit long with its earlier assertion that, “…the total number of startups going through the program each year will hold steady at about 500…” The recently completed W26 batch had nearly 200 companies (i.e. they’re currently on pace to invest in 800 startups in 2026).
And that’s just the start. Here is some of the other activity that took place across the accelerator landscape during the first quarter of 2026:
London-founded fellowship program Entrepreneurs First completed its move to San Francisco and unveiled a fresh $200M fund
Accelerator upstart Neo announced a new Residency program for college students
Montreal-based AI research institute Mila launched a new venture-building program for AI research scientists as part of a $100M “venture scientist fund” announced earlier in the year
South Park Commons shared its plans to raise a new $500M fund for its self-proclaimed “anti-accelerator”
Taken together, it might seem like there’s now an overabundance of programs for founders to choose from. But if you look closer, what we’re seeing is actually a clustering around two very specific approaches to hands-on investing:
Accelerators as the New MBA
Fellowships as the New Montessori
Let’s dig deeper into each of these trends.
Accelerators as the New MBA
In the early days of accelerators, programs like YC, Techstars and 500 Startups didn’t have nearly the prestige of today’s industry leaders. In fact, it was quite the opposite. Amongst many founders and investors in the startup world, accelerators were seen as something of a crutch. They were the thing you went to if you couldn’t figure it out on your own.
Fast-forward 20 years and the perception is very different. Not only are accelerators broadly accepted as a reasonable path for first-time founders to take, but having simply attended a top accelerator is seen by many as a mark of credibility and prestige. Sound familiar?
“You got into Harvard…you must be smart!”
“You got into YC…you must be smart!”
Last year, David Crow wrote about the increasing similarities between top accelerators and universities. He noted that,
“In the past, ambitious graduates invested in themselves by going to grad school. They spent $100,000 on an MBA, law degree, or medical program as their path to impact.
Today, ambitious people might choose YC or Speedrun instead…
YC and Speedrun are not just accelerators; they’re the new professional schools of venture.”
I’ll take it a step further: not only are ambitious individuals increasingly looking at top accelerators as a credible path to advance their careers, accelerators are increasingly selecting founders in ways that look a lot like how elite MBAs choose students.
And I’m not the only one.
I recently caught up with a friend who spent many years as a VC at one of Silicon Valley’s top-tier funds (he also happens to have an MBA from a prominent business school). In discussing the evolution of the early-stage landscape, he suggested that top accelerators have very intentionally moved towards a model for selecting founders that mirrors how top MBA programs select students:
“At this point, [top accelerators] know the “shape” of founders that Tier 1 VCs like to invest in. The schools they went to, the companies on their resume, the traction points that matter. The things that get an IC* comfortable investing in a company that maybe hasn’t done anything yet.
It’s the same way MBA programs cater to top employers. What undergrad did the student go to? Where did they intern? What test scores do they need if they came from a lesser-known school? They’re trying to maximize the chances that an incoming student will land a job with a name brand employer, regardless of what they actually do during business school.”
* investment committee
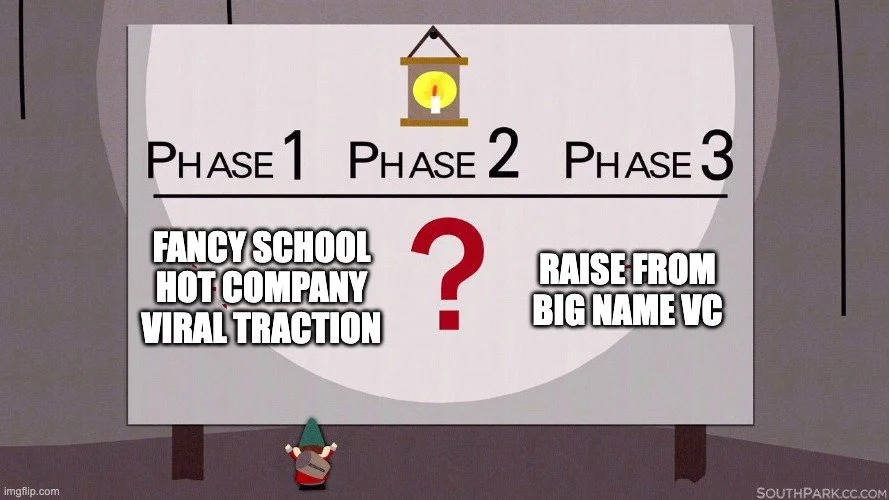
If you read my recent post on Hunters vs. Farmers, you might be getting a sense of deja vu. That’s because what we’re talking about here is the approach that “hunters” typically take, but within the context of a segment of venture that we historically think of as “farmers”:
“Early-stage hunters focus on pedigree and traction as their primary signals. Things like:
Graduating from a top school or program (Stanford, MIT, Waterloo, IIT Bombay, Thiel Fellowship, etc.)
Early employees that left “hot” companies
Repeat founders
Hot sectors
Virality / significant early traction
They’re generally betting on the correlation between pedigree and outcome (or, at least, pedigree and quick markups).”
This is exactly what elite MBA programs do. They bet on the correlation between pedigree and outcome, where outcome is “gets hired by a top-tier employer”. Today’s top accelerators are increasingly converging on a similar model. And you can see it in their marketing,
“Want to maximize your chances of landing a job with [top employer]? Apply to Harvard!”
“Want to maximize your chances of raising a round from [top VC]? Apply to YC!”
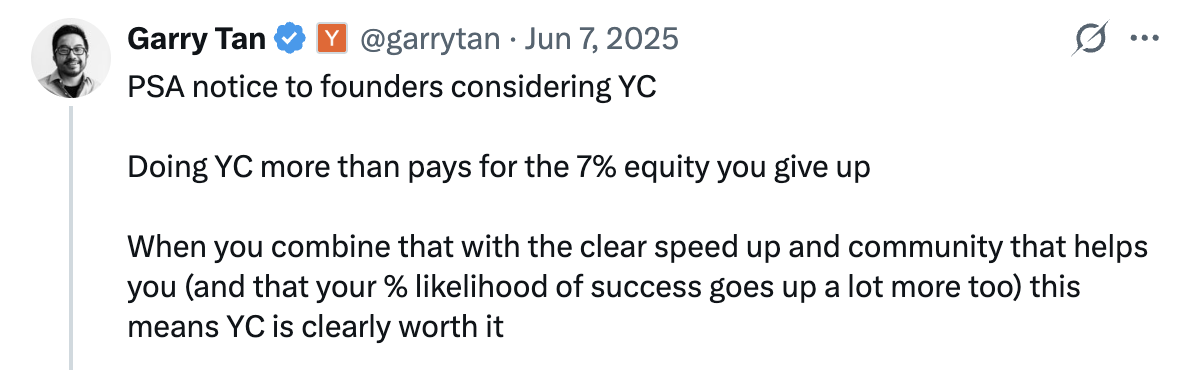
This certainly isn’t a bad approach — for either the accelerators or the founders.
That said, it’s worth noting that what’s happening at the top of the accelerator pyramid right now is very much influenced by a considerable imbalance in supply and demand. More and more qualified founders are looking for the “cheat codes” that come with the brand recognition and alumni networks of top accelerators. Yet there are very few programs that credibly deliver consistent outcomes along these dimensions (particularly in the aftermath of 500 Startups and Techstars both effectively failing). With so many qualified startups and so few spaces available in each program, founder pedigree naturally becomes a more prominent factor in selection.
Which means that a significant number of ambitious founders — especially founders outside of California and those from schools, companies and backgrounds that don’t neatly fit the typical Silicon Valley mold — are struggling to gain acceptance into these elite programs.
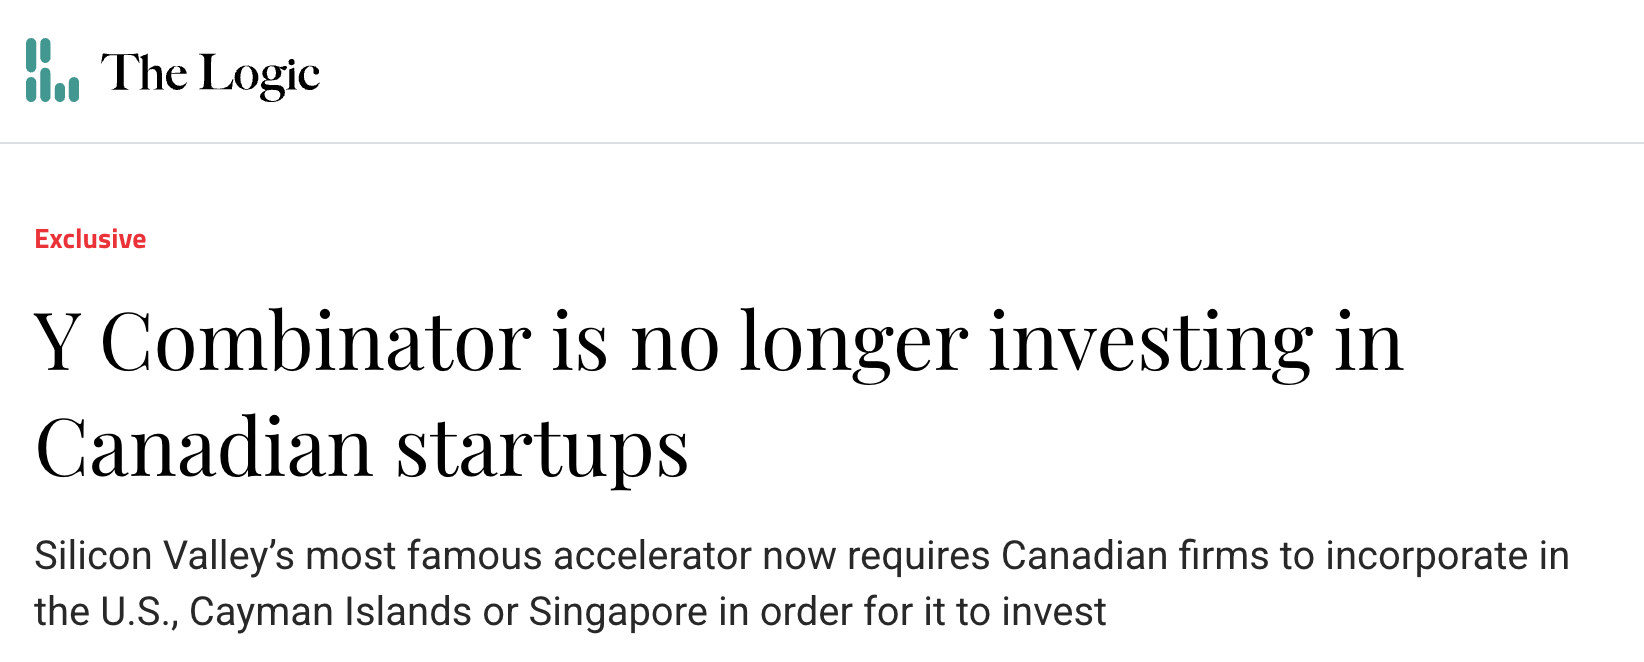
When the supply-demand curve is so imbalanced that an entire country doesn’t make the cut
So why aren’t we seeing more “elite MBA programs” emerge if the supply-demand curve is so imbalanced?
Despite the incredible demand for top tier Silicon Valley-based accelerators, only two platforms founded in the past decade have found success: Neo starting in 2017 and speedrun (from a16z) in 2023.
It turns out that creating a full-fledged accelerator platform from scratch is hard. It takes a lot of resources, investors who are experienced evaluating startups with virtually no traction, and an incredible number of high-quality, properly incentivized mentors. Creating a high-quality accelerator is, in fact, really, really hard.
But it is doable. Not only that, with so much latent opportunity — especially when it comes to startups outside of California — more elite Silicon Valley-based platforms are undoubtedly going to emerge. It’s just a question of when.
In the meantime, the majority of early-stage investors that have started rolling up their sleeves are taking a different approach. One that focuses almost entirely on the potential of individual founders while forgoing much of the complexity of a full-blown accelerator…
Fellowships as the New Montessori
If accelerators like YC and speedrun are the new MBA, then fellowship programs like South Park Commons, HF0 and Entepreneurs First are the new Montessori school.
If you’re unfamiliar with the term “Montessori”, it is an approach to early childhood education that focuses on encouraging children’s natural interests rather than providing formal, structured education. Montessori programs are designed around student-directed work, with a particular emphasis on uninterrupted work periods. The approach is based on the idea that children are naturally eager for knowledge and the primary role of teachers is to guide and mentor them.
At a high level, Montessori schools take a group of highly-motivated individuals and place them in a room with a handful of experienced, light-touch mentors in the hope of creating magic.
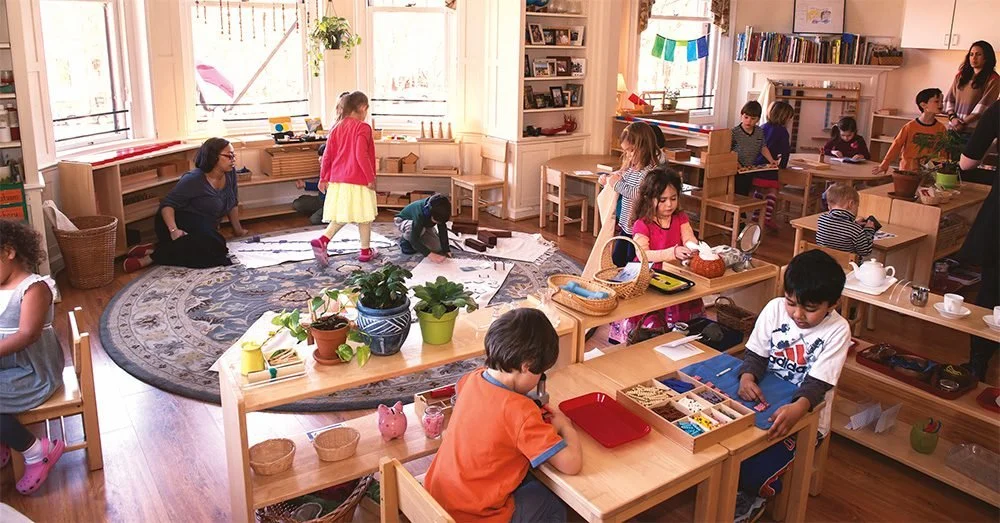
A Montessori “hacker house”
Which brings us to fellowships.
Fellowship programs invest in aspiring founders based primarily on their experience and pedigrees. These individuals are placed into a cohort and participate in activities designed to guide them towards founding high-potential companies (with a particular emphasis on ideation and cofounder matching). In other words, they take a group of highly-motivated individuals and place them in a room with a handful of experienced, light-touch mentors in the hope of creating magic.
Over the past few years, the number of fellowship programs has exploded. Not only are there an increasing number of standalone platforms (like South Park Commons, HF0 and Entepreneurs First), but many existing VCs have launched fellowship offerings as a means to increase their access to high-potential founders at the earliest stages. Some examples include a16z’s “alpha” fellowship (mentioned above), Conviction Partners’ “Embed” program, and Afore Capital’s “Founder in Residency” program.
Earlier, I alluded to the fact that fellowship programs forgo much of the complexity of a full-blown accelerator. Let me expand on that point — as it’s key to understanding why so many fellowship programs are emerging.
Both fellowship programs and Montessori schools are rooted in the notion that individual participants are highly-motivated and eager for knowledge. The corollary of that belief is that mentors need not be heavy-handed (either in their depth of programming or the help they provide). Montessori programs don’t so much teach children as they guide them on where to look for their own answers. Similarly, fellowship programs don’t focus on the type of “startup 101” programming that accelerators historically delivered. Instead, they provide frameworks for aspiring founders to search for answers while making introductions and connections to help them progress.
Guess what? That approach means fewer mentors, less time and effort developing programming, and significantly lower costs.
The simplest form of a fellowship offering is a VC partner providing regular mentorship and occasional connections to an aspiring founder. Which is exactly what many VCs have done for years through entrepreneur-in-residence (EIR) programs. From the perspective of traditional VCs, fellowship programs are little more than the cohort-ization (is that a word?) of something they were already doing.
Want to have your mind blown even further? Y Combinator — the world’s foremost accelerator — actually started out more like a fellowship program. Here is how Paul Graham originally described YC (then referred to as the “Summer Founders Program”):
The Summer Founders Program preserves many features of a conventional summer job. You have to move here (Cambridge) for the summer, as with a regular summer job. We give you enough money to live on for a summer, as with a regular summer job. You get to work on real problems, as you would in a good summer job. But instead of working for an existing company, you'll be working for your own; instead showing up at some office building at 9 AM, you can work when and where you like; and instead of salary, the money you get will be seed funding.
…
We'll have some smart people who are willing to talk over your plans with you, and suggest pitfalls and new ideas. We may also have connections to companies you'd like to do deals with. But how much you want to take advantage of our advice and connections is up to you.
We'll organize dinner once a week for all the Summer Founders, so you can meet one another and compare notes. We'll try to get some expert in technology, business, or law to speak at each dinner. But beyond that we'll be hands-off.

The first batch of YC’s “fellowship program”
To be clear, today’s top-tier fellowship programs provide significantly more that just a la carte mentoring and connections. They are full-blown platforms with programming and mentorship strategies that have been developed and iterated over many years. But the low “entry price” of starting a basic fellowship program, combined with the dramatic supply and demand imbalance I alluded to earlier (more and more founders looking for “cheat codes” but relatively few credible accelerators), is driving what I believe to be just the start of a wave of new fellowship offerings.
To recap:
The bifurcation of venture capital is forcing many VCs to invest earlier-and-earlier
Increased competition at the Pre-Seed stage is driving those investors to find new ways to differentiate themselves — which, for many, involves getting more hands-on with founders
Creating a new accelerator is difficult and prohibitively expensive for most VCs (a16z can afford to throw a ton of money at creating a new accelerator, but the funds who are moving upstream specifically because they can’t afford to compete against a16z most certainly cannot)
However, “systematizing” mentorship and/or scaling an existing EIR program is much more approachable for most VCs (and easy to justify from an ROI standpoint)
Bottom line: expect to see more and more fellowship programs emerge in the coming months (particularly from mid-sized Seed funds that are trying to figure out how to effectively compete at Pre-Seed).
On Terms and Terminology
Before I wrap things up, I want to share two final thoughts on terms and terminology:
On Terms
Many accelerators and fellowships are increasingly trumpeting large numbers when it comes to their investment amount. It’s not uncommon to see programs seemingly offering $1M of investment to startups.
But don’t believe everything you read.
The vast majority of accelerators and fellowships make either milestone-based or follow-on based investments. That means that (a) you might not receive the full amount, and (b) if you do, you may end up giving away a much higher portion of your company than you realized.
Consider the following examples:
Y Combinator
Top-line number: $500K
Actual initial investment: $125K for 7%
Follow-on investment: $375K (MFN)
a16z Speedrun
Top-line number: $1M
Actual initial investment: $500K for 10%
Follow-on investment: $500K (contingent on follow-on funding)
Entrepreneurs First (US)
Top-line number: $250K
Actual initial investment: $125K for 8%
Follow-on investment: $125K (MFN)
South Park Commons
Top-line number: $1M
Actual initial investment: $400K for 7%
Follow-on investment: $600K (contingent on follow-on funding)
Strictly speaking, there’s nothing wrong with this approach (in fact, it very much represents a standardization of the traditional venture capital strategy of “investing early and doubling down on winners”). But as a founder, it’s important that you read the fine print (here is a somewhat dated post on accelerator terms that I wrote a few years ago).
On Terminology
I’m not going dive into the etymology of (or debate over) terms related to accelerators / incubators / startup schools / etc., but I do think it’s important to share one point as it relates to fellowships (as they’re relatively new on the startup landscape and the language is still in flux):
The term “residency” is often used interchangeably with “fellowship” (e.g. Neo refers to its fellowship program as “Neo Residency”). However, it is also increasingly being used to differentiate between full-blown fellowship programs and lighter-touch coworking offerings that standalone fellowship programs are using to attract potential candidates (e.g. the Entrepreneurs First Residency and the South Park Commons Residency).
If you are considering a fellowship program, be sure to pay attention to the terminology and make sure you understand exactly what you’re applying to (lest you mistake one for the other).

Snakes and Ladders
Over the past 18 months, Silicon Valley has sped up. And most people outside of the Bay Area have no clue just how wide the chasm has become.
I spend a lot of time traveling back and forth between San Francisco and other cities across North America and the UK.
Every time I leave the Bay Area, I find that my internal clock naturally slows down, as it adjusts to the pace of life in whatever city I’m visiting. Conversely, the moment my flight lands at SFO, it ramps back up. My good friend Marvin Liao wrote about this last year (referencing a short but insightful post from Sriram Krishnan the year prior).
This particular phenomenon isn’t new to anyone in tech. Silicon Valley has always operated at a higher velocity than other startup ecosystems (similar to how New York has a different gear than comparable cities when it comes to other forms of white collar work). But over the past 18 months, something has been happening.
Silicon Valley has been speeding up.
And most people outside of the Bay Area — including founders, ecosystem supporters and even many VCs — have no clue just how wide the chasm has become.
The Resurgence of Silicon Valley
Over the past year, there have been a number of signals hinting at Silicon Valley’s resurgence. For example, the PitchBook-NVCA Venture Monitor, which provides a quarterly snapshot of the US venture landscape, has shown a steady increase in the percentage of US VC investment going to companies based in the San Francisco Bay Area (on both a dollar and deal count basis):

Source: PitchBook-NVCA Venture Monitor, Q1 2023 - Q1 2026
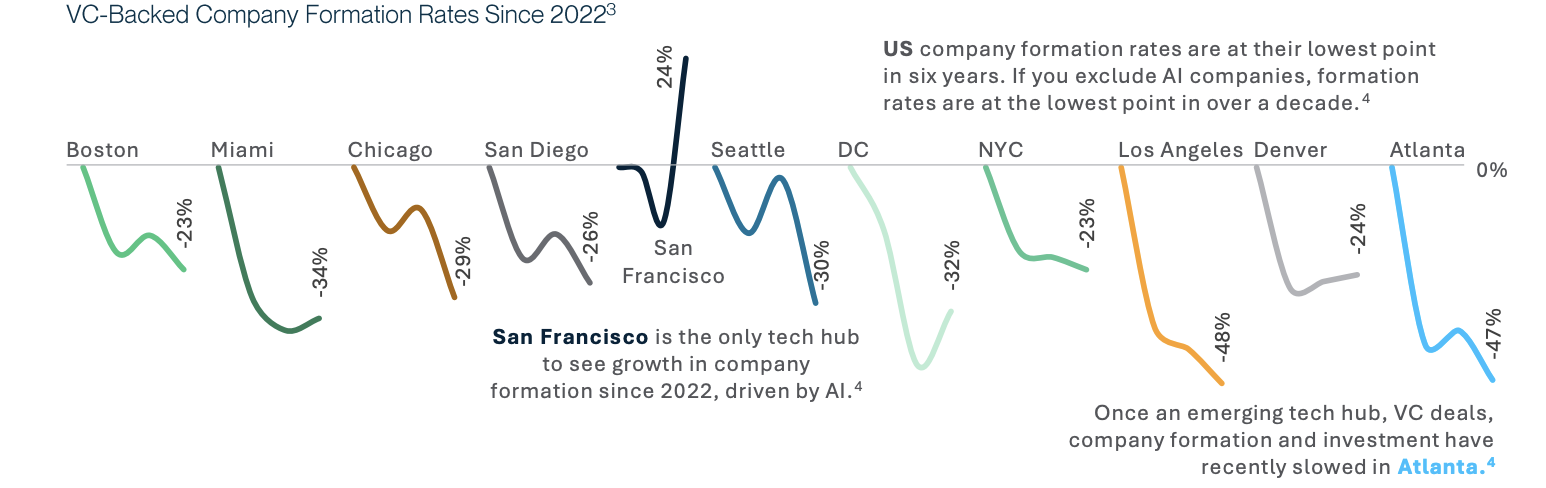
A report recently published by Silicon Valley Bank showed that, since 2022, the rate of VC-backed company formation has plummeted in every major city in America, except for San Francisco…where new company formation has skyrocketed:
Meanwhile, rent in San Francisco is increasing at the highest rate in the US and is on pace to surpass NYC for one- and two-bedroom units.
“In San Francisco, rents are surging, with one-bedrooms climbing 16.1% and two-bedrooms up 19% year-over-year, as a return-to-office push and optimism around AI-driven hiring pull high-income workers back into an already supply-constrained market.”
Taken alone — or even together — these signals don’t necessarily indicate a shift in “how” Silicon Valley is operating as an ecosystem. After all, San Francisco has been a gold rush town since the 1800s. People in tech rushed to the Bay Area during the dotcom boom in the late 90s and then again as the recovery from the 2008 financial crisis accelerated in the early 2010s. But this time is different.
Each time I’ve returned to the Bay over the past 18 months, it’s seemed faster than when I left. And each time I travelled to another city, the slowdown felt more pronounced. The contrast more jarring. It was as if Silicon Valley was accelerating and evolving in near real-time, while other ecosystems remained static.
What’s Going On?
Last year, tech media started publishing articles about Silicon Valley embracing “996”. The implication of these articles was that the acceleration happening in tech could simply and easily be attributed to startup employees working longer hours. But that explanation rang hollow to me.
While the idea of working 996 (9AM to 9PM, 6 days/week) seems shocking to many people, it’s actually nothing new for Silicon Valley. Back when I worked in startups, a 12-hour workday was pretty normal (I actually have a draft blog post on the topic which I have yet to get around to finishing…). I personally think the media reaction has a lot more to do with how many visitors to Startupland™ during the ZIRP era didn’t actually work that hard, but that’s a topic for another day.
From where I sat, there had to be something else going on.
It took a conversation that I had with Charles Hudson last fall — when I was brainstorming for an experiment that would become Game On — to provide the lightbulb moment. We were discussing the fact that founders seemed to be executing faster in San Francisco than they had been before. Charles had observed something similar and had invited several of his portfolio founders from outside of California to visit for “field trips” (short visits to San Francisco during which they would work out of the Precursor Ventures office).
Charles shared with me a story about one such founder, who was working at the Precursor office on a Friday afternoon when he ran into a bug with an API that he was building on top of (the anecdote is paraphrased as follows):
Founder: “I just ran into a bug with X, so I’m blocked.”
Charles: “What are you going to do about it?”
Founder: “I filed a ticket.”
Charles: “And then?”
Founder: “And then what…?”
Charles: “What else did you do?”
At this point, the founder looked dumbfounded.
Charles: “Are you really going to just file a ticket and call it a day?”
Founder: “What else am I supposed to do?”
Charles: “How about I connect you with the CEO?”
A few minutes later, the founder was describing the bug to the company’s CEO. Within an hour, it was fixed.

Snakes and Ladders
I’ve been thinking about that anecdote — any many similar ones that I’ve heard since — and I believe that the best metaphor for what’s going on in Silicon Valley right now is the board game snakes and ladders.
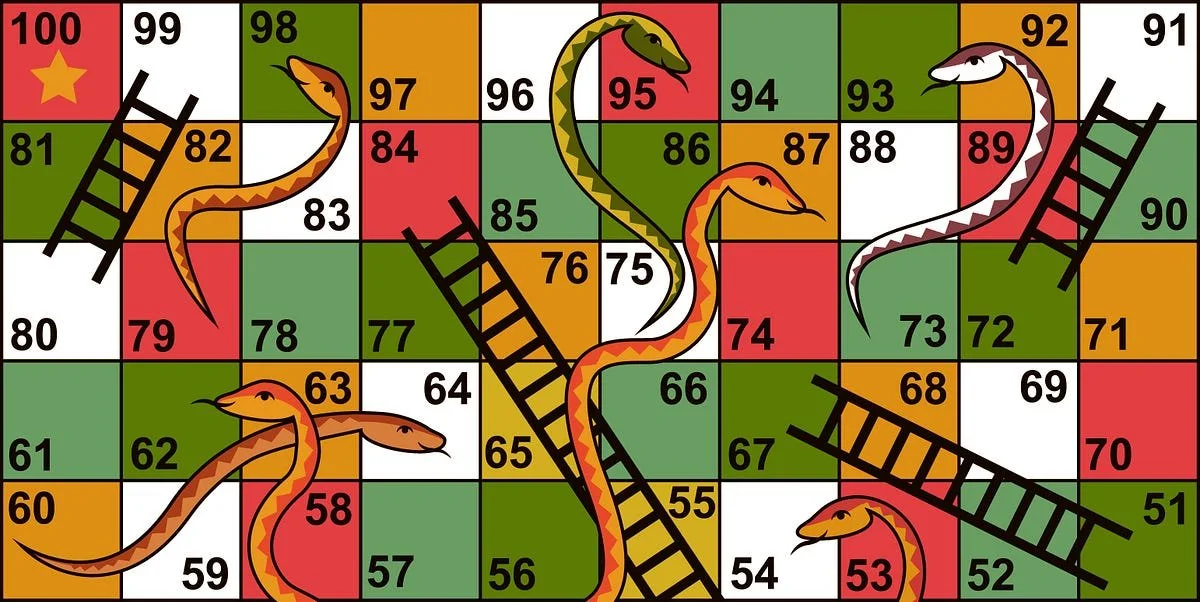
Founders in SF have always benefited from high-value networks, but over the past couple of years they’ve become far more aggressive in how they leverage them. Have a bug? Reach out to the CEO. Want early access to the next release? Get your VC to connect you to the CEO. Trying to get into that invite only party with the who’s who of your sector? Reach out to the party organizer (aka the CEO).
These days, founders up and down Silicon Valley unapologetically search for and leverage “ladders” in order to skip steps. They’ve become far more aggressive at this than I’ve ever seen before — going into social debt to a degree that would have been considered inappropriate (and, frankly, cringe-worthy) only a few years ago. But these days, it’s increasingly perceived as a socially-acceptable form of ambition.
These founders are sprinting and scrambling as fast as they possibly can up each and every ladder they find. Occasionally, they screw up and slide back down a “snake”. But no one in the valley bats an eyelash. There are no negative social implications. Meanwhile, founders everywhere else in the world are dutifully running back and forth along the left-to-right game squares. Some of them are trying to go faster (aka 996), but all of them continue to follow the linear, back-and-forth path.
Have you ever heard of anyone winning a game of snakes and ladders without climbing a ladder? Me neither…
One of the experiments we performed during the “Game On” program last January involved introducing the 35 visiting Canadian founders to some unexpected ladders. On day two of the program, we had Google’s Global Founder Advocate, John Alioto, join us. He sat down in front of our visiting founders with a simple offer,
“Tell me anything you want access to anywhere in Google, and I’ll make it happen.”
One of the founders in the room raised their hand and mentioned that they had been on a waiting list for a pre-release product for 3 months. John smiled, typed a few things into his computer, and several moments later declared that they had access to it. Everyone’s eyes widened.
Over the course of the morning, he repeated similar unlocks for many of the founders in the room. In mere moments, these founders climbed ladders that they had been dutifully marching towards for weeks or months. John unlocked doors that were previously closed to them, with no idea as to when (or if) they might be opened.
That’s a daily occurrence for Silicon Valley’s highest-velocity founders.
The Fog of War
Popping up a level, it’s important to address the topic of information asymmetry in the current startup landscape.
Whether you are a founder, an investor or an ecosystem supporter, it’s essential that you understand that there has been a significant reduction in the information flow emanating from Silicon Valley. The “fog of war” between the Bay Area and the rest of the world has gotten thicker. “Snake and ladders” is but a single example of the many changes that have taken place in how San Francisco startups operate that aren’t yet apparent to the outside world.
Historically, information and innovation flowed fairly reliable out of Silicon Valley. Each time a new idea would arise — whether technical, business process, or otherwise — it would first disperse throughout local Bay Area networks. A month or two later, some number of people would share it with the wider world through blog posts, Twitter threads and videos. Within a quarter or two, the majority of the world’s tech ecosystems were up-to-speed.
That’s not happening anymore.
Technological innovations are still widely and reliably distributed online (you need only look at the speed with which OpenClaw took the world by storm to be convinced of that). But when it comes to business processes, go-to-market strategies, best practices and other innovations, very little information is leaving the Bay Area these days.
There are three reasons for this:
The intensity of AI-driven competition has resulted in many people deprioritizing non-critical content creation
An increasing percentage of the content that does get created is useless, AI-generated slop
Within Silicon Valley, information sharing has overwhelmingly shifted from public forums to private group chats and closed events
When taken together, the result is that founders, investors and ecosystem builders outside of Silicon Valley are increasingly out-of-touch with what’s happening on the ground in San Francisco for no other reason than that no one is telling them.
In the past six months, I’ve seen numerous founding teams from outside of Silicon Valley visit the Bay Area, only to discover that their knowledge — about technology, competition, customer interest, and more — was significantly out of date. Despite having every belief that they were operating at the bleeding edge of their industry, they discovered that they were, in fact, very far behind.
I’m not sure when (or if) the flow of information from Silicon Valley to the outside world will return to it’s previous rate. For now, I can simply offer this: if your goal is to create a globally competitive tech company, you should presume that what you think you know about what’s happening Silicon Valley is significantly outdated. At worst, it’s flat-out wrong.
The solution? Go on a field trip. Get on a plane, spend a few weeks in San Francisco during the summer. And see for yourself.
For founders building outside of Silicon Valley, it’s the new playbook.
Things I Think I Think - Q1 2026
Three months ago, nobody had heard of OpenClaw, OpenAI was valued at a mere $500B, and Anthropic was signing multi-year partnerships with the U.S. Government.
Three months ago, nobody had heard of moltbot clawdbot OpenClaw, OpenAI was valued at a mere $500B, and Anthropic was signing multi-year partnerships with the U.S. Government.
Here’s where we stand ninety days into 2026 in my latest homage to legendary sports columnist Peter King.
Try explaining this one to 2025 Garry
Here are 5 Things I Think I Think - Q1 2026 Edition:
1. The Bifurcation of VC Continues (Continued…)
In my Q4 2025 post, I shared some observations about the ongoing bifurcation of VC. In particular, I discussed some of the changes that were starting to emerge at the Seed round. Over the past three months, those shifts have gone into overdrive.
It’s now very clear that for a certain category of companies (namely, AI-native companies whose revenue tracks usage), the growth trajectory is very different from what has historically been the case in the software world. The extreme compression of time has led to a dramatic acceleration of funding for those companies and a dramatic upswing in round sizes and valuations. And while usage-based revenue won’t last forever, the companies capitalizing on it are running away from the proverbial pack.
Carta recently noted that the top 5% of U.S. Seed rounds in Q4 2025 had an average valuation of $115.5M (compared to a median valuation of $24M). That looks a lot more like a traditional Series A valuation. And if this year’s on-the-ground activity is any indication, I expect the Q1 numbers to absolutely crush that.
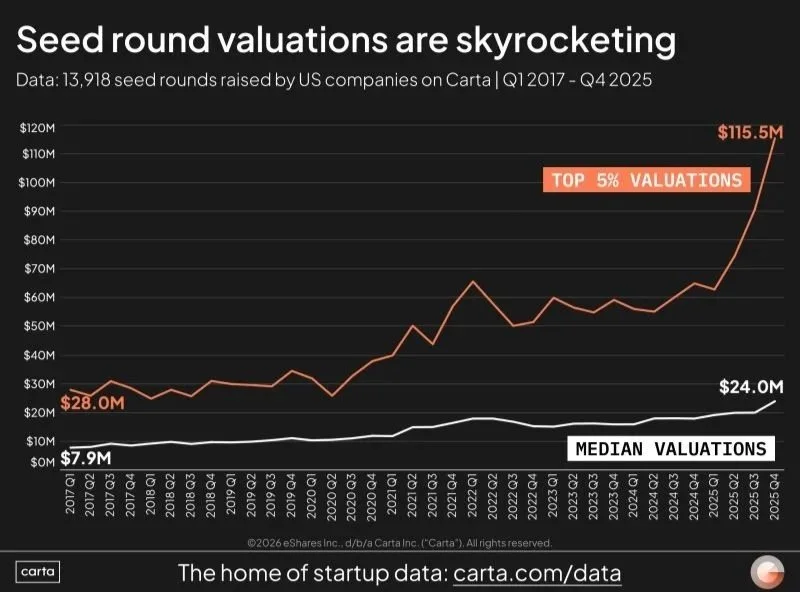
So, if it’s the case that the top segment of Seed companies are splitting off from the rest, are we still talking about a “bifurcation” of VC?
Yes.
Because it’s the megafunds that are swooping in to fund the perceived top Seed companies.
The vast majority of traditional Seed funds (even large ones) can’t afford to invest in these mega rounds. At least…not with traditional fund models. Which is why we’re seeing a ton of adjustment happening amongst Seed VCs. I shared some thoughts on this shift in last week’s post, but it’s worth pointing out that we’re only just starting to see the resulting dominos fall.
I expect that we’ll see a lot of changes when it comes to fund strategies at the Seed by this time next year. In particular, I expect that we’ll see a number of Seed funds adjust their models to look more like Pre-Seed microfunds, with 3 - 5% ownership targets at much higher valuations.
In the meantime, I offer a warning for founders preparing to fundraise: expect to see a Seed crunch for at least the rest of this year.
Much like the Series A crunch we saw last year, this one won’t be due to a lack of capital. It will be because the majority of Seed funds are completely rethinking their investment criteria.
Warning: goal posts moving
In the past few weeks alone, I’ve seen multiple companies that would have easily raised a Seed round a year ago struggle to get first meetings with VCs. Companies with real revenue and prominent logos aren’t even getting a 20-minute intro call.
Plan accordingly.
2. The SF Maker Phase is On Off On
A little over a year ago, I noted that the “maker faire” phase of San Francisco’s AI cycle was over,
“…we’ve moved from the “innovators” phase of this edition of the San Francisco technology lifecycle to the “early adopters” phase. And that’s a good thing.
This isn’t to say that you shouldn’t go to San Francisco in 2025 if you’re a builder — you absolutely should — just don’t expect it to have the same level of serendipity as last year. On the other hand, if you’re a founder a bit further along on your journey who’s looking to meet other high-quality founders focused on building their companies, there’s no better time to come. Just know that you need to be more intentional about your visit and manufacture the outcomes you want.”
I also argued that, “if history’s any indication, it will be another 20 years before it’s back.”
It turns out that history wasn’t helpful in this one. In January, moltbot clawdbot OpenClaw took the tech world by storm. Add to that the latest advancements in Claude Code and it seems like everyone is back to tinkering again.
In reality, I don’t believe that we’re heading back to another full-blown “maker faire” phase of SF’s tech cycle, but there is definitely is mini boom that’s happening right now around agents. Lots of meetups. Lots of activity. Lots of enthusiasm.
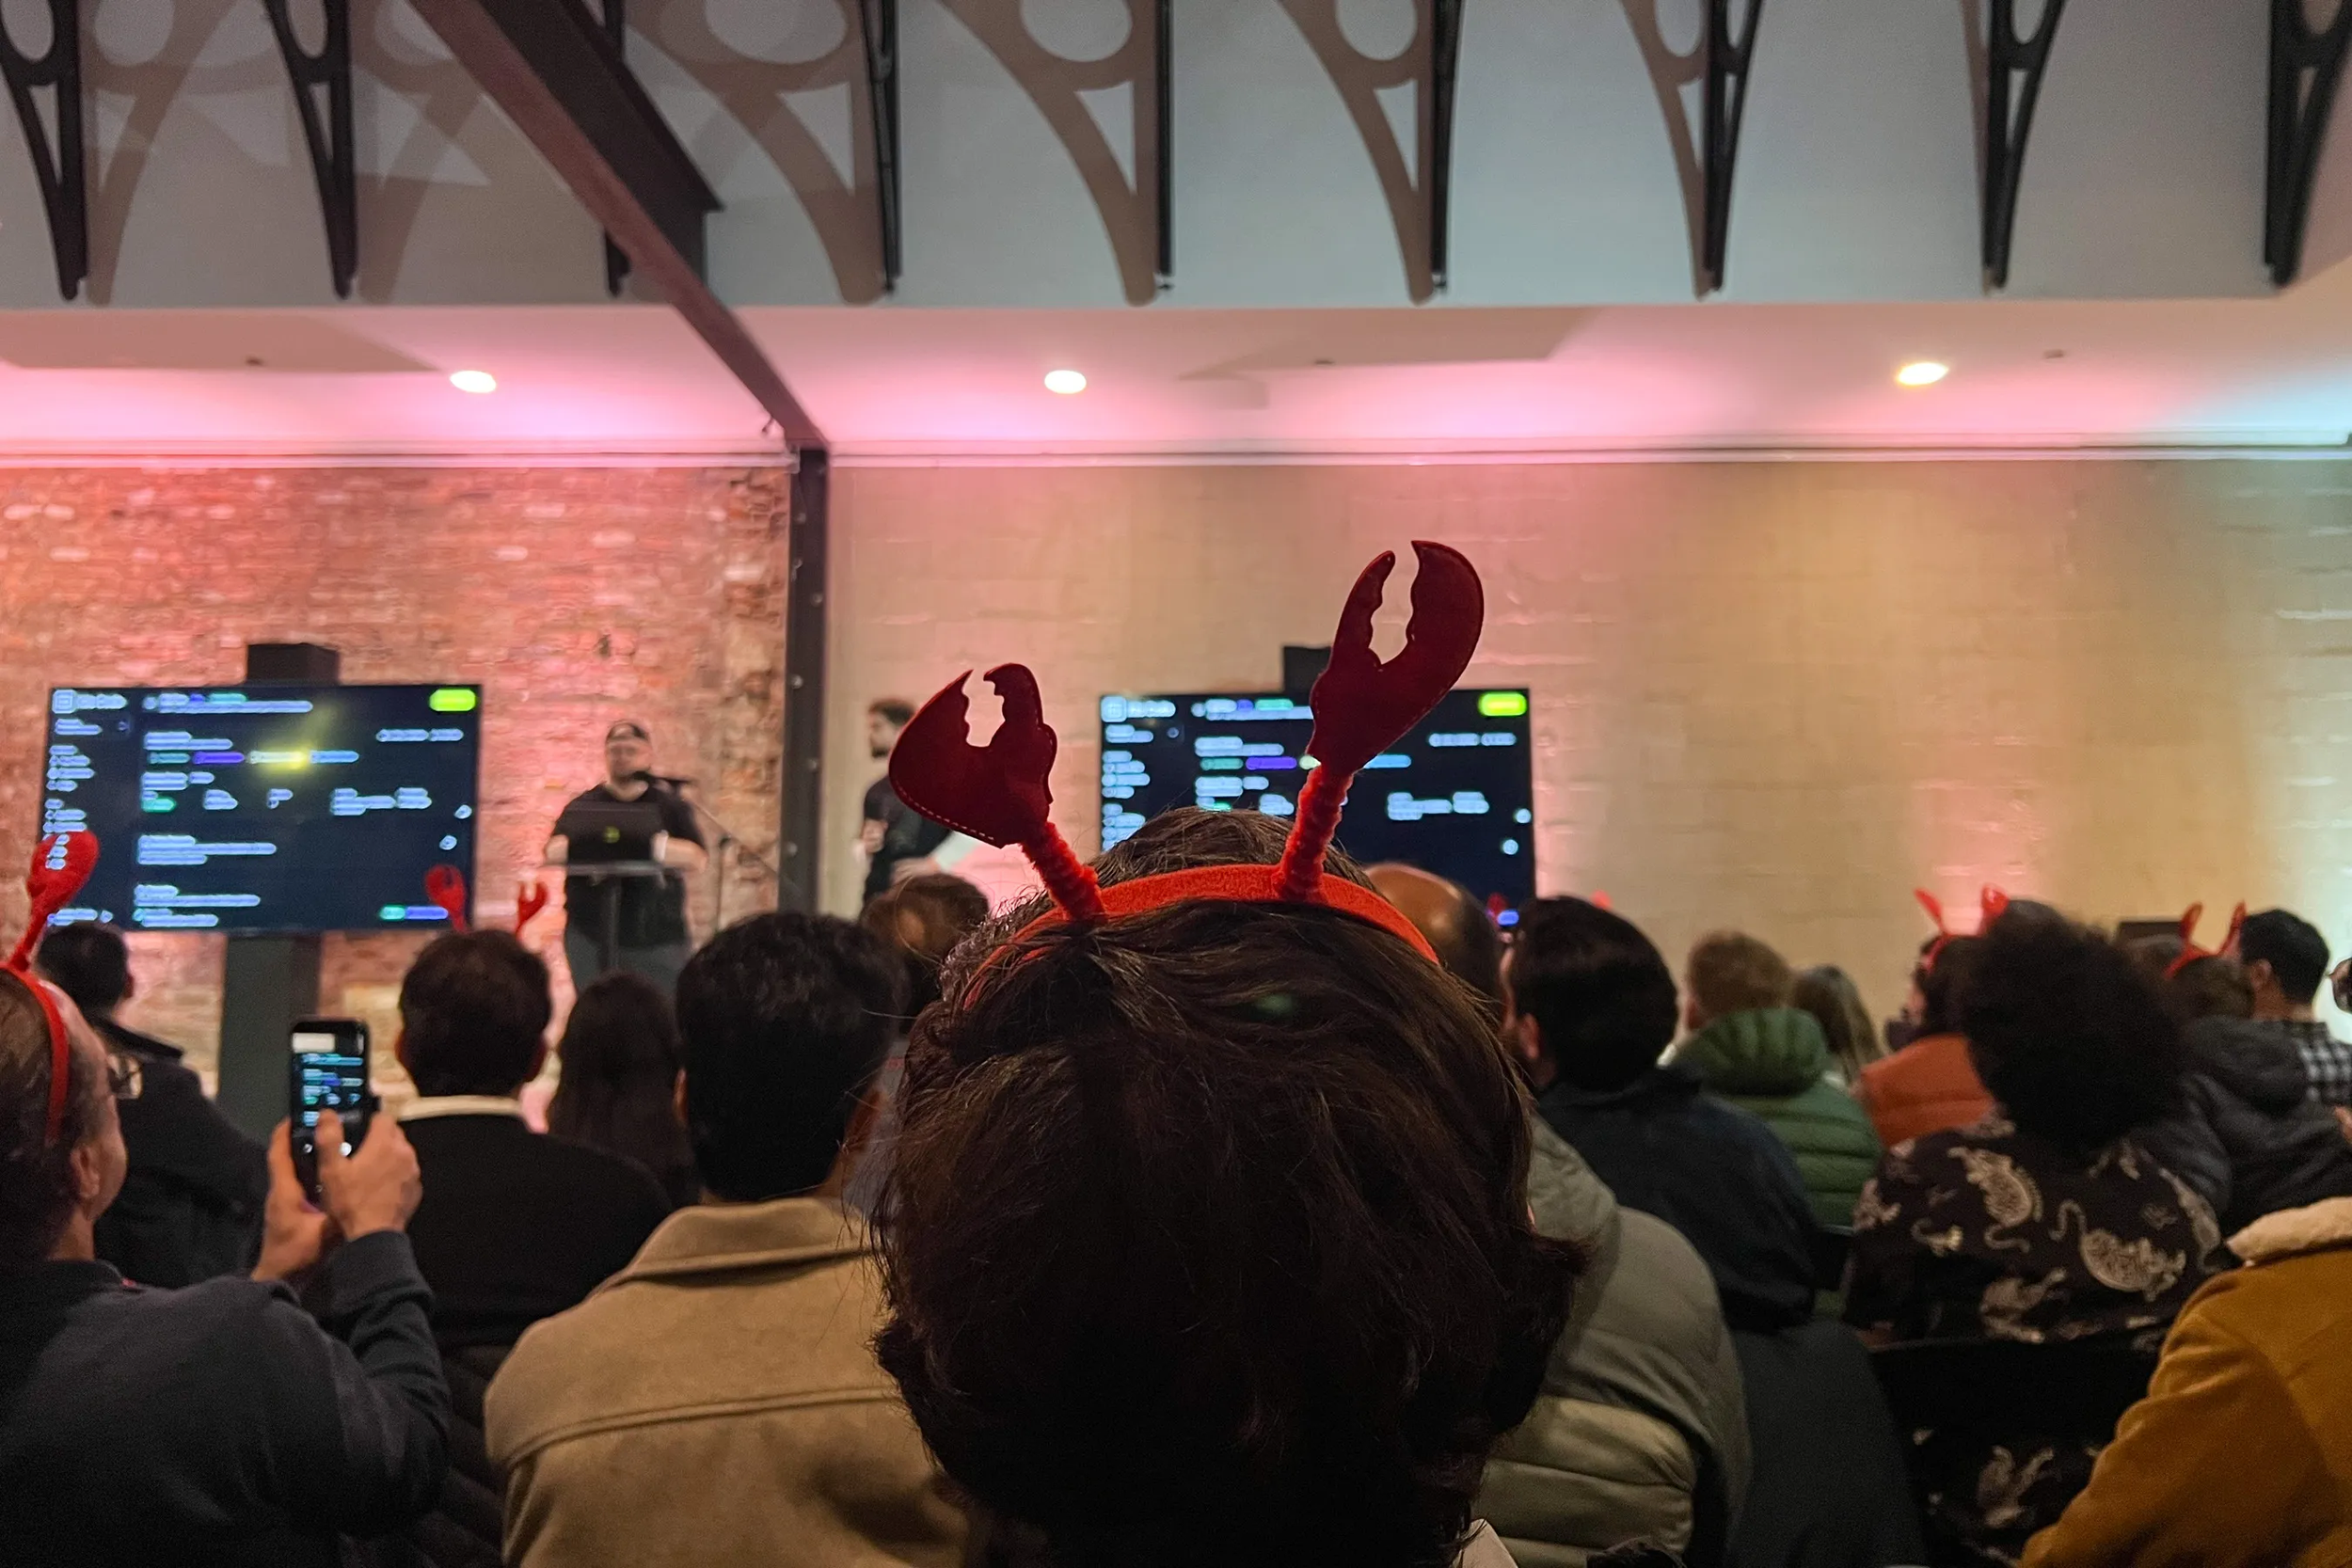
I suspect that this maker revival period will be relatively short-lived, particularly as more (and differently-targeted) agent offerings come to market. But it’s definitely going to be an eventful spring in Silicon Valley.
3. Do You Even Moat, Bro?
Another ongoing debate in the tech world surrounds the evolution of moats.
Historically, technical moats were a big deal for a lot of VCs. But with AI compressing time-to-market, a variety of new ideas have emerged. Some pundits have argued that deep knowledge of a particular industry or specialization will be a moat. Others suggest that trust and brand loyalty will win the day. There’s also the element of “taste”…
Jordi Visser recently wrote an article titled, The Repricing of Time: Equity in the Age of Agents, in which he discussed the impact of AI on equity markets (I highly recommend that you read it). Jordi posits the following:
“For more than a decade, equity markets were built around a simple premise: durable franchises deserved durable multiples. Investors weren’t just buying earnings. They were buying time. Time to compound. Time before meaningful competition arrived…Time was the moat.
…
But something subtle has changed.
AI does not simply disrupt business models.
It compresses time.”
Jordi goes on to propose that as AI continues to improve, the biggest moat will no longer relate to what you are building. It will be dictated by your ability to adapt. In other words, more than ever before, velocity will be the one metric that matters most.
4. YC is Pricing the Market
A year and a half ago, I noted that YC was boxing out. Earlier that year, Techstars had effectively failed. With 500 Startups’ having imploded a few years prior, that left an unprecedented opening for YC to dictate the proverbial terms across the entire accelerator landscape. It started with a move to 4 batches per year and has followed with the firm driving higher and higher average valuations each batch.
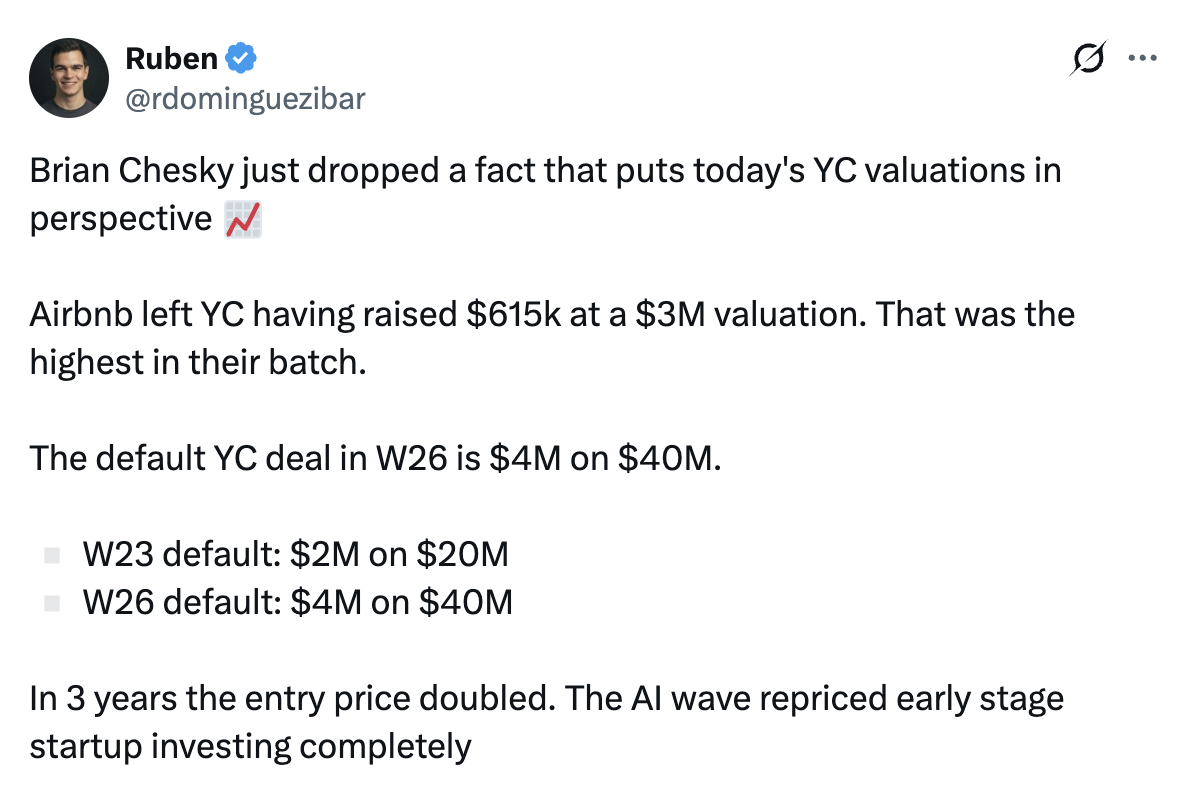
To be clear, the “default” YC deal isn’t actually what all of the companies graduating from the program get. (Moreover, as an index YC batches represent a very particular segment of the early-stage market — one typically characterized by high-pedigree founding teams supplemented by certain early traction signals). But the fact remains that these companies consistently price at the high end of the market across multiple dimensions.
a16z is targeting the same founder demographic with their Speedrun platform. The firm spent Q1 aggressively ramping up their team (I did more than a few reference calls over the past few months). It will be interesting to see where their batch valuations land as that platform settles into its groove and whether or not the well-funded competition puts a dent in YC’s ability to dictate prices.
5. The Delta Between SF / Silicon Valley and the Rest of the World is Exploding
I constantly travel between San Francisco / Silicon Valley and other startup ecosystems around the world (particularly those in Canada and the UK). Over the past year, the rate of change in the Bay Area has accelerated dramatically. Over the past 3 months, it’s gone stratospheric.
And founders / investors / ecosystem builders in the rest of the world — including in most of the US — genuinely have no clue.
I find myself increasingly disoriented as I bounce between ecosystems. I regularly meet founders outside of Northern California who are excited about the projects and products they’re working on, completely oblivious to the fact that companies in Silicon Valley have long-since abandoned those approaches, technologies or markets. At the same time, technologies that have permeated the day-to-day lives of Bay Area residents are still foreign in most of the world.
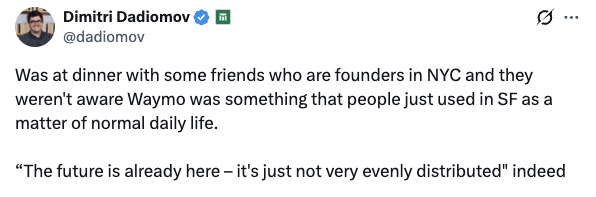
That’s certainly not to suggest that founders / startups / investors in the Bay Area are the preeminent experts on everything to do with technology (Silicon Valley remains a very thick bubble in both positive and negative ways). But it feels to me as though the rate of change occurring as a result of AI is actually decreasing the flow of information from Silicon Valley to the rest of the world.
Things are advancing so quickly that people in the Bay Area are finding less time to share what they’re working on with the world outside.
More than ever, I think it’s essential that founders, investors and ecosystem supporters around the world make a point of traveling early and often to Silicon Valley. To understand what’s going on, to benchmark the velocity at which it’s happening, and to understand what the competitive landscape really looks like.
Things are only going to get faster.
What’s Going on with Seed Rounds?
Another major shift is underway and, this time, it’s throwing off founders, angel investors, and Pre-Seed VCs alike.
As we near the end of the first quarter of 2026, yet another major shift is underway in the funding / fundraising landscape. And this time, it’s throwing off founders, angel investors, and Pre-Seed VCs alike:
Seed VCs are increasingly not acting like Seed VCs.
“Let’s see who this “early-stage VC” really is!”
Rather than dive into a full history of early-stage investing, I’ll anchor this post with the following loose — but by no means dogmatic — definitions of early-stage VCs (at least, as we’ve come to define them over the past decade or so):
Pre-Seed: The first institutional round of capital. Often comes before any revenue or pilots. The investment decision is primarily based on an evaluation of the team, their initial idea, and its market potential.
Seed: The first round of capital where traction plays a factor in the investment decision. Initial traction (revenue, pilots, etc.) provides early evidence that the product solves a real problem in the market and that customers are willing to pay to solve that problem.
Series A: The first round of capital where traction is at the forefront of the investment decision. At this point, there is enough traction to demonstrate that there is a real market for the product and that initial traction wasn’t a “fluke”. The investment decision focuses on how large and how fast the company can scale its early wins.
To frame it another way, the key variable around which the investment thesis is built for each of these stages is:
Pre-Seed: Team
Seed: Market Hypothesis
Series A: Traction
The Market Hypothesis
If you are unfamiliar with the term “market hypothesis”, it’s the statement that underpins a startup’s primary focus and typically takes the following form:
“There is a market X in which problem Y exists and customers are willing to pay for solution Z.”
If this concept seems vaguely familiar, it’s because of its close relationship to product-market fit (PMF). One definition for product-market fit is the point at which a market hypothesis is proven to be true (through the creation of a product/solution that slots into the hypothesis statement):
“There is a market X in which problem Y exists and customers are willing to pay for our solution Z.”
At the Pre-Seed stage, a market hypothesis may or may not be fully formed. Even if it is, investors typically incorporate into their investment decision an expectation that one or more aspects of it may turn out to be incorrect (and, thus, focus primarily on the team and their ability to iterate in search of product-market fit).
At the Seed stage, the market hypothesis is (historically) at the center of the investment decision. While it may not be in its final form, VCs evaluate potential investments through the lens of the market hypothesis that founders provide. Do they believe that the market is big enough? Do they believe that the startup has the right team to go after that market? To what degree does the early traction support the notion that their solution (a) solves the problem the founders are describing, and (b) demonstrates that customers are willing to pay for that particular solution?
(This is why it’s so important that founders spend time refining their positioning and market hypothesis before fundraising!).
What Has Changed?
While Seed-stage investments have been anchored around the market hypothesis for more than a decade, in the past few months things have shifted considerably. And the reason starts and ends with “AI”.
AI is changing so many things at such a high velocity that many Seed VCs are struggling with how to evaluate startups when they no longer have conviction that the market hypothesis will hold over their 7-10 year investment horizon. Consider the following:
“There is a market X…” — will that market still exist in 10 years?
“…in which problem Y exists…” — will this still be a problem in 10 years?
“…and customers are willing to pay for our solution Z” — will they still be willing to pay for this in 10 years?
Live footage of a Seed VC
While the above comments might seem facetious, it’s important to understand that these are real questions within the context of the role that Seed VCs have historically played. For the past 10+ years, Seed VCs have been primarily responsible for funding companies from the point at which they had a clear market hypothesis and early signals supporting that hypothesis through to product-market fit.
What happens when Seed VCs can no longer rely on those market hypotheses being stable?
How Seed VCs are Reacting
According to Crunchbase, the number of Seed deals in North America has fallen for 3 consecutive quarters — despite the fact that total deal volume by dollars remaining relatively strong. That means capital is concentrating at the Seed stage.
In other words, fewer deals are happening with larger average deal sizes.
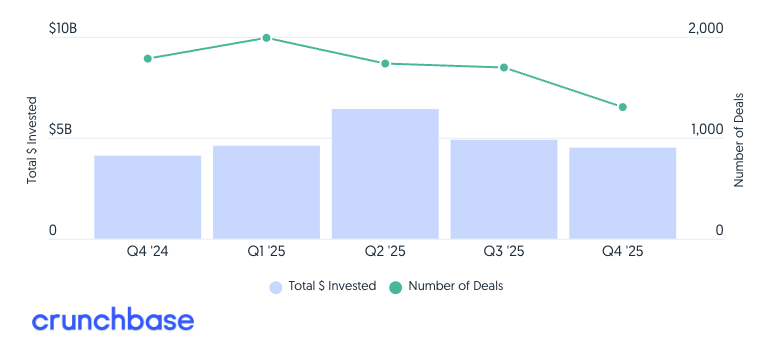
North American Seed Investment Through Q4 2025
Beneath the surface, Seed VCs are broadly reacting in one of three ways:
1. Reducing the Number of Deals
Some Seed VCs have reacted by doing fewer deals.
Over the past few months, I’ve spoken with a number of institutional LPs concerned by the fact that some of the funds they’ve invested in aren’t actively deploying capital. One early justification was the need to “slow things down” while they adjusted their investment theses to an increasingly bifurcated VC landscape. But at this point, it appears that some Seed VCs remain inactive / less active because they are simply unsure of what to do.
2. Chasing Repeat / Pedigreed Founders
Many Seed VCs are reacting by investing more in repeat founders and/or founding teams with a strong “pedigree” (graduated from top schools, worked at prominent companies, YC graduates, etc.).
Pitchbook showed a significant increase in the early-stage deal sizes commanded by repeat founders in recent years (in the chart below, “serial” founders are repeat founders who had an exit, while “unproven” founders are repeat founders whose prior companies failed).
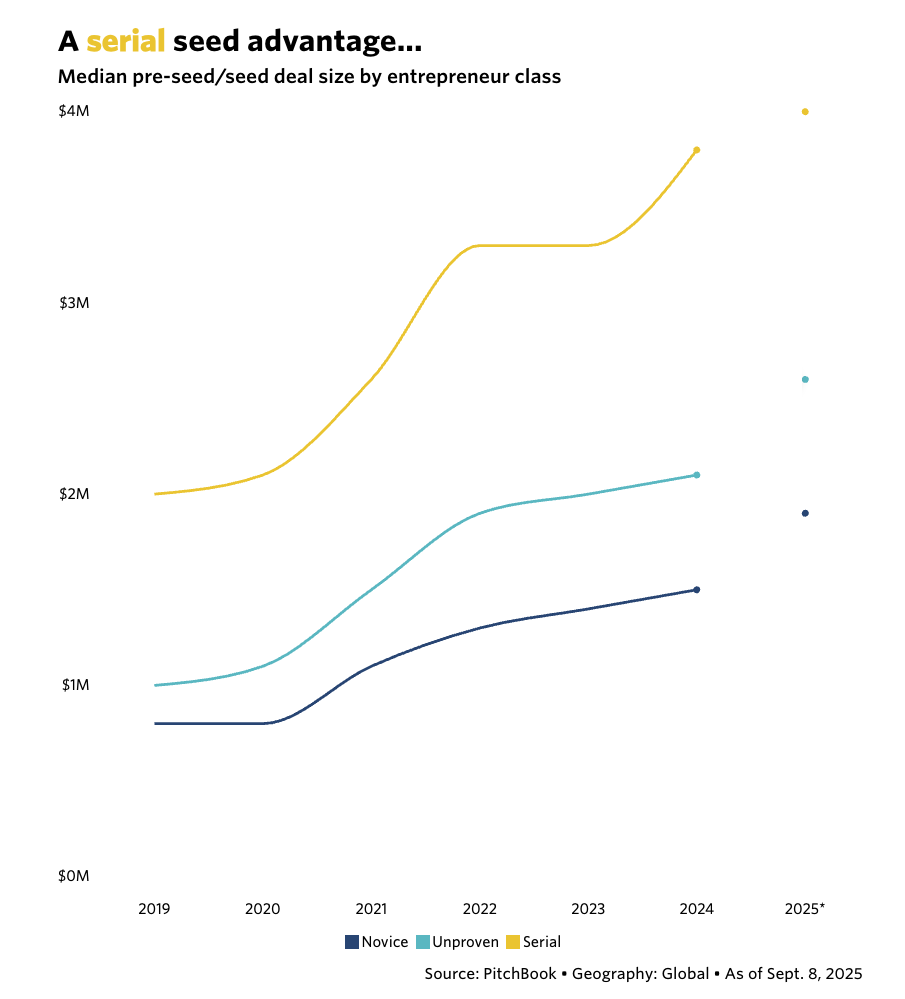
In the absence of conviction about the underlying market hypothesis, these investors are betting on the prior experience of the team.
“They figured it out before, so (hopefully) they can figure it out again.”
3. Focusing on Early Traction
The third trend has been to chase signs of early traction.
Early, disproportionate traction has always been something of a cheat code for startups. At the Pre-Seed stage, we often see deals happen quickly when a team comes to the table with unusually strong traction (revenue, users, GitHub stars, etc.), even if they don’t have a fully-formed market hypothesis.
The bet here involves a similar benefit-of-the-doubt as the one given to repeat founders:
“They figured out how to get to X traction, so (hopefully) they can leverage that to build a real product / get to product-market fit.”
Wait a Minute…
Ok, so to summarize what we’re currently seeing in the early-stage fundraising market:
Pre-Seed VCs generally discount the market hypothesis and focus primarily on the team and their ability to iterate in search of product-market fit
Seed VCs are increasingly discounting the market hypothesis and…focusing primarily on the team and their ability to iterate in search of product-market fit???
That’s right. Seed VCs are increasingly acting like Pre-Seed VCs when it comes to their investment decisions.
There’s a lot to unpack when it comes to the potential long-term implications of this shift. It’s especially fascinating within the context of the ongoing bifurcation of VC (and explains why some Seed VCs continue to sit on the sidelines — they simply don’t know how to invest based solely/primarily on the potential of a team). For now founders, angel investors and Pre-Seed VCs need to understand the following about what’s happening at the Seed stage:
Outside of markets that are unlikely to be disrupted by AI, the rubric with which many Seed VCs are evaluating potential investments has changed. Specifically,
The focus on traction has increased — not because it shows more evidence in support of the market hypothesis, but because it shows more evidence in support of the team’s ability to execute.
The focus on a team’s track record has increased.
The impact of whether or not a company is building in a “hot space” has increased.
While Seed VCs are increasingly acting like Pre-Seed VCs, it’s not exactly the same as raising another Pre-Seed round.
For starters, Seed VCs have a lot more data to analyze about your team and your trajectory (especially when it comes to velocity, the one metric that matters most).
It’s also important to understand that Seed VCs have promised their LPs a shorter path to returns than Pre-Seed VCs. In other words, they still need to get an exit in the same amount of time that they did before. This means that you have to be able to demonstrate meaningful progress towards something valuable (it’s not a do-over if you’re still wandering around in the woods in search of PMF).
Finally, this dynamic is most prominent with generalist Seed VCs. Specialized Seed VCs — particularly those in deep tech — are relatively unchanged in their behavior.
If you’re preparing to raise a Seed round, keep the following in mind as you fine-tune your pitch: in addition to analyzing the usual details on problem, solution, traction, etc., many Seed VCs are now asking themselves the following question as part of their investment process:
Can this team win (generate a return) even if one or more of their core assumptions is disrupted by AI? (In other words, can they still win if their market hypothesis gets disrupted?)
Unfortunately, it’s not at all clear yet how Seed VCs are testing for this. As a result, I suspect that we’re going to see a significant “crunch” at the Seed stage in the next few quarters. Startups that historically could raise funding based on a clear market hypothesis and reasonable early traction will struggle, especially if they can’t convince investors that the market hypothesis is viable over a long-term horizon.
Most Seed VCs don’t know what the future is going to look like, so they’re increasingly betting on founders who they believe can figure-it-out.
AI Price Drops Are Coming
Right now, AI companies around the world are capturing unprecedented revenue. But it won’t last forever.
My first co-op job back in the 90s was for a regional Canadian telecom company called BC Tel. It was the early days of the internet, when dial-up modems were the norm (you were envied if you had one of the new 56K ones). The most recognized sound in the world was this.
RIP BC Tel
BC Tel was preparing to launch its first deployments of a new technology called “digital subscriber lines” — dedicated phone lines that businesses could purchase in addition to their standard voice line in order to have an always-on internet connection (you’ll recognize the technology by its acronym, “DSL”). Like most telecoms that were rolling out DSL, BC Tel planned to initially sell their product using usage-based pricing.
Over the course of the summer, I wrote metering software that would track exactly how many bytes were transferred up and down a customer’s DSL connection each month. Those metrics were then used to generate their monthly invoice.
A “vintage” Cisco 678 DSL router
Midway through the summer, the first DSL deployments were rolled out to great fanfare. While some early adopters were eager to brag about their state-of-the-art internet connections, it wasn’t long before the complaints started coming in. Businesses that were used to paying $100/month for a dial-up line were suddenly getting invoices in the thousands (or tens of thousands) of dollars. The telcos argued that usage-based pricing was the only approach that made sense (since the increased traffic would result in increased costs on their side).
Customers weren’t buying it. And the competition took notice.
The cable companies weren’t far behind. And when they eventually rolled out their competing broadband offerings, they did so with fixed, monthly pricing. Within a couple of years, usage-based internet pricing was a distant memory, along with the short-lived revenue burst that came with it.
From 1999 - 2003, BC Tel/Telus’ DSL revenue skyrocketed as a result of usage-based pricing. Revenue flattened in 2003 (despite ongoing subscriber growth) as it was replaced with fixed pricing.
What Does This Have To Do With AI?
As the saying goes, “history doesn’t repeat itself, but it often rhymes.”
Right now, AI companies around the world are capturing unprecedented revenue, driven primarily by usage-based pricing. Early adopters are eager to take advantage of the incredible productivity gains offered by this new technology, but are also running head-first into the sticker shock of pricing. Many prosumers are now spending thousands of dollars each month on AI tools, while some companies are already well into the millions.
While investors and tech leaders loudly proclaim that this type of pricing “is the future”, the reality is it won’t last forever.
Why Usage-Based Pricing Never Lasts
In markets where customers have multiple competitors and/or alternative ways to fill a need, pricing always trends towards “value-based” pricing. Value-based pricing is where a customer is willing to pay an amount of money for a product or service based on its perceived value to them.
For some products and services, value-based pricing is, in fact, aligned with usage. For example, we are used to paying for travel-related products (fuel) and services (taxis, Ubers, etc.) based on how far we travel. Utilities, like water and electricity also employ usage-based pricing.
But there are many products and services for which value-based pricing is independent of usage. You’re unlikely to want to pay a fee every time you sit on your sofa or open and close your window.
For usage-based pricing to persist over time, two things have to be true:
The value that a customer perceives in the product/service must somehow derive from it’s usage (more usage → more value)
The customer must be able to reasonably predict and/or control usage
The second point is key for businesses that leverage AI. At the end of the day, a business that utilizes a product/service with usage-based pricing must ensure that they’re still able to generate a profit themselves, even if the product/service that they ultimately sell is fixed-price.
This is a crucial point, considering that the vast majority of end products are (and will remain) fixed-price.
To illustrate my point, as a consumer you are unlikely to pay more for one coffee mug over another because one was “designed with AI”. Nor are you likely to pay more for a book that was researched with AI, a movie that was generated with AI or ribs that were smoked using a recipe perfected with AI.
Why AI Adoption is Different (For Now)
What makes AI adoption different from the introduction of DSL 25+ years ago is that the latter didn’t come with immediate productivity gains. Sure, a DSL line was faster and more reliable than dial-up, but software wasn’t yet at the point that better internet access automatically translated into significantly more revenue or lower costs.
As a result, early adopters revolted at the high costs of DSL and threatened to go back to dial-up. They called the telecoms’ bluff…and it worked.
But AI is different. There are legitimate and immediate productivity gains that come from leveraging it. As a result, companies are willing to pay outrageous rates for AI because of the increased productivity that they’re realizing. But that willingness isn’t infinite.
The simple narrative being pushed by AI companies and their investors is that AI is making software developers more productive than they’ve ever been. So much so that companies should be willing to spend infinite amounts of money on AI. The more nuanced reality is that, in most cases, those productivity gains aren’t resulting in equivalent profit gains. In fact, in many cases the incremental cost of AI is eliminating (or, at least, significantly reducing) the profit margins of the companies leveraging it.
Put differently, what we’re seeing is not a straight-forward case of “developers are more productive so we need fewer developers”. Beneath the surface is a clear current of, “we’re spending so much on AI that we can’t afford to keep all of our developers.”
That dynamic is what’s driving the massive VC rounds commanded by today’s fastest-growing startups. It’s also the real reason behind many of the layoffs being announced by companies whose revenue growth has stalled.
Consider this week’s 10% layoff by Atlassian. Buried within the company’s announcement was the following justification,
“We are doing this to self-fund further investment in AI…”
In other words, “we need to cut staff because we can’t afford to pay our increasing AI bills” (P.S. if we can’t figure out how to effectively leverage AI, we’ll probably die).
In the not-too-distant future, we will reach a breaking point in terms of the ability and willingness of businesses and consumers to pay ever-growing AI bills. (I suspect that we have a few more quarters before that happens, but it will happen.)
And therein lies the opportunity for astute startup founders.
The Opportunity in Fixed-Priced AI
For many customers (both individuals and businesses), price certainty is more important than the price itself.
As a case study, through the 1990s and into the early 2000s, most personal computers were custom-built. Anyone could order the components needed to build a computer, buy an OEM copy of an operating system (Windows or one of many Linux distributions) and get up and running. The coolest retailer on the planet in those days was Fry’s.
Over time, custom computer shops popped up filled with people who assembled and sold “no-name-brand” computers to consumers and businesses. Eventually, global brands like Compaq, HP, Gateway and Dell took over.
To computer nerds like myself, it seemed absolutely ludicrous that someone would pay $4,000 (in 1990s money!) to buy a PC that had half the performance of one that I could custom-build in a day for less than $2,000. But many did. And their market share kept growing for one simple reason: their customers wanted certainty. Certainty in price. And certainty that their computer would work.
We’re seeing that same dynamic play out today in AI.
Amidst the many threads proclaiming that if you aren’t rolling your own OpenClaw server, you’re falling behind, is the reality of how most of the world works. Ambitious individuals and businesses around the world will absolutely leverage AI, but the vast majority have neither the time nor the inclination to do it from scratch. And they won’t have to.
Because someone will do it for them.
Moreover, they’ll do it for them at a fixed price (even if that price seems exorbitant to the many hackers deep-in-the-weeds of AI).
We’re already seeing early examples of this, including:
Vertical AI offerings that provide specialized AI capabilities at a fixed price
AI search capabilities that are now bundled with CRMs, note-taking software and other databases
Consultants that will spin up an OpenClaw server on a Mac Mini for you for a fee (much to the chagrin of open source hackers)
If you’re a founder looking for opportunity in AI, don’t just look at the technology. Pay attention to price. There are an incredible number of markets where customers will buy AI-based offerings today if they (a) solve a real problem they have right now, and (b) do so at a fixed price (even if that price seems ludicrous).
None of the hyperlinks on Claude’s pricing page provide any real definition as to what usage is actually based on — which, for most people and businesses, is a problem
If you can create an AI-based offering that solves a real problem at a fixed price, while ensuring that you have a healthy operating margin, you’re likely in a good position to sell to the 99% of consumers and businesses who aren’t glued to Twitter/X 24/7.
Not only will you start focusing on margin (in terms of controlling your own use of AI whilst delivering your product/service) long before most other AI companies think about it, you’ll have a head start on building brand loyalty while others obsess over, “but what if X builds it?”
Because at the end of the day, consumers and businesses still just want a solution to their problem.
Stop, Collaborate and Listen
There are moments in time when it’s important as a founder to stop and pay attention to what’s happening around you. This is one of those moments.
Last week, I urged founders to ignore distractions.
“In an age of distractions, the winners will be the ones who stay focused.”
But there is a counter point to that. For there are moments in time when it’s important to stop and pay attention to what’s happening around you.
I recently caught up with an absolutely dialed-in founder whom I’ve known for many years. He’s S-tier when it comes to ignoring the noise and staying focused on whatever he’s working on (these days, it’s an algorithmic trading platform that’s crushing the intersection of DeFi and traditional finance).
When I asked him how he’d started off the year, he had this to say,
“When my team came back from the holidays, we put everything on pause. Literally everything.
We put all of our algorithms on autopilot and spent a week trying the latest versions of every tool, program and project we could find.
We tinkered as a team for a full week. My mind was completely blown by what we had built by the end.”
Coming from this particular founder — whose teams are known to push the boundaries of whatever technologies they’re working with — a statement like that made me sit up in my seat.
Not just because of what he said, but because he wasn’t the first person to have shared something similar with me over the past few weeks.
At this point, I’m old enough to have seen a lot of technology inflection points. And I have a strong suspicion that we’ll look back at January 2026 as being one of those.
From my vantage point, there are three important things that have emerged in the past few weeks:
1. AI Can Finally Write Good Code
Most developers at this point have become accustomed to using some form of AI while writing code. But for all the hype around vibe coding, anything remotely complex still required humans to roll up their sleeves and wade through muck. Remo Jansen recently described it like this,
“For over two years, I have been using GitHub Copilot extensively with multiple models, coding agents, and custom agents, and for the most part it has been hit and miss.
I usually ask GitHub Copilot to implement a feature or fix a bug using the chat or coding agent, and a lot of times it would go very wrong. I have developed the habit of staging changes before each prompt, code reviewing changes for each prompt as I go along, and rolling back via git when I'm not happy with the solution. Working like this for a while means that I have been able to develop a sense of what kinds of things will work and how to break problems into steps that make it more likely that the AI agent will do what I expect.”
In late-November, Anthropic released it’s newest model, Claude Opus 4.5. At the time, the release didn’t jump out as particularly significant. But that was probably because it came after U.S. Thanksgiving — which meant most developers were focused on wrapping things up for the year as opposed to testing new models. As the year came to a close and we entered 2026, posts like these started to emerge:
I’m generally skeptical of hyperbole and presume most extreme reactions to new technologies are exaggerated, but then I started hearing similar sentiments from people I know and trust. Friends who spent time over the holidays to kick the tires on Opus 4.5 all had similar reactions:
“I built something I’ve wanted to do for awhile over the weekend. I’ve tried (and failed) multiple times to get it done with earlier models.”
“It’s the first time I didn’t have to spend hours reviewing and fixing the code.”
“This one’s different.”
2. The First Agent “Kit”
Almost every major technology shift includes a particular point at which the New Thing™ is made available to highly technical early adopters in a way that is (almost) turn key.
For the personal computer, it was the introduction of the Altair 8800 in 1974. The Altair 8800 was the first commercially successful microcomputer kit. You had to be incredibly technical to assemble it (and it was easy to make mistakes), but it provided the launchpad for the personal computer revolution that came after. (In March 1975, the Homebrew Computer Club held its first meeting in Menlo Park, which Steve Wozniak credits as the inspiration for the Apple I.)
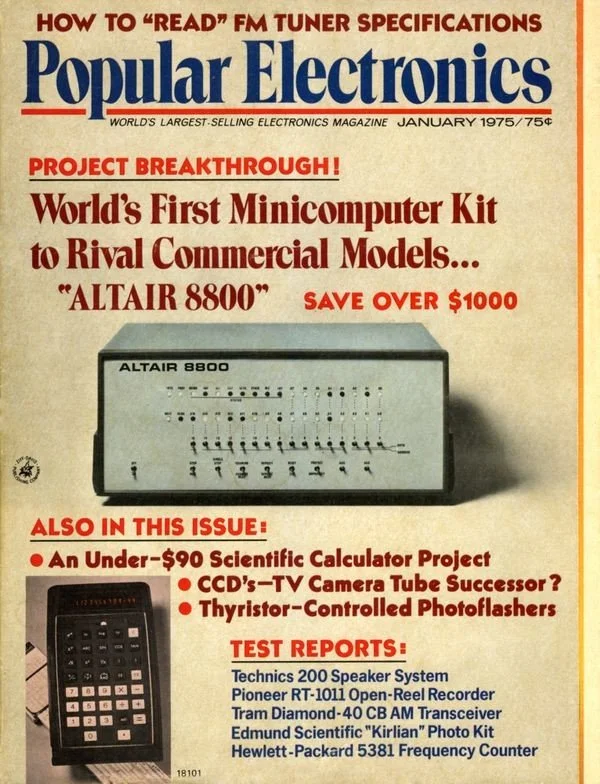
Over the past few weeks, the internet has been awash with posts about Clawdbot Moltbot OpenClaw. On the one hand, there isn’t anything particularly mind-blowing about OpenClaw’s technology. After all, we’ve had agents for some time now. But if you think about it within the context of technology history, it’s an extremely significant product.
OpenClaw is the first agent “kit”.
Just like the Altair 8800, OpenClaw is accessible to only highly technical early adopters (at least, for now), but those hobbyists, hackers and tinkers are swarming to it.
And while there’s an incredible amount of noise and nonsense taking place around this (*cough cough* moltbook), it’s only a matter of time before we see some of these projects turn into products.
3. Open World Games from a Prompt
On the last day of the month, Google announced “Project Genie”, an AI tool capable of creating playable open-worlds from a prompt.
And gaming stocks around the world immediately plummeted.
On the one hand, this might seem like a bit of an overreaction. After all, we’re a ways away from having a prompt result in a brand new end-to-end GTA game (many of my friends in the gaming industry confidently responded as much).
On the other hand, the economics of AAA video games has been upside down for many years. Costs have skyrocketed (the budget for GTA 6 is predicted to be somewhere between $1 and $2 Billion), but financial results remain highly unpredictable.
What makes the stock market response to the release of Project Genie directionally reasonable (at least, in my opinion) is that it represents an expectation that AI will have a similar impact on gaming that it already is having on general software. If we accept that a small team of highly specialized founders can create a billion-dollar software company using AI, then it’s perfectly reasonable to predict that a small team of experienced game developers will create a AAA video game using AI.
While I remain steadfast in my believe that the founders who focus will win, this very much feels like a moment-in-time when it’s important for founders to take stock of what’s going on around them.
That doesn’t mean diving down the rabbit hole of agent social networks, but it does mean checking out the latest tools. And it’s always better to do that with friends.
I’m setting aside time in the next few weeks to stop, collaborate and listen. I suggest you do too.
When Distractions are Everywhere, Focus Wins
The rate of advancements resulting from AI is nothing short of astonishing. But for founders, it can be a major distraction.
We live in an age of distractions.
Geopolitical distractions. Social media distractions. Prediction markets and crypto degens and brainrots and, and, and…
Remember that time a VC’s streamlining measure caused an entire country’s tech sector to screech to a halt?
Oh yeah…and there’s that whole AI thing:
“Have you tried the latest Claude Code?”
“My Mac Mini arrives tomorrow, I can’t wait to get Clawdbot going”
“It’s not called Clawdbot anymore, it’s Moltbot!”
The rate of advancements that are coming at us as a result of AI is nothing short of astonishing. But for founders, it can be a major distraction.
I remember sitting at YC’s W2025 demo day last March when Garry Tan stood in front of the crowd and declared that 25% of the companies in the batch had 95% of their code generated by LLMs. During the course of the day, company after company went on stage with a pitch that included a line like this:
“We wrote our first line of code 3 weeks ago, and…”
Almost everyone in the audience was enamored by how much progress these companies had made in such a short amount of time. But my mind went elsewhere. As someone who spent years working within accelerators, I knew that underneath every such statement was another one:
“We just pivoted 3 weeks ago…”
And that’s what I heard again and again over the course of the day,
“We pivoted 3 weeks ago, and…”
“We pivoted last month, and…”
“We pivoted last week, and…”
Despite meeting numerous incredible founders and amazing companies that day, I left the Palace of Fine Arts with a singular thought stuck in my head: AI is going to be a super power for some founders and will absolutely undermine the focus of many more.

Since then, I’ve seen the results time and time again:
Pre-revenue companies pivoting left, right, and centre around whatever excites them.
Companies who change what they’re doing after not finding an excited customer after…3 tries.
Too many founding teams throwing the baby out with the bathwater time and time again.
For every team I meet that found a new opportunity as a result of AI, there are 10 more who couldn’t stay focused enough to push through the natural challenges of getting to product-market fit.
On the one hand, I get it. New technologies are exciting! Most of us got into this because we really like to build things. But the easier it is to just “start over”, the harder it is to persevere.
These days, my timeline is filled with posts from founders who built X or automated Y after chugging red bull all night. And that’s cool! But does it solve your customer’s pain point?
You know…the one you founded the company to solve?
Unless you’re building dev tools, those customers are probably going to have the same problem on Monday that they did on Friday. The latest AI model or open source agent didn’t change that.
By all means try new things. Spend time to test the new models and try the new toys. But for the love of god constrain the amount of time you spend doing that. If you started a company to solve a pain point that you’re passionate about, keep your eye on the prize (provided, of course, that you continue to believe that pain point matters).
And if you find yourself spending more time on the shiny new thing than you are on solving your customer’s pain points, think about that too.
In an age of distractions, the winners will be the ones who stay focused.
Now, where’s my Mac Mini…
Things I Think I Think - Q4 2025
Now that we’ve all made it through our backlogged New Years inboxes, let’s reflect on Q4 and kick off 2026 with my latest homage to legendary sports columnist Peter King
It’s hard to believe how much transpired in the past year. From new administrations to the blistering pace of innovation, 2025 was one for the books.
Now that we’ve made it through our backlogged inboxes, let’s reflect on Q4 and kick off the new year with my latest homage to legendary sports columnist Peter King.
Here are 5 Things I Think I Think - Q4 2025 Edition:
1. The Bifurcation of VC Continues
At this point of the movie, the idea that venture capital has split into two broad categories (multi-billion dollar megafunds and nimble, specialized funds) is no longer up for debate. What’s been fascinating to watch is the behavior of the many funds caught in the middle. These funds are too small to compete on price, too big to embrace the opportunities presented by AI-native companies going after niche markets (read this post on why market matters most to VCs to understand why), and, more often than not, incapable of pivoting to an industry or technological speciality due to the backgrounds of the partners.
Over the past few months, I’ve spoken with multiple institutional LPs who are frustrated at a lack of deployment by some of the VCs they’ve invested in. Unlike the immediate aftermath of the ZIRP crash — when VCs slowing deployment was seen by LPs as a feature, not a bug — the firms caught-in-the-middle have slowed their pace of investment due to an entirely internal reason: they can’t figure out how to adjust their investment thesis to this new reality.
The noncommittal investment committee
The fastest-growing companies are now leap-frogging one or more fundraising rounds (most commonly, the Seed round). That leaves $100M - $250M funds that anchored around Seed — particularly generalist funds — having to reinvent themselves. Do they invest larger amounts of money in fewer companies? Try going downstream to Series A? Or upstream to Pre-Seed?
This dynamic is most noticeable outside of the Bay Area, especially in ecosystems where multistage funds are increasing their presence.
For founders, it’s harder than ever to make sense of local investor behavior. If you plan to fundraise outside of the Bay Area, I recommend adding the following question to every initial investor meeting:
“How many investments did you make last quarter?”
(With followup questions, “what stage were the investments?”, “how much did your firm invest in those companies?” and “were you the lead investor?”)
Don’t be surprised if the answers don’t match what the VC has on their website.
2. SF is Over
It seems like only yesterday that I was trumpeting the return of San Francisco:
Q3 2024: “SF’s slow recovery is accelerating”
Q4 2024: “…we’ve moved from the “innovators” phase of this edition of the San Francisco technology lifecycle to the “early adopters” phase. And that’s a good thing.”
Q1 2025: “San Francisco is still the place to be”
Q2 2025: (I was really excited by Toronto Tech Week and forgot to fanboy San Francisco)
Q3 2025: “…the difference between what’s happening in Silicon Valley right now and what we’re seeing in the rest of the world couldn’t be more stark.”
But I guess it’s all over now…

So what’s happening?
A year ago, I noted that the “maker faire” phase of San Francisco’s AI cycle was over,
“…we’ve moved from the “innovators” phase of this edition of the San Francisco technology lifecycle to the “early adopters” phase. And that’s a good thing.
This isn’t to say that you shouldn’t go to San Francisco in 2025 if you’re a builder — you absolutely should — just don’t expect it to have the same level of serendipity as last year. On the other hand, if you’re a founder a bit further along on your journey who’s looking to meet other high-quality founders focused on building their companies, there’s no better time to come. Just know that you need to be more intentional about your visit and manufacture the outcomes you want.”
What you’re seeing now is the natural result of that shift. The folks who thrived during the meetup and party-heavy experimentation phase of AI’s emergence are finding that, “…there’s nothing too interesting to discuss at a party anymore.”
But it’s not because interesting work isn’t being done. It’s because the people doing interesting work no longer have time to go to parties.
(Side note: a few weeks ago, I wrote about the fact that the tide is starting to turn against rage bait as a strategy for product development and marketing. I suspect that there is a significant overlap in the venn diagram of “Founders who are leaving loudly SF in 2026” and “Founders who rely heavily on rage bait as a strategy”.)
3. The AI Backlash is Here
For a few weeks now, there’s been an increasing amount of coverage about an impending “AI backlash”. Traditional media, social media and countless “2026 predictions” have referenced the turn in public sentiment against AI.
Rather than focus on public sentiment, I thought I’d share some observations on how investors are behaving.
On the one hand, legitimate AI startups are as hot as ever. We’re seeing a degree of preemption and FOMO for hypergrowth AI startups that’s on par (if not greater) than what happened during ZIRP.
On the other hand, I’m seeing an increasing number of investors respond to credible “good-but-not-great” AI startup pitches with a resounding, “meh.”
Overall, it’s clear that the AI honeymoon is over. What’s intriguing to me is that I’m seeing more VC interest in AI startups that are targeting specific niches based on subject-matter expertise (and have real traction points) than in broad, big picture startups.
It’s almost as if vertical SaaS might not actually be dead…
4. The Impact of AI on Junior Roles
Speaking of AI, one of the pervasive narratives in the back half of 2025 was that it was going to kill all of the “junior roles.”
I can’t tell you how many founders I spoke to last year who excitedly proclaimed that they were cutting their staff, getting rid of all of their junior employees and that “AI was the future.” Why hire junior employees when you can just have experienced, senior hires managing teams of agents?
With economists and politicians alike warning of increasing youth unemployment, this trend seemed like a near-inevitability.
Aside from the fact that this didn’t make sense to me as a long-term strategy (if you don’t ever hire junior people, how will you end up with experienced employees when those senior staff members move on?), I couldn’t help but observe a sharp contrast between different companies that I was connected to. At the same time that many CEOs were culling their junior ranks, others were on a hiring binge. I felt a distinct sense of deja vu…
And then it dawned on me: the founders who were proclaiming that AI was end of junior hiring were the same ones who, five years prior, predicted that work-from-home was the future. And you know what they have in common?
They all sucked at managing people.
I’m not suggesting that the job market for new graduates is rosy by any means. But my personal observation is that ambitious, highly-motivated young people with technical skills are in extremely high demand. Especially in companies where there’s a willingness to focus on nurturing, growing and developing talent.
But here’s the zinger: in many cases, Gen Z employees are often more productive than their more experienced colleagues, specifically because they are the first ever AI-native generation. While they may lack experience, their willingness to embrace and utilize AI far outpaces what many of their older colleagues are willing (or able) to do.
Which leads me to two, admittedly knee-jerk, conclusions:
CEOs arbitrarily reducing their junior ranks and/or completely pausing junior hiring is, broadly speaking, a negative signal
CEOs prioritizing the hiring and development of AI-native / Gen Z employees (and, even better, intentionally pairing them with more experienced colleagues) is a positive signal
5. Accelerators are Hot Again
Many of you know that my first stop as an investor was at 500 Startups. Ten years ago, there was genuine competition in the accelerator game. In those days, YC was focused mostly on California, TechStars was championing the “rise of the rest” while 500 was staking its claim to the rest of the world.
But 500 Startups and TechStars both lost the plot, leaving YC to assert its dominance. With YC’s move to four batches a year ago, there’s been little room for competitors to wiggle in. But the tides are turning. Over the past two years, a number of challengers — both new and old — have started to gain momentum.

At one end of the spectrum are the megafunds. Almost all of them now offer some form of accelerator or incubator — either as standalone entities or as platform offerings for their portfolio companies (Canadian investor David Crow wrote a great piece last year about how larger funds are trying to manufacture funnels with this approach).
Most notable amongst the megafunds is a16z, which originally launched its Speedrun accelerator in 2023 as a gaming-focused offering. The firm has since pivoted Speedrun into a generalist accelerator and poured considerable resources into the program (it’s deployed more than $180M to-date and is currently in the process of significantly scaling up its team).
At the other end of the spectrum, we’re seeing a resurgence of both small, dedicated accelerators and offerings from Seed-specialist VCs. There’s Mint from BTV, Pear X from Pear Ventures, and recent entrants like Neo and HF0. Add to that the fact that several international accelerators — most notably, London-based Entrepreneur First — are refocusing their efforts on the Bay Area and it makes for an increasingly crowded field.
With both founders and investors alike looking for an edge, it feels like the pendulum is swinging solidly back from the “hands-off” investing style of the ZIRP era to the more “hands-on” style of years past. At a time when AI is making it cheaper than ever to get a company off the ground, I think we’re going to quickly see a new level of competition amongst credible accelerators (and between accelerators and pre-seed VCs).
And that’s great for founders.
Things I Think I Think - Q3 2025
The memories of summer are fading. Burning Man is over. And the kids are back in school. Here are 5 Things I Think I Think: Q3 2025.
The memories of summer are already starting to fade away. Burning Man is over. So is the After Burn. And the After After Burn. Best of all? The kids are back in school 🙌. Time to shift gears and get into fall with my latest homage to legendary sports columnist Peter King.
Here are 5 Things I Think I Think - Q3 2025 Edition:
1. Orange is the New Triple, Triple, Double
It used to be that venture capitalists’ preferred roadmap for success was the “triple, triple, double, double, double”. The path is simple (at least, according to MBA-types who’ve never actually run a business): Just get to $1.5M in revenue, then triple it the following year. And triple it the year after that. And then double it for the next three years. Voila! You’ve got a $100M business and are ready to go public.
Now, some VCs are latching onto an even more audacious blueprint. Hemant Taneja of General Catalyst recently had this to say:
“Triple, triple, double, double is definitely dead. I tell our investors: don’t bring that to me <laugh>…Going from $1M to $3M to $9M is not interesting…you gotta go, like, $1M to $15 - $20M to $100M.”
His comments were polarizing, to say this least.

As aloof as Hemant’s comments might seem, they reflect the converging perspective of a growing number of VCs. At the start of the summer, I wrote about some of the changes that are happening amongst early-stage investors. In the post, I shared the following anecdote:
“I [recently] met a founder who was extremely frustrated with the lack of progress they’d made raising capital from VCs. In relaying their experience to me, the founder proclaimed that they had a stellar founding team with an amazing track record, a working prototype and clear evidence of a market need. Yet they were getting zero traction with investors.
Later that day, I looked up the founder’s company and thought to myself, “what a nice, incremental business.”
…
To be clear, there was nothing wrong with this founder’s business. It was — and is — a perfectly reasonable B2B SaaS company. The type that was built to solve a real problem and that very likely would have been able to raise VC funding 2 years ago (not because of ZIRP, but because it is a perfectly reasonable company solving a real problem).
Yet in comparison to AI companies, with their unprecedented growth trajectories, and deep tech companies, with their imagination-bending potential, it just felt…
…incremental.”
It used to be that a startup achieving “triple, triple, double, double, double” growth was rare and exciting. Only the best-of-the-best could achieve it. Now, the definition of “exceptional” growth has fundamentally changed. And, like it or not, VCs chasing power law outcomes can’t unsee that.

2. But, But, But…
As much as some VCs — particularly those associated with Silicon Valley’s billion-dollar funds — are extolling the virtues of these AI-driven money machines, other investors are raising the alarms.

So what does all this mean for founders?
For starters, if your company is building an AI-first “prosumer” product — or anything where distribution should reasonably follow AI adoption — this type of extreme growth is what investors are looking for. But, more than that, if you’re any type of SaaS-y company, this is the benchmark against which you’re now being compared.
That may not seem fair, but it’s happening.
We’re now seeing companies go from zero to $10M in ARR (or more) in less than two years with an increasing degree of regularity. To be clear, this is still very much the exception to the rule, but it’s occuring frequently enough that a small but growing number of VCs are holding their dry power until and unless they see such growth.
At the same time, many investors are questioning how sticky this revenue will be. What percentage of these companies will be able to maintain their revenue and customer base after the initial growth explosion (vs. seeing it collapse like a house of cards)? At this point, we simply don’t know. So while some VCs are tripping over themselves to chase these extreme growth companies, others are steering clear.
If you’re a founder raising capital this fall, my biggest advice is to cast a wide net. There’s a lot of capital flowing right now, but also an unusual degree of opacity around what individual investors are looking for.
3. A Tale of Two Ecosystems
Speaking of capital flowing, the difference between what’s happening in Silicon Valley right now and what we’re seeing in the rest of the world couldn’t be more stark.
It’s only one month into the fall fundraising season and I’ve seen dozens of pre-seed deals happen in the Bay Area in only days, while Seed and Series A rounds are going from first meeting to term sheets in 1-2 weeks. By contrast, I’ve spoken with founders in Canada, the UK and elsewhere who are struggling to get local investors across-the-line. Why the difference?
Outside of the U.S., the dry powder we’ve been hearing so much about for the past few years is starting to dry up.
Take Canada, for example, According to a recent Betakit article,
“Canadian VCs, particularly emerging managers, are struggling to raise new capital. According to BDC, only 17 funds raised a total of $2 billion in 2024, marking a year-over-year decline in dollars raised and average fund size. The share of emerging managers is shrinking: the report shows that established managers, considered to be those who have raised more than three funds, now make up 20 percent of active GPs—the largest share in a decade.”
To put that in context, in 2024 a16z raised 3.6x as much capital as all Canadian VCs combined.
A year later, we’re starting to see the impact. According to the Canadian Venture Capital Association, in the first half of 2025 there was “…a 26% decline in dollars invested and a 22% drop in deal count [by Canadian VCs] compared to H1 2024.”
Why does this matter?
Throughout the world, early-stage funding rounds are overwhelmingly led by local investors. A small percentage of international founders each year succeed in raising capital from Silicon Valley VCs, but the vast majority rely on local VCs and angels for their first few rounds of funding. The mythical U.S. lead investor is just that: a myth. A reduction in early-stage domestic capital can, therefore, have a long-term negative impact on a country’s entire tech ecosystem.
A drop in the share of emerging managers (newer VCs) is an even bigger red flag for a country’s startup ecosystem.
Bottom line: if institutional and corporate LPs outside of the U.S. continue to sit on their hands, their countries risk missing out on what looks to be the biggest and most consequential technological (and economic) shift in our lifetimes.
So yeah…it’s a big deal.
4. Founders Are On the Move
While VCs in some countries are struggling, founders are sprinting as fast as they can. And going wherever they need to.
A few weeks ago, I reached out to a handful of young Canadian founders about putting together an impromptu mixer in San Francisco. I figured 10 or 12 might show up. More than 30 founders descended on the bar in Lower Haight (much to the chagrin of some of the locals).
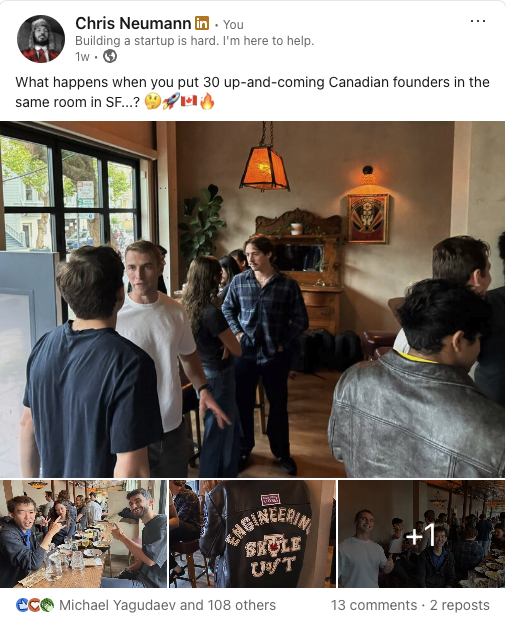
That might not seem like a big deal, but consider this: nearly half of them flew in from Vancouver, Toronto and Montreal just for this event.
For awhile now, I’ve observed an increasing mobility amongst founders — particularly Gen Z founders — who seem utterly unencumbered by the cost or complexity of going back-and-forth between cities. As someone who’s spent a long time championing the importance of spending time in Silicon Valley, I consider this a strong signal when it comes to the potential of the next generation of founders. But even I’ve been shocked by how quickly and widely their expat networks are expanding — often without any involvement or support of past generations of founders.

There’s a lot to unpack here (and I plan to in a future post), but for now I’ll say this: the mental model that the current generation of founders has when it comes to operating in and across multiple ecosystems if fundamentally different than generations past. And that’s really exciting.
5. Speaking of On the Move
The past few weeks in Startupland™ have been dominated by coverage of the U.S. administration’s introduction of a $100,000 fee on H-1B applications. Since that announcement was made, multiple countries — from Canada to China — have introduced or are in the process of introducing policies designed to lure foreign workers away from the U.S.
While those efforts are domestically very popular, I continue to believe that the reactions to the policy change (both inside and outside of the U.S.) are much ado about nothing. While some people and companies will undoubtedly be impacted by the change, I don’t believe that this will result in a sudden flow of talent away from the U.S. Here’s what Democrat megadonor Reed Hastings had to say:

Reed’s take was certainly against the flow when it came to Silicon Valley reactions, but I think it’s the correct one if you reframe the categorization of high tech visas as follows:
H-1Bs will be used for very high value jobs
O-1s will be used for very high value people
AI Won’t Actually Change Everything
The current gap between the tech world’s obsession-of-the-moment and the rest of the world seems more like a chasm.
Last week, I took a few days away from preparing for this year’s BC Founders Day and escaped into the British Columbia wilderness.
I’ve written before about the importance of finding what recharges you. For me, a few days in nature (preferably somewhere devoid of cell phone coverage) is ideal. One reason why I do this on a regular basis is because of how it rejuvenates me. The healing benefits of spending time in nature have been proven time and time again (not only is it okay to go outside, it will make you more effective as a founder).
But there’s another reason why nature is my preferred escape: it forces me completely out of the bubble of Startupland™.
I don’t wanna goooooooo!
Usually when I head into the wilderness, I use the time to reset and reflect. When I go with my kids (as was the case last week), I try to simply focus on them (p.s. if you haven’t gone camping with kids before, it really is one of the best things in life).
Despite nature throwing an atmospheric river at us — after nearly 60 days of pure sunshine, no less — our brief trip into the woods was an undeniable success. There was exploring, swimming, laughing, getting dirty, getting frustrated, overcoming challenges and, of course, s’mores.
You know what there wasn’t any of? AI.
The only prompting I did was trying to get my boys to help wash the dishes. The only agent I encountered with was the one checking tickets for BC Ferries.
AI didn’t help us put up the tent when we arrived late to our campsite and it didn’t make it any easier to anchor a tarp over the picnic table when the skies suddenly opened up.
AI didn’t help my son spot these two bald eagles
I wasn’t expecting to have any work-related epiphanies on this particular trip, but as I sat on my well-worn REI camping chair, I was struck by how wide the gap had become between Startupland™ and the outside world since the emergence of AI. There is always a sizable distance between the tech world’s obsession-of-the-moment and the perspective of the rest of society. But it feels like the current AI-centric gap is closer to a chasm.
If you’re like me, you’ve probably had a lot of conversations with other residents of Startupland™ recently that leave you feeling like we’re all in a mad rush to maintain relevance. Investors and founders are sprinting to capture market share, CEOs are rushing to make their workforce AI-native, and everyone seems desperate to leverage AI and agents any and every way possible.
But in the rest of the world? Not so much.
That’s not to say that the masses aren’t already benefiting from AI. It’s creeping into everyone’s cell phones, search tools and social media. But in many industries, AI isn’t really changing anything. And it probably won’t anytime soon.
AI won’t change how the friendly campground hosts we met on our trip welcome visiting campers. It won’t change how the small town ice cream store we stopped at doles out scoops of ice cream to wide-eyed children. Nor will it change the operations of the mini golf course we played at, the local bait and tackle store we bought supplies at, or the fish-and-chip shop we patronized before boarding our ferry.
And while it might be easy to dismiss these as niche examples that only representing the long-tail of the economy, such observations are increasingly being made by larger players. Earlier this summer, Thomas Bravo raised nearly $35 Billion for three new funds. The firm’s co-founder and managing partner, Orlando Bravo, was asked how they leverage AI and where he saw potential,
"Summarizing data. But right now there is not a compelling use case we see that will dramatically affect how we add value."
Around the same time, Jason Lemkin of Saastr made this observation,

I’m certainly not trying to downplay the impact and importance of AI — to the tech world or beyond. AI represents the most significant technological advancement in a generation. But it’s worth remembering that there are a lot of places where AI isn’t necessarily top of mind.
Generational wealth will undoubtedly be made by many working in and around AI. But there are also an incredible number of opportunities that remain for founders willing to look where others don’t.
Plus ça change, plus c'est la même chose.
VCs are Changing Their Tune on Conflicts
VCs generally do not invest in startups that compete directly with existing portfolio companies. But that norm is changing.
Founders and investors aren’t always on the same page.
But for most of the history of Startupland™, there has been one industry norm that both sides agreed on: in general, VC firms do not invest in startups that compete directly with existing portfolio companies. In fact, most VCs go to great lengths to ensure that (1) there are the no direct competitors in their portfolio, and (2) there is enough “room” between portfolio companies to allow them to pivot without risk of running into one another.
I previously wrote about this norm in a post titled Don’t Talk to Your Competitor’s Investors. The post walks through the historical reasons for this norm (both moral and legal), while noting that,
“The best investors don’t want to be in a position of conflict. They don’t want to have to choose between your company and their portfolio company, so the moment they sniff an overlap, they’ll pump the brakes.”
But the tides are changing and this long-accepted norm may soon be a thing of the past.
Last week, Charles Hudson of Precursor Ventures suggested that, with multi-stage funds getting larger and larger, the tradition of venture firms not investing in competitive companies may soon go away:
“As venture fund sizes keep getting larger, I do think that the tradition of venture firms having a norm (if not a stated policy) to not invest in competitive companies is likely to go away. This is simply a function of the fact that as venture funds have grown larger, it has become increasingly essential for those firms to be associated with the biggest and most important companies. The larger the fund, the more important it is to be an investor in the companies that are true outliers; there is no way to make the fund math work if you are not in those companies unless you are in other, similarly-situated companies. My sense is that there is more money chasing outliers at the moment than there are outlier companies to fund.”
Charles goes on to suggest some approaches that large funds can take to reduce the impact of such conflicts-of-interest, though he also notes that, “this is an issue where the business model for funds is at odds with what most founders want.”
His post focuses mostly on the dynamics of large multi-stage funds, but smaller funds and single-stage specialists are also starting to rethink their approach to competitive investments.
Why the Change of Heart?
Before you rush to the conclusion that this shift is simply another case of greedy VCs behaving badly, it’s worth noting that a couple of significant changes have happened in the past few years that fundamentally change some of the assumptions underpinning venture capital portfolios:
1. Companies are Staying Private Longer
Venture capital firms have historically been built on an assumption that most exits would occur within 7 - 10 years. Over the past decade, that number has crept higher, as many businesses have chosen to stay private longer. Add to that the many macroeconomic shocks we’ve had in recent years, and its increasingly common for early-stage VCs to hold positions in their winners for 15 years or more.
Think about what you were doing 15 years ago.
In my case, Aster Data was raising its Series C (it wouldn’t be acquired for almost another year — and DataHero wouldn’t be founded for a year after that). The cloud wasn’t really a thing yet. Neither Stripe nor Snowflake had been founded. And peer-to-peer anything hadn’t caught on.
So yeah…
2. Technology is Changing Faster
Step back and think of everything that has come into being technologically speaking over the past 15 years. Now think about how much faster innovation is happening as a result of AI.
In the past, it was reasonable (and, in many cases, prudent) for an early-stage fund to remain steadfast in its commitment to avoiding portfolio conflicts even after 10 years. After all, the fact that a company survived to its tenth birthday suggested that it was probably doing well. Moreover, a slower rate of change of technology implied that a new startup entering the same sector was likely to be a genuine competitor.
Things are different now. Even if two companies with an age gap of 10 years are likely to be competitive from a sector standpoint, chances are their technologies, target personas, and value propositions are fundamentally different.

3. Startups are Pivoting Sooner
A third major shift that’s occurred as a result of AI is that startups are able to validate (or invalidate) concepts sooner than ever before. It’s now increasingly common for investors to back a company, only for the founders to pivot within months of the investment closing.
In the past, it might take a company 6 - 9 months to determine that its original hypothesis wasn’t going to work, and then another 3 - 6 months to come up with something new. Today, startups can achieve both of those in a single quarter. In addition, we’re seeing early-stage startups pivot further away from their original ideas, making it harder than ever before for VCs to ensure adequate “space” between portfolio companies.
At this point, some early-stage VCs are investing with the presumption that the original idea will fail. They’re backing strong teams, but with no real idea of what the ultimate product will be (an approach founders typically love, but one that can result in unintended consequences — especially when it comes to portfolio conflicts).
4. Companies are Living Longer
Last but not least, many more startups that failed to achieve product-market fit have found ways to survive longer than ever before. Historically, if a VC-backed company didn’t achieve its goals, that company would either be acquired or shut down. Today, we’re seeing many more companies transition into long-term sustainable (but slower growing) businesses. While that can be great for the founders, it’s not necessarily the outcome investors signed up for.
The problem occurs if a company has changed trajectories to one that no longer fits the VC business model, yet the founders expect their investors to continue to uphold a moratorium on investing in potential competitors.
What Can Be Done?
First off, I agree with Charles’ assertion that the norm of VCs not investing in competing companies is going away. As a former founder, I hate this. But as an investor, I understand it.
From the perspective of multi-stage funds, they simply have to chase extreme outliers, portfolio conflicts be damned. Mega funds will increasingly do this until it’s widely-accepted behavior (hopefully, with some of the best practices Charles suggests).
On the other hand, I think that most early-stage / single-stage investors continue to believe that “the norm of not investing in competitive companies [is] a feature, not a bug” (I sure do!). The best Pre-Seed and Seed stage VCs are so involved with their portfolio companies that any conflict — real or perceived — is going to cause problems. So my assertion from two years ago — “the best investors don’t want to be in a position of conflict.” — still holds true.
That said, it’s no longer pragmatic for early-stage investors to think about conflicts in such absolute terms. Especially not over a 15-year horizon.
As we look ahead, I think there are some practical approaches that Pre-Seed and Seed-stage VCs can take to reasonably mitigate conflicts and maintain strong founder relationships, while future-proofing their ability to make reasonable new investments. All of which require clear, transparent communication with founders. For example:
Adopting an “expiration date” policy for avoiding portfolio conflicts — Instead of having a blanket moratorium on investing in competitive companies, consider a policy that expires after a certain amount of time or under certain conditions (e.g. no material forward progress in 36 months). The goal here isn’t to abandon companies that are struggling or to normalize “do-overs” (though I’m sure some investors will do that). Rather, it’s to provide clear guidelines as to when the investor might reasonably consider a competitive investment. Conceptually, this is closer to a standard employment non-compete (which founders and investors alike are very familiar with).
No guarantees in the case of a pivot — This is a touchy one for founders, but from an investor’s perspective, it can be challenging to support a competitive moratorium after a startup makes a significant pivot. Especially if the VC is not confident in the pivot (or in the team’s ability to execute the pivot). Early-stage VCs generally have little control over a startup deciding to pivot. Most still want to back their portfolio companies after a pivot — at a bare minimum, they have a financial incentive to do so — but if the pivot is into an area that the founding team has no prior experience in, it’s not unreasonable for the investor to want to keep their options open.
No guarantees below a minimum ownership — This is another one I’ve seen cause problems (in both directions). On the one hand, I’ve seen founders squeeze investors down to an inconsequential amount of ownership, only to expect that VC to not invest in competitors. On the other hand, I’ve seen VCs intentionally write small scout checks, then use the information they gain to make large investments in competing companies. Making clear the expectations in both directions will go a long way towards a smoother, long-term relationship.
Interestingly, I think that founders will broadly “get over” a shift in behavior by multi-stage funds and that conflicts within early-stage funds will end up being more prominent. (We generally don’t expect good service from Chase or Comcast, so we’re not disappointed when our experience sucks.) Conflicts within smaller funds — particularly those known to be more “founder-friendly” are where we’re likely to see the drama.
How investors choose to adapt their policies on competitive investments — and how transparent they are about those policies — may very well become a future marketing point. Regardless, founders should absolutely ask potential new investors what their current policy is on investing in competitive companies, how they view that in light of pivots, and whether or not they expect it to change in the future.
Some final thoughts from Charles:
“Most founders lack significant “hard power” (i.e., the right to block an investment) in these negotiations; funds can and do invest in competitors if they choose to do so. However, there will always be a set of founders who possess soft power and will utilize it to encourage their investors not to engage in such behavior. The universe of founders with meaningful soft power to influence this is very small, but that universe of founders is very powerful.”
What’s Going on with Early-Stage Founders?
What now we’re seeing the manifestation of the shift Everett Randle warned about back in 2021.
A few weeks ago, I shared my thoughts on what’s been happening recently in the early-stage investment market, which is more bifurcated than it’s ever been. In short, I believe that we’re currently witnessing both a realignment of the investment strategies of many early-stage VCs and a fundamental shift in how the best founders raise capital. In my previous post, I dug into the first part of that statement. This week, I’m going to dig into how and why top founders are changing their approach to fundraising and the impact it’s having on the venture capital industry.
To set the context, let’s start with an overview of a fundamental shift that’s currently taking place in venture capital.
Venture Capital is Dead!
Right now, there are an incredible number of hot takes about venture capital. Try searching “venture capital is dead” and you’ll see pages upon pages of blogs and opinion pieces on why VC is dead (or, at least, VC as we know it). Read a little further and you’ll quickly realize that the majority of these takes were written by people who provide alternative products to venture capital or who have a philosophical opposition to the VC model. Add to that a handful of well-meaning but inaccurate posts written without the benefit of knowing the numbers behind-the-scenes (I promise that a handful of multi-billion dollar funds registering as RIAs does not portend the death of venture capital 😉), and you’re forgiven for believing that, this time, VC really is dead.
I’m sorry to say, VC is not dead. But it is definitely changing.
The Bifurcation of Venture Capital
The past decade saw the emergence of VC “megafunds”, as leading firms raised larger and larger funds in order to expand their capabilities and competitive advantages. That trend went into overdrive following the ZIRP crash, with institutional LPs desperate for safety as exits dried up.
Last year, 9 firms raised half of all VC capital in the US (more than $35 billion). The top 30 firms accounted for 75% of all capital raised by US VCs:

At the other end of the spectrum, emerging funds — in particular, those less than $50M in size — saw an increase in capital raised. At the extreme end of this trend are microfunds — funds less than $10M in size — which accounted for 42% of the funds closed in 2024.
In contrast to the perceived safety of megafunds, LPs tend to invest in sub-$50M funds because of the combination of (1) a focused thesis and (2) a disproportionate potential to generate outsized returns. As one longtime investor put it,
“There are a dozen ways to 10x a $30M fund; there’s only one way to 10x a $3B fund.”
Rex Woodbury describes these two categories as “artisans” and “scaled asset managers”:
“Artisans focus on people; they invest capital, sure, but their value really shines in hands-on partnership…Asset managers are more about the money—their form of venture is less about craft than about putting dollars to work.”
The Tail Wagging the Dog
Ultimately, LP investment dollars follow returns. And returns come from the ability of VCs to successfully invest in the best founders and companies.
So while it’s interesting to talk about the bifurcation of venture capital in terms of LP dollars raised, this is actually a lagging indicator of a behavioral shift on the part of founders.
Everett Randle of Kleiner Perkins predicted this shift back in 2021. Specifically, he foresaw the “middle squeeze” that we’re currently seeing in venture as akin to what happened in retail during the decades prior. Since the turn of the millennia, consumers have increasingly chosen luxury brands (e.g. Tiffany) and mass-market retailers (e.g. Walmart) over the middle ground. Everett noted,
“The most exposed and vulnerable will be funds stuck in the “middle”. When choosing between capital providers, sometimes founders will want the $12 Amazon Prime 1-day-shipping Carhartt T-Shirt, sometimes they’ll want the $1,500 Gucci Cardigan, but very rarely will they want the $22 J.C. Penney Hoodie. You really, really don’t want to be the VC version of J.C. Penney.”
Today, Founders Really Do Have the Power
There was a time not so long ago when the power disparity between founders and VCs was so extreme that investors held virtually all the chips. In the early days of Aster Data, we needed to raise $1M in order to buy the physical servers that we needed to develop and test our software on. There was no “bootstrapping” for enterprise software companies in those days. Either we raised venture capital or the company would not exist.
Fast forward 20 years later and the tables have turned, primarily as the result of three major shifts:
Reduced Costs - AWS drastically reduced the overhead costs of developing and deploying software. The resultant cloud / SaaS offerings drastically reduced the overhead costs of building a company. The combination meant less capital required to get many new startups off the ground. The recent innovations in AI have put this dynamic on steroids.
Shorter Time to Revenue - Not only have technical advancements reduced the cost of bringing software products to market, they’ve also reduced the time to initial revenue. The potential for global distribution from day one has fundamentally changed the revenue trajectories for many startups.
More Funding Options - In parallel with these fundamental changes in company formation, we’ve seen an explosion in funding options for startup founders. The emergence of microfunds, operator VCs, crowdfunding and a proliferation of angel investors — combined with an increased willingness by VCs to invest globally — has led to far more capital options for founders than ever before.
Which brings us back to the bifurcation of venture capital…
How Founders Today Think about Venture Capital
What we’re seeing with early-stage founders today is the manifestation of the shift Everett Randle warned about back in 2021. With more options (and, thus, more power) than ever before, the world’s best founders are increasingly rejecting the “VC version of J.C. Penney.” Some are rejecting venture capital outright. Others are taking the “seedstrapping” approach to fundraising, wherein they raise a single round to get things off the ground and strive for profitable growth from then on. Those who do seek out external funding are overwhelmingly choosing between one of two options:
Scaled Asset Managers: Megafunds, with their globally-recognized brands, deep pockets and comprehensive resources
Artisans: Emerging Managers, with their focused specializations, narrow investment theses, and clearly-defined value-adds
In the past three years, this massive shift has contributed to more than 2,000 VC firms globally shuttering their doors.

If you’re surprised by the scale of the numbers above, it’s because the U.S. tech media (which is the source of much of the world’s news on all things tech), really hasn’t covered this. And that’s because such seismic shifts have happened there before. The first such shift happened in the early-2000s, after the dot-com bubble burst. The second occurred after the financial crisis of 2008. In both cases, a significant percentage of under-performing VC firms failed, only to be replaced by a new generation of emerging firms.
Case-in-point: megafund a16z was founded in 2009.
But in the rest of the world, this is really the first time that domestic venture capital industries have experienced an existential crisis of this magnitude. Up until now, they’ve mostly been sheltered by virtue of:
A hesitancy by U.S. VCs to invest internationally
A hesitancy by local founders to seek capital internationally
In other words, until recently, many VCs around the world benefited from a local advantage.
But if our earlier retail analogy is anything to go by, that local advantage is about to disappear forever.
In the consumer bifurcation of the past two decades (towards focused, direct-to-consumer brands and cheaper, mass-market retailers), one of the biggest losers was generic local retailers who depended on a local advantage but offered little more than higher prices to their shoppers. It turned out that, when presented with options, the vast majority of consumers simply weren’t willing to pay a higher price solely to subsidize a local retailer.
The same is proving true when it comes to venture capital.
Today’s founders — empowered by the realization that they hold more power than ever before — are increasingly unwilling to accept a lower-quality product from investors simply because those investors are local. And many mid-sized VCs around the world are waking up to the reality that they may, in fact, be the J.C. Penney of VC.

Before I go any further, I want to be clear: I’m not suggesting that there is zero value in local venture capital. Quite the contrary.
I believe that a strong domestic VC industry — especially at the early stages — is an essential component of any tech ecosystem. Despite all of the technological and cultural shifts that are happening, the vast majority of Pre-Seed and Seed deals are led by local investors. Which means that the availability of strong local early-stage funding options is critical to the success of startups around the world.
But once you’ve got a product and/or some early traction, all bets are off. At the later stages (and, increasingly, at Pre-Seed and Seed for top founders), the competition for the privilege of investing in their companies is now global.
Jack Newton, the intensely patriotic CEO and Founder of Canadian unicorn Clio, recently highlighted this perspective, noting that,
“Though it might be nice for Canadian investors to reap the returns of domestic companies, the creation of jobs and homegrown talent is the most important thing,”
So how are VCs around the world reacting? Surprisingly similar to how local retailers did twenty year ago when threatened by “big box” retailers. In a striking parallel to local business associations of the past, venture capital associations around the world are increasingly trying to tie the survival of their members to that of the ecosystems in which they operate.
For example, outgoing CVCA president Kim Furlong recently inferred that a drop in deployment by Canadian VCs in Q1, “…threatens the innovation economy we’ve worked hard to build.” But the data doesn’t support her assertion. While funding from Canadian VCs into Canadian startups fell in Q1, overall funding in Canadian startups actually rose according to PitchBook, with U.S. investors participating in 80 per cent of Canadian venture capital investments that quarter.
Adapt, Evolve, Compete or Die
Today’s founders are emboldened by choice and, just as with consumers of the past, there’s no going back to mediocrity for them. As Everett Randle predicted, the most exposed and vulnerable funds are those currently stuck in the “middle” — surrounded by heavily-resourced megafunds on one side and a growing number of laser-focused emerging funds on the other. That leaves such VCs with the choice first posed by famed hedge fund manager Paul Tudor James: “adapt, evolve, compete or die.”
Thankfully, there are many paths forward for fund managers to take. They can reorient around a more focused thesis, as Canadian firm Two Small Fish and U.S. firm Susa Ventures did with deep tech (the latter via spinout fund Humba Ventures). They can develop compelling platform offerings, as many U.S. VCs did post-2008. Or they can even double down on a geographic advantage, demonstrating to local founders that they understand their needs better than anyone, as Toronto-based Golden Ventures recently did in spearheading the inaugural Toronto Tech Week.
In the coming years, we will see a number of prominent VC firms reorient around new strategies as this shift progresses. We will also see many shutter their doors as they fail to react to the changing landscape. But rest assured, ecosystems around the world will survive and thrive. With more and more new funds being created, founders will continue to have plenty of options even if J.C. Penney, Kmart or Hudson’s Bay close their doors.

Things I Think I Think - Q2 2025
Sending dispatches from the wilderness in between Canada Day and America Day. Here are 5 Things I Think I Think: Q2 2025.
It’s that magical week at the beginning of summer when school is out, the weather is nice and we all get to celebrate Canada Day and America Day. So let’s kick back with this year’s summer homage to legendary sports columnist Peter King.
Here are 5 Things I Think I Think - Q2 2025 Edition:
1. Liquidity, My Old Friend!
After what seemed like an eternity without exits, we finally saw several prominent tech IPOs and major acquisitions take place towards the end of Q2.
While these still represent a relative drop-in-the-bucket when it comes to the overall amount of capital deployed, the fact that some VCs are finally receiving some sweet, sweet liquidity is a big deal. It means long-overdue distributions to their LPs and, potentially, some amount of recirculation back into VC.
As the VC landscape continues its increasingly bifurcated convergence towards megafirms like Sequoia and A16Z and smaller, sub-$50M firms, an increase in LP liquidity will have a big impact on the latter category. That means more capital for early-stage founders creating exciting, new businesses.
2. Sovereignty Startups are Hot 🥵
In my Q1 update, I touched on the reactions that we were starting to see from the tech communities in Canada and Europe to the US tariffs, such as Build Canada and Project Europe. Those initiatives are now maturing into longer-term endeavors (Build Canada, for example, recently shared details on its next phase, following the Canadian federal election, which included the announcement of its inaugural CEO.)
Much like in the US, we’re seeing a lot of this startup energy converging in areas related to sovereignty (think defense, energy, manufacturing and AI). And the funding seems to be following (I’m looking forward to seeing the breakdown of early-stage funding from the first half of the year…AI notwithstanding, I suspect it will be eyeopening).
The challenge for many of these ecosystems they lack enough Pre-Seed VCs with the technical background necessary to underwrite pre-product companies in these spaces. A hard tech renaissance is happening — and many ecosystems around the world risk missing out.
3. B2B SaaS is Not 🥶
If sovereignty startups are what’s hot in startup ecosystems around the world, traditional B2B SaaS is not. In fact, Q2 has yielded the most bifurcated fundraising environment I’ve ever seen.

I said it on LinkedIn, so it must be true
In response to questions from founders about what I meant by this, I wrote an extensive post on this a few weeks ago titled, What’s Going On with Early-Stage Investing? The tl;dr is that we’re seeing a dramatic shift by investors away from the types of incremental tech businesses that they’ve backed over the past decade (think B2B SaaS, e-commerce, etc.) and towards technically-heavy startups that were the norm up until 2010 or so.
At this point, I think it’s safe to say that a significant percentage of startups that were within the strike zone of venture capital two years ago are now fundamentally out of play. And not just in the short term.
This isn’t about VCs chasing the latest trend. Between exit multiple compression and a growing belief that the long-term value of many SaaS businesses will trend to zero as AI continues to improve, a significant percentage of tech founders are going to need to rethink how they capitalize their company.
Personally, I don’t think that’s a bad thing. 99% of companies aren’t — and never were — a fit for VC (and that’s okay). Perhaps this shift will better align the behavior of founders and investors alike. It would be great to see VCs stop wasting founders’ time in categories they don’t intend to invest in. And maybe….just maybe…we’ll start to see new funding options emerge for the plethora of founders who are building interesting, but not exponential, businesses.
4. Some Big Changes are on the Horizon
A few weeks ago, I attended Creative Destruction Lab’s annual Super Session, where founders and investors from around the world converge each year on the University of Toronto. One of the most eye-opening panels consisted of a range of practitioners and researchers at the bleeding edge of AI, including executives from Neuralink, several startups currently in stealth, and Turing Award winner Richard Sutton.
While I can’t share everything that was discussed, it’s not an understatement to say that there are some truly massive changes coming in the next few years, particularly at the intersection of AI and health. We’re going to see some things that inspire us, as well as some that will undoubtedly make us question how we see the world. It’s an incredibly exciting time to be alive and be a participant in the global tech ecosystem.

5. Toronto on the Verge?
Speaking of Toronto, the city recently hosted the first-ever Toronto Tech Week (a grassroots replacement for Collision, which this year moved to Vancouver). While I was thrilled to see my hometown host another major tech conference, it was hard not to compare the local reaction to that of a sheltered teenager getting invited to a house party for the first time (and not knowing quite what to do). Toronto, on the other hand, demonstrated why it’s the third largest and fastest-growing tech ecosystem in North America.
The energy throughout the GTA was palpable. The overlapping activities showcased just how large and diverse Toronto’s tech community now is. At the same time, I couldn’t help but notice the same self-limiting themes that have historically held Toronto (and Canada) back creeping up throughout the week:
There was lots of talk of ambition, but almost as much talk about how Canadians don’t brag enough
There was entirely too much focus on government — in fact, I don’t think there was a single panel I attended where someone wasn’t complaining about what the Canadian government is or is not doing
And there were way too many navel-gazing comparisons to the US
Don’t get me wrong, Toronto feels like it’s on the verge of breaking out (like…really breaking out). But to do so, it needs to embrace what it is — and what it is not — in order to take its rightful place on the global tech stage.
Stop complaining, stop comparing, and just go! 🚀 🇨🇦 🔥
What’s Going on with Early-Stage Investing?
I have never seen a more bifurcated fundraising environment. What’s going on?
“I have never seen a more bifurcated fundraising environment.”
I recently shared this observation on LinkedIn in response to a post from the amazing Amanda Robson (“Robby”) of Modern Technical Fund:

Amongst the various responses — both sincere and snarky — to Robby’s post and mine were questions from a number of commenters,
“What do you mean?”
“Was there a time when this wasn’t the case?”

My instinct was to immediately respond, but I quickly realized that I didn’t know how to put in to words what I’ve been seeing. What I’ve been feeling.
In recent weeks, I’ve seen both sides of the proverbial fundraising coin. I’ve watched founders raise massively oversubscribed rounds in a matter of weeks, while others struggle on the brink of failure. I’ve spoken with early-stage VCs overwhelmed by the volume of high-quality companies they’re seeing, while others lament their inability to deploy capital.

Like many, I believe that there’s never been a better time to build a company (I can only imagine what we could have achieved at DataHero or Aster Data if we had the types of AI-driven tools that are available today). I also think that it’s an incredible time for founders to raise capital. Yet in both private and public conversations, I’ve been challenged on this latter point by founders and VCs alike (ask anyone who attended my recent Web Summit talk 😉).
What’s going on?
For starters, contrary to what some more cynical observers have suggested, this isn’t just a “return to normal”. The difference in fundraising experience between founders whose companies are “on thesis” and those that aren’t is far more pronounced than it was pre-2021. It’s also not the case that investors have already forgotten the lessons they learned post-ZIRP and are rushing into bad investments driven solely by FOMO (VCs still don’t skip diligence).
I believe that what we’re witnessing today in the early-stage market is both a realignment of the investment strategies of many early-stage VCs and a fundamental shift in how the best founders raise capital.

For the purposes of this post, I’ll focus on the behavior change that’s happening amongst early-stage VCs (and many angel investors) and save the founder perspective for another day.
Let’s start with the numbers. Carta’s recent State of Private Markets: Q1 2025 Report shows that the number of Seed deals has plummeted year-over-year, but the average valuations have increased sharply (including for bridge rounds).

Notwithstanding my standard disclosure that early-stage funding data is incredibly unreliable (as a result of the fact that many rounds are not disclosed until well after the investment is made), this tracks with what I’ve seen in the market: fewer rounds are happening, but those that do are oversubscribed, resulting in higher valuations.
But why?
On the one hand, large multistage funds are certainly throwing around more money, but that isn’t enough to explain this data. It’s also naive to think that investors are blindly chasing anything and everything AI.
…or is it?
The “aha” moment came to me in three acts…
1. The Oracle’s Report
First, there was the recent release of legendary analyst Mary Meeker’s first “Trends” report in 6 years, focused on all things AI. In a corresponding interview with Axios’ Dan Primack, she noted,
“We've never seen anything like the user growth of ChatGPT, particularly outside the U.S., and it shows how the global dynamics of tech and distribution have changed.
I wasn't around for the evolution of the mainframe or mini-computer, but have read up on it and was around for the PC, desktop internet, mobile internet, cloud, and now AI. This is such a faster pace of change.”
A lot of folks have compared the potential impact of AI to the emergence of the cloud (and, in particular, the impact of AWS) and the internet before that. Both are reasonable precedents in terms of the scale of impact, but we really have no precedent when it comes to the rate of growth. Consider the following:
AWS
Initial beta release in 2002
First infrastructure service, SQS, was released in 2004
S3 was released in 2006
EC2 was released in full production in 2008
AWS surpassed 1 million users in 2012
International releases were staggered, sometimes years after the US release
Open AI
Initial beta release in 2018
Initial public release (GPT-3.5 / ChatGPT) in 2022
ChatGPT surpassed 100 million users two months later (January 2023)
o1 was released in December 2024
ChatGPT had 400 million users in 188 countries as of February 2025
AWS took approximately 10 years to get to 1 million users. ChatGPT took 2.5 years to get to 400 million uses.
Of course, this is not an apples-to-apples comparison (as AWS’ users are almost exclusively developers while ChatGPT is a general use program). But if we take that growth rate as an approximation for the growth of the underlying infrastructure (and what we’re subsequently seeing in agents and other AI-driven technologies), it’s clear that Mary’s observation is far from an understatement. The adoption of AI and AI-related technologies is happening faster than any foundational technology in history.
And a big part of that is due to the fact that these platforms are generally made available around the world from day one.
2. The Deep Tech Investor
A few days later, Leo Polovets of Humba Ventures, a prominent early-stage deep tech fund, posted the following on LinkedIn:
While the post itself was tongue-in-cheek, the message struck a chord with me. Leo is very well-respected VC who has both worked for and invested in multiple consequential companies. He’s making big bets, but not necessarily in AI.
This also maps to what I’ve been seeing in the market. While I’ve met with plenty of founders of AI-centric companies as of late, I’ve also met strong, ambitious founders working in manufacturing, space technology, transportation, infrastructure, and the mining of rare earth minerals.
There are a lot of founders working hard to solve big, consequential problems right now. Not only in AI.
3. The Frustrated Founder
In the midst of all of this, I met a founder who was extremely frustrated with the lack of progress they’d made raising capital from VCs. In relaying their experience to me, the founder proclaimed that they had a stellar founding team with an amazing track record, a working prototype and clear evidence of a market need. Yet they were getting zero traction with investors.
Later that day, I looked up the founder’s company and thought to myself, “what a nice, incremental business.”
“…incremental business.”
I don’t know why that particular phrase popped into my head, but that’s when everything clicked.
To be clear, there was nothing wrong with this founder’s business. It was — and is — a perfectly reasonable B2B SaaS company. The type that was built to solve a real problem and that very likely would have been able to raise VC funding 2 years ago (not because of ZIRP, but because it is a perfectly reasonable company solving a real problem).
Yet in comparison to AI companies, with their unprecedented growth trajectories, and deep tech companies, with their imagination-bending potential, it just felt…
…incremental.
Right now, we are entering a period of monumental technological change. Virtually every industry is going to be impacted by AI. At the same time, consequential technologies are on the verge of disrupting countless industries from energy to transportation to manufacturing to defense. Founders building in those spaces or who are able to convincingly argue why their company will benefit from the changing landscape are having more success fundraising than ever before.
But for founders of nice, incremental businesses. The type that solve a real problem and that very likely would have been able to raise VC funding 2 years ago, it’s a different story.
Not because they aren’t good businesses. But because they no longer capture the imagination. Which in the mind of an investor translates to a lower potential return (and always remember, the job of a VC is first and foremost to generate a return for their LPs). Moreover, in many cases, it’s not clear if the problem they’re solving will even be around in 5 years.
That e-commerce company you’re building? Is it relevant if AI changes how we shop?
That vertical B2B SaaS company you’re building? What happens if someone can vibe code a competitor next year?
These may sound like facetious questions, but I promise they’re not. We really don’t have any precedent for the adoption of AI. Which is why investors are piling into the relatively small number of companies whose founders can clearly articulate why they will be relevant in a post-AI world. And saying no to virtually everyone else.
It might not seem fair, but I think this is going to be the fundraising reality for the immediate future — at least until we have some more clarity around the rate at which AI and AI-driven technologies will permeate the broader market.
So if your company started out before the AI wave, you’re not building in deep tech, and/or you don’t have a convincing answer to the question, “why will this be relevant in 5 years?” then I’m afraid that VC (probably) isn’t right for you.
Things I Think I Think - Q1 2025
Can you write this post in the style of Studio Gibli? Here are 5 Things I Think I Think: Q1 2025.
It’s been a rollercoaster of a quarter on so many fronts. Let’s slow things down with another homage to legendary sports columnist Peter King.
Here are 5 Things I Think I Think - Q1 2025 Edition:
1. I Came in Like a Wrecking Ball
A lot of people thought they knew what was coming with the new administration, but the breadth and velocity of actions has impressed even the most seasoned political pundits.
I’ve said before that I have zero background in government or public policy, so I’m not going to try to unpack or opine on everything that’s going on. Rather, I’m going to share a few thoughts from the perspective of someone in venture:
The fundraising environment has, thus far, been completely immune to the day-to-day geopolitical drama (and, in fact, is very much on fire — more on that later). It remains an excellent time to raise if you’re a founder.
At this point, it’s fair to assume that tariffs of one form or another are here to stay. Plan accordingly.
Like many in tech, I was surprised by the recently-announced pardons for several startup founders convicted of fraud given the number of VCs in the administration’s inner circle. Hunter Walk has a good summary of why the right amount of fraud in Seed stage startups is greater than 0% but it shouldn’t be pardoned.
Speaking of VCs, I previously predicted that we would see a meaningful amount of vitriol directed at VCs as the new administration made move that were seen to have been influenced by the “VC arm” of the Republican party. With DOGE’s efforts mostly attributed to Elon Musk and talk of tariffs the primary economic topic, that hasn’t happened.
2. Fundraising is on 🔥
In my new year’s update, I predicted that the first half of 2025 would be hot from a fundraising perspective and wow…has it ever been!
Rounds are coming together with breathtaking speed. Virtually every founder I’ve worked with this quarter ended up in an oversubscribed scenario, with valuations at or above their target.
Some of this is stems from the entry of significant dry powder into the system that was sitting on the sidelines for the past couple of years. Some of this, undoubtedly, comes from the excitement surrounding all things AI.
Additionally, I think a not-insignificant part of the energy and enthusiasm in the ecosystem right now is due to the fact that we’re finally nearing the end of the washout of companies that raised too much during the ZIRP days. Investors are seeing more fast-growing, inspiring startups and fewer struggling companies in search of salvation, which is impacting their psychology.
In other words, investors are feeling more positive because their day-to-day experience is more positive.
Sound silly? A few years ago, I wrote about the impact that the adrenaline of deal flow has on investor behavior. When VCs see fewer deals or fewer companies that they perceive to be high quality, their rate of investment slows. What we’re seeing now is the inverse: investors are seeing a high rate of high-quality startups, which is keeping their level of enthusiasm — and thus, their willingness to invest — high.
It’s only been one quarter, but it’s feeling like we’ve finally moved back from glass half empty to glass half full on the fundraising front (at least, at the early stages — there remain a significant number of Series B and later companies in the danger zone).

As we head into Q2, I have two fundraising-related predictions:
When the final numbers are tallied up, I expect that Q1 2025 will have been the biggest startup fundraising quarter in North America in years (even without Open AI’s unprecedented $40B funding round).
Q2 will continue the momentum, although I won’t be entirely surprised if VCs start their summer slowdown a few weeks early. If you’re planning to raise before the summer, make sure you start before Memorial Day.
3. Elbows Up
In my Q4 update, I noted that the G7 countries were all falling behind the U.S. in terms of productivity and wondered aloud whether the tech communities in Canada, the UK, or any of the other countries would step up in the same way we were seeing in America. Talk of tariffs and trade wars in the early days of the new administration has since pushed a number of founders, investors and policy makers into action.
When the first round of tariffs was announced, I wrote about the unprecedented level of anger amongst Canadians. Canadians were (and still are) pissed. One outcome has been the Build Canada initiative, a coordinated effort from the tech and business community to promote a range of policy changes focused on increasing Canadian productivity in the lead-up to that country’s federal election.
We’re starting to see similar initiatives across the pond in Europe. For example, a group of prominent investors and founders including Harry Stebbings of 20VC and my former colleague Rina Onur Sirinoglu recently announced Project Europe, a new fund modeled after Peter Thiel’s famed Thiel Fellowship. But the urgency around Europe’s actions doesn’t yet seem as high as those in the Great White North (at least, not within the tech community). I suspect this has a lot to do with the fact that Canada is physically proximate to the U.S. and has a major federal election this month.
At a time when Canadian entrepreneurs on both side of the border are trying to make sense of what these changes mean for them, the coming weeks will tell us a lot about how influential Canada’s tech community really is.

4. San Francisco is Still the Place to Be
With so much of the tech news cycle focused on the impacts of tariffs and other actions from the new administration, it might not be as apparent to the outside world how fast San Francisco is moving right now. But it absolutely, unequivocally remains the place to be.
I was recently in San Francisco for YC Demo Day and the energy and activity dwarfed the prior demo day, which is notable as that was the first in-person demo day since Covid. The San Francisco Palace of Fine Arts was packed to the brim with investors and founders, and the buzz around AI and the emerging impact of vibe coding was palpable.

5. AI has its Studio Gibli Moment
I was going to end this post by sharing some thoughts on the emergence of vibe coding, but that was before Open AI released its latest image generation capabilities in an update to GPT‑4o. This past weekend, millions of people around the world rushed to reimagine their photos in the style of Studio Gibli.

While this viral trend might seem like nothing of particular significance, anyone who’s studied technology adoption knows the impact that moments like this can have.

According to Sam Altman, ChatGPT added more than a million users in a single hour on Monday. For context, it took 5 days to add that many users during the app’s viral launch. For many people around the world, the opportunity to “Gibli-fy” their images served as their introduction to AI.
I don’t think it’s an exaggeration to suggest that we’ll look back at this release as a turning point in the mainstream adoption of AI. Numerous technological waves have been driven by photo-related capabilities. It makes perfect sense to me that the opportunity to leverage AI in such a magical way would trigger the imaginations of the public-at-large. (Sorry, but AI’s killer app was never going to be “deep research”).
I’m not a consumer guy, but I can’t help but wonder if we’ll see a wave of AI-driven consumer apps catch fire in the coming months. Either way, it will be exciting to see how the adoption of these technologies changes as we transition into the “early majority” phase of the technology adoption lifecycle.