Chris Neumann
Investor | Founder | Advocate
Before You Start Fundraising, You Need to Get Acclimated
Founders trying to raise Seed or Series A funding from Silicon Valley VCs need to change their approach now.
Last week, I met with 4 different startups based outside of California: one from New York, another in London, a third in Vancouver and the fourth from Toronto. All of these startups are preparing to fundraise in the fall (either for their Seed or Series A round). At some point in each of those conversations, I found myself giving the founders a piece of advice that I hadn’t previously offered with any regularity:
“You should go to San Francisco a few weeks before you start to fundraise. You need to get acclimated.”
It wasn’t all that long ago that the majority of fundraising — even at later stages — was being done mostly online. For founders based outside of the U.S., raising from Silicon Valley VCs took a bit of extra prep work, but for the most part it didn’t matter if you were based in Brisbane, California or Brisbane, Australia. As recently as Q1, most Seed and Series A fundraising processes still began with virtual intro calls.
But over the past few quarters, things have shifted dramatically. Silicon Valley has been speeding up. A lot.
The first half of the year saw valuations for the top 5% of Seed rounds hit unprecedented highs, driven primarily by a surge in preemptive fundraising rounds. At the same time, the culture in Silicon Valley has been evolving to reflect its shift in velocity and intensity, manifesting in ways both big and small.
I hadn’t internalized just how prevalent these changes have been until I was on those calls last week. As I spoke with each of the founders, I found myself subconsciously (and not-so-subconsciously) noticing a variety of tells that made clear that they were not based in the Bay Area. An observation that my mind immediately translated to, “they’re not going fast enough.”
Considering that 2 of the 4 founding teams had previously spent considerable time in Silicon Valley, I was shocked at just how apparent it was to me that they were no longer locals. Some of it was language — there are a lot of new phrases that have entered the San Francisco lexicon as of late (the tongue-in-cheek website SF-isms catalogues some of them). But mostly it was their sense of urgency.
Or lack thereof.
I want to be clear that I’m not suggesting that any of these four startups aren’t operating at a high velocity — they all are — but Silicon Valley founders have upped their intensity and velocity to such a degree that everyone else seems slow by comparison. And in fundraising, just as in life, perception is reality.
Velocity has always been the metric that matters most when it comes to early-stage startups. And in today’s AI-driven landscape, Silicon Valley VCs are paying more attention than ever to how fast startups are going. Fundraising calls are happening in hours instead of days. Meetings are scheduled over text messages instead of through Calendly links. Everything in the ecosystem is happening faster.
Which brings us back to my fundraising advice.
It used to be relatively easy to prepare out-of-town founders for Silicon Valley fundraising by pointing them to a few key phrases, a list of what was “hot or not” in San Francisco at the time and a rubric of what Bay Area VCs would focus on for their stage. But it’s not so simple anymore. Right now many Seed and Series A VCs are struggling to adapt to the changing landscape, so there is no single list of what these investors are looking for to point at. Moreover, Silicon Valley itself is still accelerating.
Which makes it challenging to enumerate exactly what out-of-town founders should do in order to best prepare to pitch Silicon Valley VCs at this particular moment in time.
So I will instead share the advice I gave to each of the four founders I spoke to last week:
As you prepare your pitch for Silicon Valley VCs, reduce your level of confidence in feedback from hometown founders and investors (unless they have spent considerable time in the Bay Area recently and/or successfully fundraised from Silicon Valley VCs this year). In all likelihood, their advice is outdated.
Counterbalance this by proactively seeking feedback from founders, investors and others with strong current ties to Silicon Valley.
If at all possible, spend 2 - 3 weeks in San Francisco immediately prior to kicking off your fundraise. Doing so will:
Give you enough time to adjust and acclimate to the “new” pace and culture of Silicon Valley
Allow you to tap into the serendipity of Silicon Valley by attending events and meeting other founders
Provide an opportunity for you to solicit feedback on your pitch and fundraising strategy from Silicon Valley-based founders and investors
Expect to do most of your fundraising in person this time around
For founders outside of California who are trying to raise a Seed or Series A round from Silicon Valley VCs this year, I think this is likely to be the best approach given (a) the currently evolving nature of Silicon Valley, and (b) the widening gap in velocity/intensity/urgency between Silicon Valley and the rest of the world.
Note: the above advice is specifically geared towards founders trying to raise Seed or Series A rounds from Silicon Valley VCs. While Pre-Seed founders can certainly benefit from spending time in Silicon Valley, the vast majority of Pre-Seed rounds globally continue to be raised from local investors, so it may not impact your success rate when it comes to fundraising.
Should I Fundraise in the Summer?
If summer is a bad time to fundraise, why do so many VCs proclaim that they’re open for business?
It’s that time of year again.
We just hit the mid-point of Silicon Valley’s summer break and, right on cue, a plethora of VCs started proclaiming that they’re not actually on summer vacation.
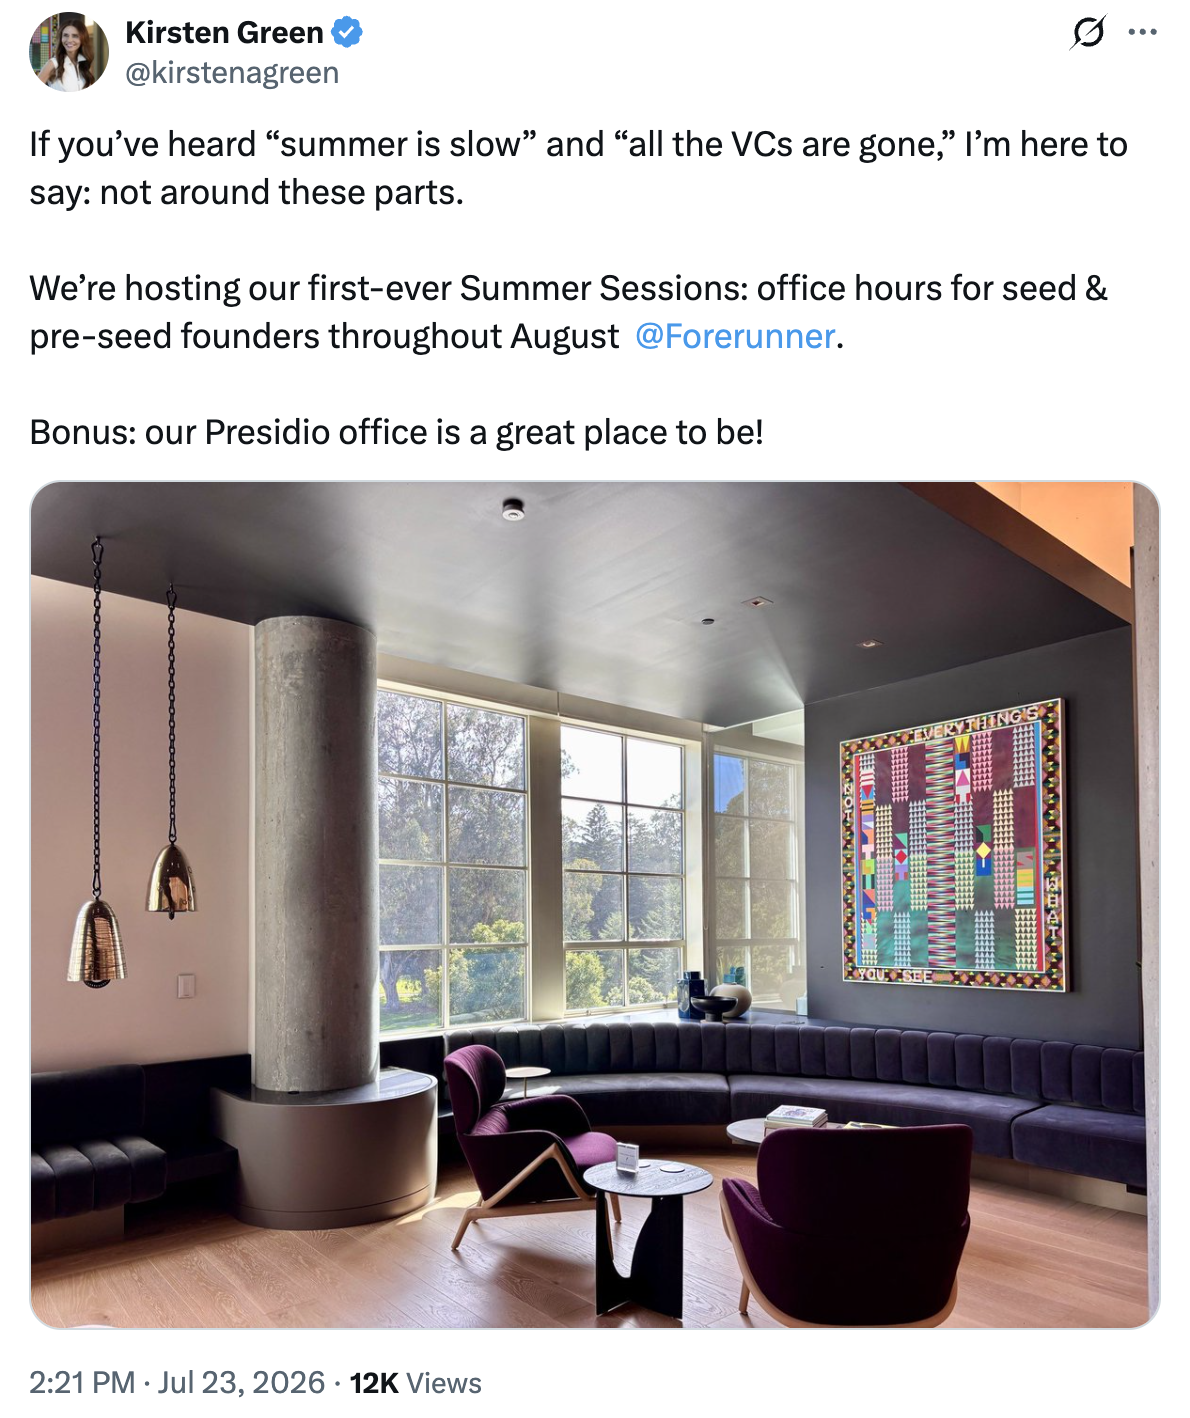
I’ve previously written about why summer is a bad time for founders to fundraise. If you haven’t read that post before, I suggest you start by giving it a quick skim. Here’s the tl;dr:
The vast majority of VCs do, in fact, work through the summer. But like everyone else, they do so at a reduced pace. They take summer vacations, spend more time with their kids, run around in the desert dressed up like fuzzy cyberpunk muppets. You know…normal summer stuff.
So it’s not that you can’t raise a round of funding in the summer. But it is logistically harder:
It takes longer to schedule initial meetings with a VC
The time between meetings increases
The amount of time needed for a VC to complete their diligence takes longer (as analysts and others at the firm also take vacations)
The result is that running a fundraising process in the summer takes longer than at other times of the year. Not only that, if you are able to successfully raise a round, you will very likely end up with a lower valuation due to the lack of competition.
But rather than revisit why summer is a bad time to fundraising from a founder’s perspective (seriously, read this post if you haven’t already), I thought I would share a bit of insight into why, each and every year, so many VCs try to push back against that narrative.
Let’s start with the basics: the goal of running a high-velocity fundraising process is to move as many investors as you possibly can through your funnel at roughly the same pace. The approach is designed to maximize the number of VCs that make it to the end of your funnel and finish their diligence process at in parallel. That point is critical because Econ 101 teaches us that competition for a scarce resource leads to increased prices. One VC willing to lead your round is great. But having multiple VCs reach the same conclusion at roughly the same time is what drives up price.
In other words, a strong company gets you a term sheet, but a strong process gets you a valuation.
A few years ago, I wrote about how VCs adjust their approach to investing during periods of reduced deal flow. This particular post was focused on the slowdown that happened post-ZIRP, but it pretty accurately describes how the psychology of investors changes during the summer:
“[During periods] of slow deal flow, VCs by-and-large disassociate themselves from any external pressure to do new deals…The result? A creeping inertia to not make investments…As inertia sets in, investors slow their deal pace. This can mean more meetings with each investor and — crucially — more time between meetings (as VCs no longer feel the time pressure to rush into a deal). The reduction in pace, combined with some VCs stopping making new investments altogether, makes it harder for founders to generate competitive dynamics when running a high-velocity fundraising process.”
Despite the inertia that creeps in during the summer, each year many VCs loudly proclaim that “they’re open” as a means to drive deal flow in a time of reduced competition. They’re hoping that you fundraise in the summer specifically because they know everyone else has that same inertia:
If they meet you in the summer and get really excited, they can likely ramp up their diligence efforts and reach a conclusion before you’ve booked a first meeting with many of their competitors
If they can get to a term sheet quick enough, they may be able to win the deal without having to compete on price or terms
If they’re interested but not enough to go fast, they still get an early look at your company and can slow play the process into the fall (giving them more data points to use in their decision while knowing that they likely won’t lose the deal)
Speaking of getting an early look, summer events is another well-worn approach that VCs use to get a sneak peak into companies that might be fundraising in the near future. Casual meetups and office hours (like those referenced by Forerunner at the start of this post) are one common tactic. Mini-conferences, founder bootcamps and other educational events is another.
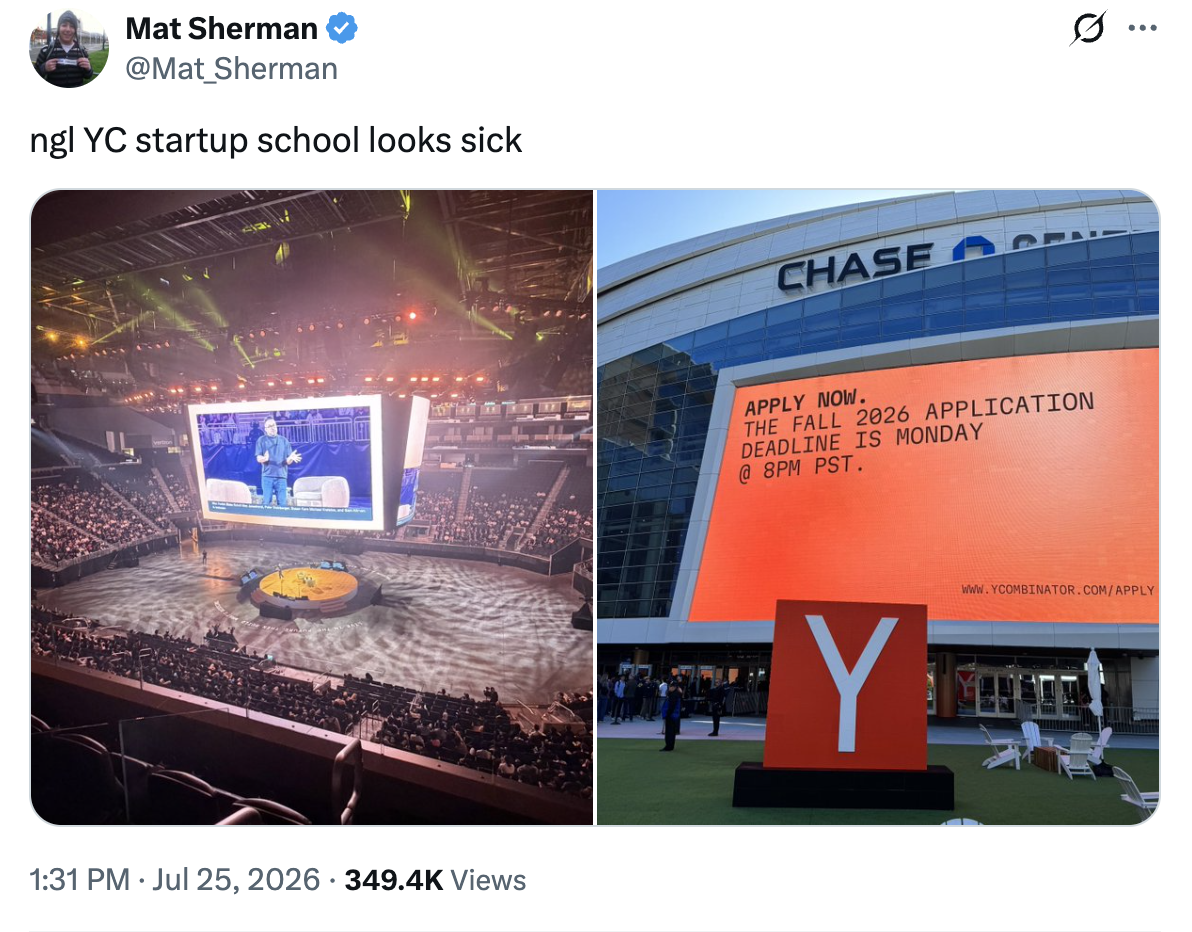
Why do you think YC makes such a big deal about Startup School each summer…? 😉
I Totally Missed Your Email
There’s a good chance many people you interact with these days are aware of when and how often you open their emails. Time to stop making excuses for why you took so long to respond.
Human etiquette is filled with performative interactions. Like all members of the animal kingdom, we have rituals around dating and mating, fighting and family. But unlike our wild friends, our etiquette has also evolved as a result of the changing nature of electronic communication.
“As per my previous email…”
Take the telephone, for example. It was invented way back in 1876 (150 years ago!), but it wasn’t until the 90s that we had a way to know who was calling before we answered. That’s right youngsters, back when I was a kid, you had to pick up the phone and say “hello?” in order to figure out if the caller was someone you wanted to speak with or a person you had desperately been trying to avoid.
(You also had to physically “pick up” the phone to answer it — none of this tapping or swiping or “Hey, Siri” nonsense…).
Once caller ID became mainstream, the etiquette and expectations around phone calls — especially missed calls — evolved. If you ran into someone whose phone calls you had been avoiding, you could no longer credibly claim that you didn’t know they had called. If you did, they immediately knew you were lying.
We’ve now officially reached that point with email — although a good chunk of the population still doesn’t realize it.
For most of the history of email, we didn’t actually know if the intended recipient opened an email that we sent. “Maybe it went to spam?” became the most common question asked when we didn’t get a response (and, by corollary, “It probably went to spam,” the go-to excuse when asked why we didn’t respond). Corporate email solutions, like Microsoft Exchange, have had the ability to track email opens (known as “read receipts”) for decades, but the functionality was mostly absent from mainstream email platforms.
That changed back in 2019, when an email startup named Superhuman added read receipt functionality to its client using tracking pixels (a concept that had been leveraged for years to deliver website analytics). Privacy advocates were in an uproar over the practice, but it wasn’t long before the backlash died down and other email clients began embedding similar capabilities into their products.
At this point, read receipts have been pretty widely available for more than 5 years, yet many people either don’t know they exist, forget that they exist, or delusionally believe that the person they’re interacting with isn’t using them.
I still regularly get email responses like this:
“I totally missed this email!
<response to the original email>
LMK and so sorry for being late.”
Meanwhile, the read history for the original email I sent looks like this:
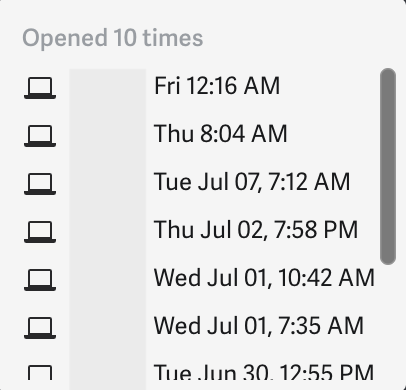
We’ve all done this before — reading and re-reading an email before deciding whether or not to respond — and it’s honestly not a big deal if we’re talking about emails between friends or work colleagues. But if you’re a resident of Startupland™ responding to an email from a potential investor, another founder, or someone else you’re trying to build a relationship with, you absolutely need to stop doing this.
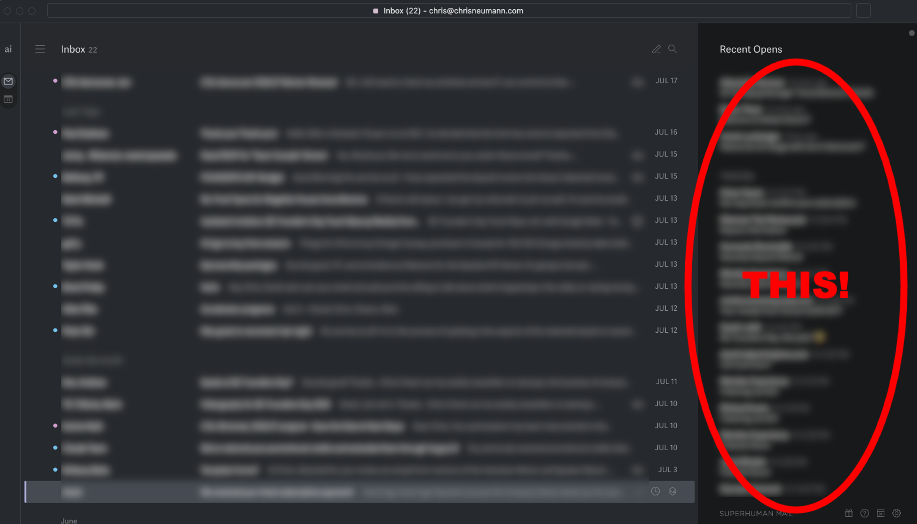
For starters, you should presume that the person who sent you the email has read receipts enabled. You should also presume that they might be keeping tabs on whether or not you opened it. Not because they’re weirdly obsessed with you, but because high-throughput email clients like Superhuman now put the open feed front and center:
And for those of you chuckling at this because your AI agent now takes care of all your emails, I promise that, “I didn’t see your email because my agent sucks at filtering,” isn’t going to buy you much credibility either.
In any case, there’s a good chance that many of the people you interact with these days are aware of how long it takes you to respond to their emails. Virtually every VC I know uses Superhuman. As do a significant percentage of founders in my network. Most of the time, your email response behavior isn’t going to make one iota of difference in your life. But if the person you’re responding to is in the process of evaluating you (such as an investor deciding whether or not to back your startup or someone in a position of influence trying to gauge if you respect their time), you might want to rethink how you handle email.
If an email takes less than a minute to respond to, just do it (this has been best practice for a long time, yet many of us still don’t)
If a request is going to take time for you to complete, send a quick note of acknowledgement to show your responsiveness
And most importantly, stop sending emails claiming that “I just saw this” after opening and closing it for weeks
Even if you’re not at the point where you’re willing to trust an agent to fully manage your inbox, with AI now embedded into virtually every email client, there really isn’t a credible reason to let your backlog build up. Let the AI auto-generate quick responses for you and either tweak them or quickly hit send.
More than ever, velocity is the one metric that matters most. And for better or worse, email read receipts now provide a measurable indication of your velocity and how you prioritize things.
Reply quickly or be honest when you don’t. Your reputation will thank me later.
The Cost of Hubris
Founder hubris can be deadly for startups. Here's how to identify it early and avoid its consequences.
A few weeks into my first batch as an EIR at 500 Startups, we held a week-long series of talks about fundraising. In those days, fundraising best practices weren’t as widely known as they are today, so the topics we covered were new to virtually all of the founders participating in the program.
Towards the end of the week, I was chatting with Marvin Liao — head of the firm’s flagship accelerator — when one of the founders approached us to discuss his fundraising process. This particular founder was one of the strongest in the batch. He had bootstrapped his company to an impressive amount of revenue, enough so that he should have been able to easily raise a competitive Seed round. But there was a catch.
Despite being part of a mentorship-based accelerator, this particular founder had zero interest in listening to anyone’s advice.
On that particular day, this founder came towards us not to ask questions, but to vent. You see, he had just returned from Sand Hill Road after pitching a top tier VC — his dream investor — and, suffice to say, it did not go well.
Why not? For starters, this founder hadn’t spent any time preparing his fundraising pitch. He hadn’t worked on it, refined it or practiced it. Not once.
Despite an entire week of programming about fundraising, and despite partner-after-partner-after-partner urging him to hold off on meeting with any VCs until he was ready, this founder decided that he knew better then everyone else and sauntered into the offices of [redacted] without so much as a slide.
And he totally, completely, unequivocally sh*t the bed.
It was so bad that the partner he met with at the tier one VC texted Marvin immediately after the meeting to ask, “What the hell was that dumpster fire?”

Watching this founder recount the experience to us was like watching a car wreck in slow motion. His reflection on what went wrong (or, more precisely, his complete lack of self-reflection) was astonishing to me. The entire conversation consisted of him complaining about how clueless the VC was, without so much of a inkling of recognition that he might have gone in unprepared.
When he eventually finished venting and walked away, I stood there with what must have looked like an utterly gobsmacked look on my face. Marvin turned towards me, smiled, and whispered,
“There’s always one.”
After the founder left, I asked him to explain.
“There’s always one,” Marvin continued. “One founder who thinks they’re special. One founder who thinks the rules don’t apply to them. One founder who thinks they know better than everyone else.”
“Every. Single. Batch.”
As my tenure at 500 Startups continued, I was astonished by the accuracy of Marvin’s observation. Every single batch, there was a founder who did this. A founder who took the accelerator’s investment, accepted a place in the batch, and immediately upon arrival decided that they needed none of the advice or education the program had to offer.
Hubris is a funny thing. You have to have a certain amount of hubris to start a company to begin with — entrepreneurship demands the audacious belief that you can create something out of nothing — but the line between confidence and cockiness is a thin one. And landing on the wrong side of it can have a detrimental impact on the trajectory of your company. Whether you realize it or not.
In the 10+ years since that first encounter, I’ve seen similar stories play out time and time again. Oftentimes when founders fall victim to hubris, the results are fatal to their startups. Those that do manage to survive frequently end up so far off course that the company never comes close to reaching its full potential.
I’ve observed some patterns when it comes to founder hubris and wanted to share them in the hope that I can help you to avoid its trap. Here are some common themes I’ve seen over the years:
Early Success
I’ve found that disproportionate hubris is often present in founders who achieved uncommon early success and/or hit significant milestones on their first try. Examples include:
Unusually strong early user or revenue growth
Unexpected virality or marketing notoriety
An unusually easy first fundraise
Founders who achieve such quick wins without realizing how unusual they are often attribute their early success to skill rather than other factors (such as luck, preexisting connections or just good timing). The result is frequently a form of complacency — sort of like when you ace the first few quizzes in a class, get used to how easy it is, and presume you don’t have to study for subsequent ones.
Charisma
In my experience, there is a strong correlation between a founder’s charisma and the likelihood that they develop hubris early in their journey. This is especially pronounced when they have an easy time raising their first round of funding.
In most cases, the initial round of funding (angel and/or Pre-Seed) is driven by narrative. Many founders with strong charisma have an easier time raising their first round specifically because of their storytelling and persuasive abilities. Where things can go sideways is in subsequent funding rounds, when investment decisions are driven more by analysis of early traction, unit economics and so on. I’ve seen many founders who breezed through their Pre-Seed round run full speed into a brick wall when raising subsequent rounds specifically due to a lack of preparation caused by hubris. Moreover, many such founders vastly overestimate the degree to which they can overcome weaknesses in their pitch and/or business with their charisma.
Small Town Founders
This might seem paradoxical, but I’ve found that early hubris is more common in founders who come from outside of Silicon Valley than in founders based in the Bay Area. For as confident and cocky as some Silicon Valley founders come across, they tend to be very well informed about the competitive landscape and the expectations of both customers and investors. Founders from smaller cities — especially ones who get early wins — are often disproportionately lifted up by their ecosystem and can unknowingly end up with big-fish-in-small-pond syndrome before achieving any actual success.
Many years ago, I was introduced to a promising young founder from a small ecosystem whose SaaS startup had surpassed $1M ARR in their first year (this was well before the rise of AI, when doing so was really, really hard). In discussing their early traction, it was immediately obvious to me that the company had a leaky bucket caused by an incredibly high churn rate. Although top-line revenue was growing, it was driven by unsustainable marketing spend. I tried my best to encourage this founder to address the company’s churn rate and its unit economics before approaching Silicon Valley Seed VCs (as they would immediately dig into whether or not the revenue was “real”), but she would hear none of it. Bolstered by local cheerleaders, startup awards and fawning media coverage, she went out and spent nearly 9 months trying to raise a Seed round. Despite countless VCs giving her nearly-identical feedback, she was unwilling (or unable) to change course. The fundraise ultimately failed and the once promising company was acqui-hired shortly thereafter.
Solo Founders
Solo founders are particularly prone to falling victim to hubris because they often don’t have voices around them to provide critical feedback and who they are willing to listen to. I’ve seen many solo founders over the years who simply ignored feedback from employees, advisors and even investors if it didn’t reinforce their preconceived views. When hubris raises its ugly head, it’s almost impossible for someone new to pierce the veil. In contrast, a trusted cofounder can often break through all but the most stubborn cases of intransigence.
One last point before I close — in Silicon Valley, hubris doesn’t just prevent you from hearing helpful advice or critical feedback. It can close doors that you never realized were open. Pay-it-forward culture is a very real thing. But an important corollary is that in an ecosystem filled with people who genuinely want to help, immediately rejecting advice or feedback that doesn’t reinforce your previously-held beliefs sticks out like a sore thumb.
If you read my post from a few weeks ago on snakes and ladders, what I’m talking about here is access to ladders. Many of the people trying to help you can also point you to a ladder, but whether or not they do so will depend on how you react. You don’t have to agree with everyone who offers advice or opinions (in fact, you most certainly shouldn’t). But you should at least listen to what they have to say. Otherwise, you will likely never know what other help they might have been willing to offer.
Instead of pointing you towards a ladder, those individuals will simply redirect their time and efforts towards one of the thousands of other founders hungry for their help.
When it comes to startups, the cost of founder hubris is high. And over time, it also compounds.
What If You Fire Them?
What happens when a VC likes the CEO, but doesn’t have conviction about the rest of the founding team?
This past week, Startupland™’s corner of social media was abuzz after podcaster Greg Isenberg posted a “horror story” from his days as a founder. As the week wore on, founders around the world quote-tweeted the original post with their own tales of VC misbehavior (yes, I’m still calling it a “quote-tweet”). Things took a sharp turn Friday morning, when Cloudflare CEO and Cofounder Matthew Prince shared some of his own experiences.
…and named names.
The third anecdote he shared — about Midas List investor Vinod Khosla — set the internet ablaze.
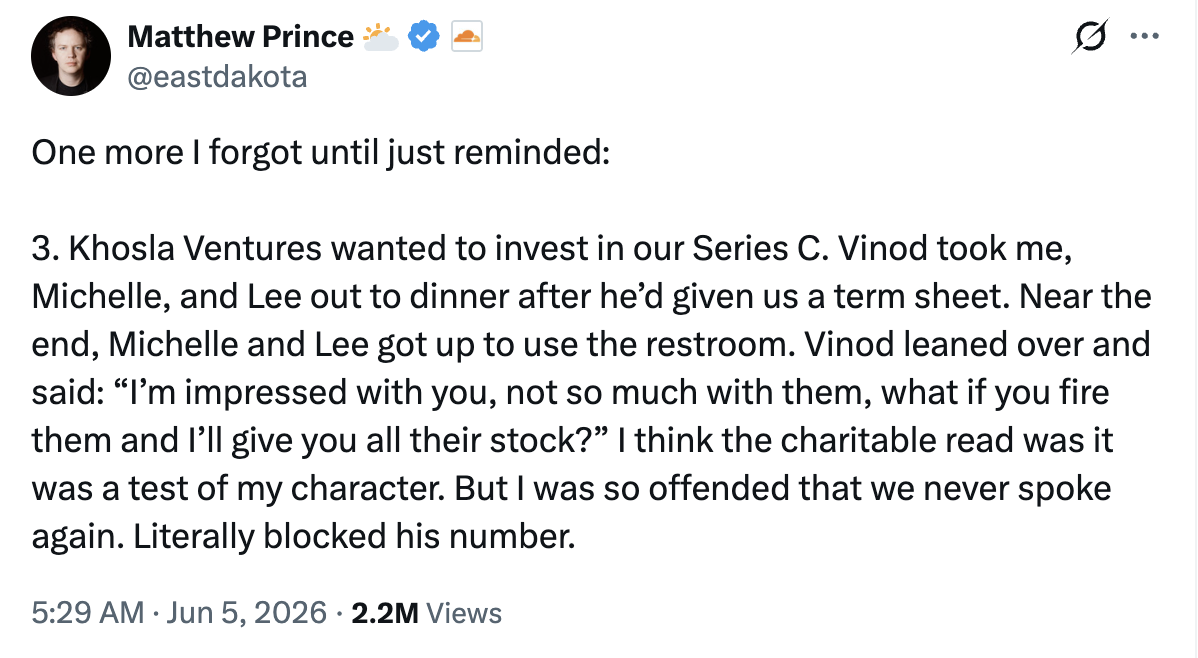
Rather than dive into the particulars of Matthew’s experience (which plenty of netizens have already done), I want to explore a topic that we don’t often talk about when it comes to startups and fundraising: what happens when a VC likes the CEO, but doesn’t have conviction about the rest of the founding team?
When it comes to fundraising and fundraising advice, we frequently talk about founders as a single unit. We refer to the characteristics of the “founding team” and write blog posts (like this one) about frameworks that VCs use to evaluate them. But the reality is that not all founders are equal in the eyes of prospective investors.
There is the CEO, and then there is everyone else.
Now, before you rush to pitchforks, it’s important to understand that there’s logic to this thinking. For starters, the CEO is (in theory at least), the person who is ultimately responsible for all decisions. The buck stops with them. Moreover, there’s a reasonable likelihood that at least one of the cofounders pitching the VC will be gone within a few years. A recent Carta report looked at more than 22,000 VC-backed companies with 2-3 cofounders. More than 25% of them had at least one cofounder leave by year 4:
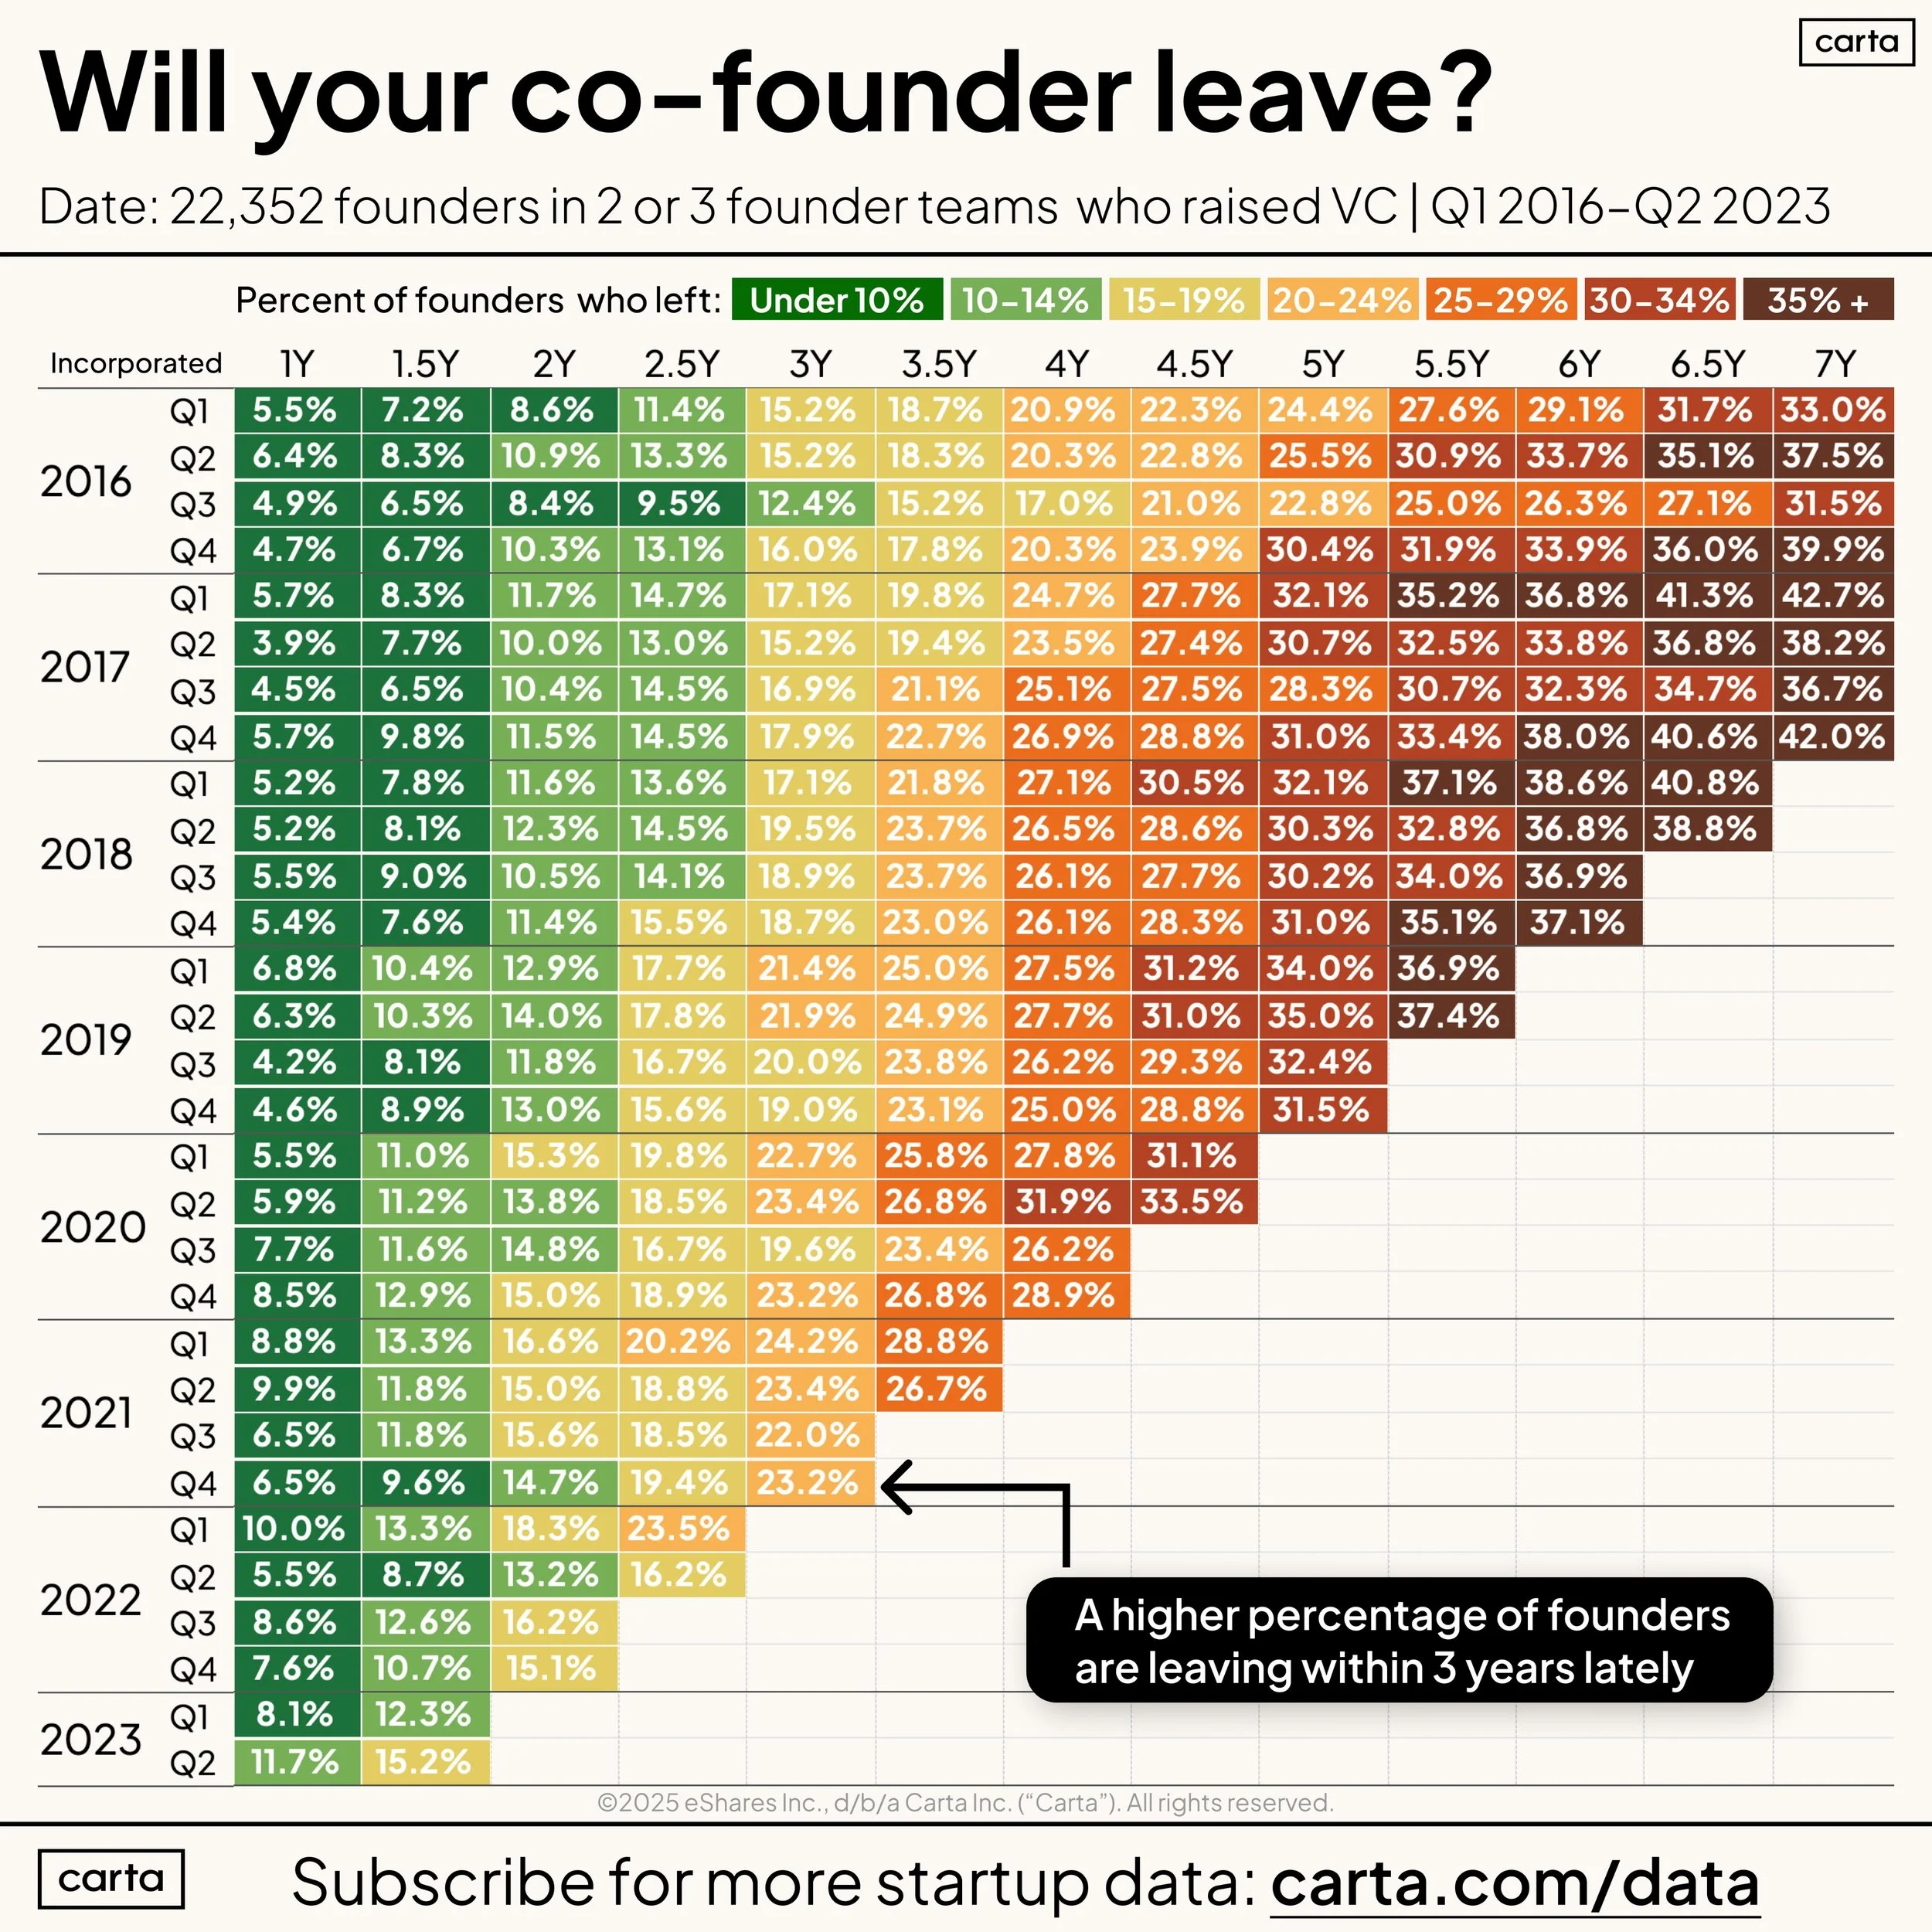
The two VC-backed companies that I was a part of — Aster Data, where I was the first employee, and DataHero, where I was the CEO — both had a cofounder leave by year 4. And many of the companies that I’ve invested in over the years have had one or more cofounders leave relatively early on.
There are wide variety of reasons why a cofounder may leave a startup, but there are several situations that occur frequently enough that VCs actively watch for them during fundraising meetings:
Interpersonal conflicts between cofounders
Lack of alignment (particularly to the company’s mission and values)
Inability to take feedback / have their assumptions challenged
Lack of growth mindset (this one is more difficult to interview for, but what investors are keeping an eye out for are signals that a cofounder might not be willing or able to evolve fast enough to keep pace with the rest of the company)
More often than not, if a prospective investors sees signs of one or more of the situations listed above, they will simply pass on the opportunity. But there is one case where some VCs will take a deeper look despite the warning signs: when they are excited about the CEO but are less infatuated with one or more of the cofounders.
Over the years, I’ve had this happen to me a number of times. After meeting an impressive CEO with an ambitious vision, strong background and clear founder-market fit, I met their cofounders and…

Believe it or not, it’s actually quite unusual to meet a founding team made up of individuals who aren’t at the same level as each other. Most high-achieving people (particularly CEOs) surround themselves by other, similarly-impressive individuals. On those rare occasions when I’m introduced to cofounders that come off as a significant step down from the CEO, it’s actually rather jarring.
My first question in such a situation is always, “did I get it wrong?” I’ll usually try to diligence the cofounder quickly (often by leveraging backchannel references) in order to figure out if my initial read was incorrect. If my suspicions are confirmed, the next question I need to answer is, “is the CEO aware that their cofounder…isn’t strong?”
Before I go any further, I want to acknowledge that this entire topic is very subjective. What I consider to be “strong” and what other people consider to be “strong” can vary wildly (which is why it’s so important when fundraising to fill your fundraising funnel with a large set of potential investors). The reality is that VC investing is far more art than science — particularly at the early stages. So while it might feel uncomfortable to think that investors are picking apart your founding team like this, understanding what’s happening (and why) can make a big difference in your outcome.
I should also point out that the stage of a company plays a big part in the ramifications of an underperforming cofounder. It is generally challenging to replace a cofounder at the early stages. On the other hand, at later stages (e.g. Series C) it’s not uncommon to see cofounders moved into different roles as experienced executives are brought in to lead specific functions. For the remainder of this post, I’ll focus on ridiculously early startups — where I spend most of my time.
In my experience, a significant “competency mismatch” between a CEO and another cofounder at the early stages usually falls into one of three categories:
The CEO is aware of the mismatch and has nonetheless chosen to cofound a company with this individual
The CEO is subconsciously aware of the mismatch but is hoping they are wrong
The CEO is completely oblivious to the mismatch
Let’s look at each of these scenarios:
1. The CEO is aware of the mismatch and has nonetheless chosen to cofound a company with this individual
In some cases, a strong CEO will intentionally choose to include one or more less experienced individuals as part of the founding team. For example, a senior CEO might have junior cofounders filling independent contributor roles, knowing that they will likely have to hire leadership “above them” at some point. Provided that there is transparency around this, it can be a healthy long-term situation (I’ve invested in several companies with this dynamic).
That said, a founding team with an intentionally large competency gap between the CEO and other cofounders can also be a strong negative signal. For example, it might indicate that the CEO isn’t comfortable managing people who are at or above their level or that they are unable to recruit strong cofounders. Both situations imply dynamics that are almost always fatal to a company, which is why experienced VCs will avoid such startups at all costs.
2. The CEO is subconsciously aware of the mismatch but is hoping they are wrong
In this situation, the CEO has a gut feeling that their cofounder might not be up to the task, but goes along with it anyways. In my experience, this mostly happens with first-time founders who haven’t previously dealt with the ramifications of an underperforming cofounder.
3. The CEO is completely oblivious to the mismatch
A great engineer will rarely cofound a company with a mediocre engineer. Similarly, an exceptional business cofounder will rarely cofound a company with salesperson or marketer who is mid. But what happens when cofounders have completely different backgrounds?
I’ve met multiple companies over the years that had an exceptional technical CEO but a goofball “business cofounder”. I’ve also met founding CEOs with incredible business backgrounds who didn’t realize that their technical cofounder was a dud.
So how do VCs deal with situations like the ones described above?
While I’ve never told a founder outright that they should fire their cofounders, I’ve have shared cofounder-related feedback with a handful of CEOs over the years. Many VCs are reticent to give feedback, but every once in awhile we meet a CEO who’s both objectively impressive and seems open to “out-of-the-box” feedback. In cases where I sense that the CEO either doesn’t realize the competency mismatch or perhaps does, but doesn’t want to admit it, I will occasionally offer feedback on their cofounders.
I only ever do this 1×1 and always verbally (either in person or on a call). But unlike the situation described by Matthew above, it’s never been as part of an offer to invest. Rather, it’s always been a follow-on conversation after deciding to pass on the company.
At the end of the day, the situation described by Matthew is an unusual one. But Vinod’s experience — of meeting a CEO that he was excited by but cofounders that he found to be less impressive — happens a lot more than you probably realize.
If you sense something that something’s off after a VC meets your cofounders, consider asking them about it. Here’s a great question to try:
“After meeting my cofounders, are you more or less likely to want to invest. Why?”
Regardless of the the outcome, you’ll learn something new.
What’s Going On With Accelerators?
With more accelerators and fellowships than ever, it might seem like there’s an overabundance of options for founders to choose from. What we’re seeing is actually a clustering around two very specific approaches to hands-on investing.
I’ve written a lot lately about the ongoing bifurcation of venture capital and its implications for fundraising (both in my quarterly updates and in dedicated posts, like this one on early-stage investing).
One prediction I made last year was that we would start to see more early-stage investors lean in to the “hands-on” styles of investing that were more common in years past. As megafunds ramped up their early-stage activity, many Seed VCs would be crowded out. They would in turn head upstream to the “safety” of Pre-Seed. The increased competition at Pre-Seed would force investors to find new ways to differentiate themselves in the eyes of both founders and LPs.
And that would lead to more accelerators,
“…we’re seeing a resurgence of both small, dedicated accelerators and offerings from Seed-specialist VCs…it feels like the pendulum is swinging solidly back from the “hands-off” investing style of the ZIRP era to the more “hands-on” style of years past. At a time when AI is making it cheaper than ever to get a company off the ground, I think we’re going to quickly see a new level of competition amongst credible accelerators (and between accelerators and pre-seed VCs).”
Sure enough, the accelerator landscape has gotten a lot more crowded since I wrote that post.
Since the beginning of the year, megafund a16z significantly ramped up their speedrun team (I might have done reference calls for some people they were looking to hire 👀). They followed that up by launching a new fellowship program called “alpha” a few weeks ago.
Speaking of alpha, the big dog of accelerators, YC, didn’t sit long with its earlier assertion that, “…the total number of startups going through the program each year will hold steady at about 500…” The recently completed W26 batch had nearly 200 companies (i.e. they’re currently on pace to invest in 800 startups in 2026).
And that’s just the start. Here is some of the other activity that took place across the accelerator landscape during the first quarter of 2026:
London-founded fellowship program Entrepreneurs First completed its move to San Francisco and unveiled a fresh $200M fund
Accelerator upstart Neo announced a new Residency program for college students
Montreal-based AI research institute Mila launched a new venture-building program for AI research scientists as part of a $100M “venture scientist fund” announced earlier in the year
South Park Commons shared its plans to raise a new $500M fund for its self-proclaimed “anti-accelerator”
Taken together, it might seem like there’s now an overabundance of programs for founders to choose from. But if you look closer, what we’re seeing is actually a clustering around two very specific approaches to hands-on investing:
Accelerators as the New MBA
Fellowships as the New Montessori
Let’s dig deeper into each of these trends.
Accelerators as the New MBA
In the early days of accelerators, programs like YC, Techstars and 500 Startups didn’t have nearly the prestige of today’s industry leaders. In fact, it was quite the opposite. Amongst many founders and investors in the startup world, accelerators were seen as something of a crutch. They were the thing you went to if you couldn’t figure it out on your own.
Fast-forward 20 years and the perception is very different. Not only are accelerators broadly accepted as a reasonable path for first-time founders to take, but having simply attended a top accelerator is seen by many as a mark of credibility and prestige. Sound familiar?
“You got into Harvard…you must be smart!”
“You got into YC…you must be smart!”
Last year, David Crow wrote about the increasing similarities between top accelerators and universities. He noted that,
“In the past, ambitious graduates invested in themselves by going to grad school. They spent $100,000 on an MBA, law degree, or medical program as their path to impact.
Today, ambitious people might choose YC or Speedrun instead…
YC and Speedrun are not just accelerators; they’re the new professional schools of venture.”
I’ll take it a step further: not only are ambitious individuals increasingly looking at top accelerators as a credible path to advance their careers, accelerators are increasingly selecting founders in ways that look a lot like how elite MBAs choose students.
And I’m not the only one.
I recently caught up with a friend who spent many years as a VC at one of Silicon Valley’s top-tier funds (he also happens to have an MBA from a prominent business school). In discussing the evolution of the early-stage landscape, he suggested that top accelerators have very intentionally moved towards a model for selecting founders that mirrors how top MBA programs select students:
“At this point, [top accelerators] know the “shape” of founders that Tier 1 VCs like to invest in. The schools they went to, the companies on their resume, the traction points that matter. The things that get an IC* comfortable investing in a company that maybe hasn’t done anything yet.
It’s the same way MBA programs cater to top employers. What undergrad did the student go to? Where did they intern? What test scores do they need if they came from a lesser-known school? They’re trying to maximize the chances that an incoming student will land a job with a name brand employer, regardless of what they actually do during business school.”
* investment committee
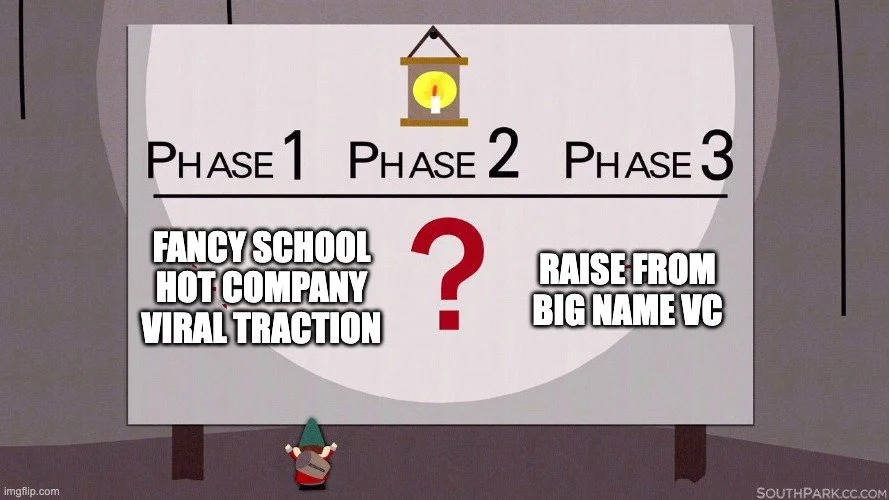
If you read my recent post on Hunters vs. Farmers, you might be getting a sense of deja vu. That’s because what we’re talking about here is the approach that “hunters” typically take, but within the context of a segment of venture that we historically think of as “farmers”:
“Early-stage hunters focus on pedigree and traction as their primary signals. Things like:
Graduating from a top school or program (Stanford, MIT, Waterloo, IIT Bombay, Thiel Fellowship, etc.)
Early employees that left “hot” companies
Repeat founders
Hot sectors
Virality / significant early traction
They’re generally betting on the correlation between pedigree and outcome (or, at least, pedigree and quick markups).”
This is exactly what elite MBA programs do. They bet on the correlation between pedigree and outcome, where outcome is “gets hired by a top-tier employer”. Today’s top accelerators are increasingly converging on a similar model. And you can see it in their marketing,
“Want to maximize your chances of landing a job with [top employer]? Apply to Harvard!”
“Want to maximize your chances of raising a round from [top VC]? Apply to YC!”
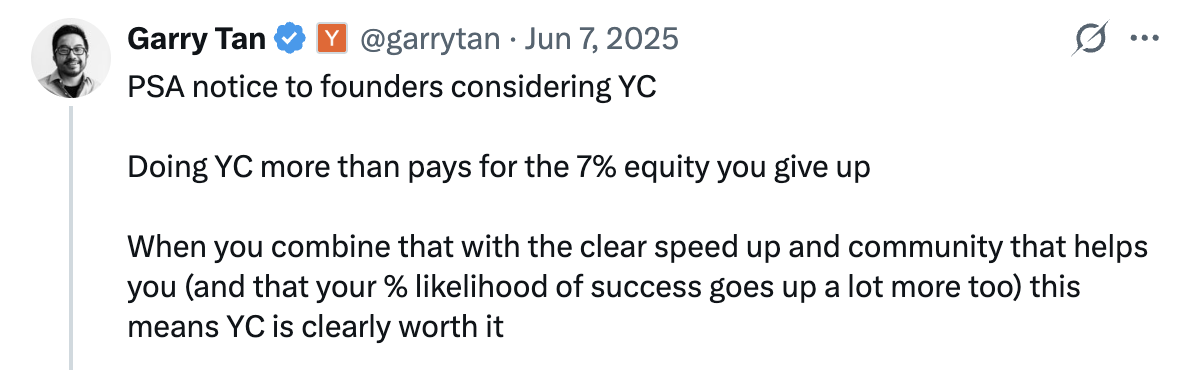
This certainly isn’t a bad approach — for either the accelerators or the founders.
That said, it’s worth noting that what’s happening at the top of the accelerator pyramid right now is very much influenced by a considerable imbalance in supply and demand. More and more qualified founders are looking for the “cheat codes” that come with the brand recognition and alumni networks of top accelerators. Yet there are very few programs that credibly deliver consistent outcomes along these dimensions (particularly in the aftermath of 500 Startups and Techstars both effectively failing). With so many qualified startups and so few spaces available in each program, founder pedigree naturally becomes a more prominent factor in selection.
Which means that a significant number of ambitious founders — especially founders outside of California and those from schools, companies and backgrounds that don’t neatly fit the typical Silicon Valley mold — are struggling to gain acceptance into these elite programs.
When the supply-demand curve is so imbalanced that an entire country doesn’t make the cut
So why aren’t we seeing more “elite MBA programs” emerge if the supply-demand curve is so imbalanced?
Despite the incredible demand for top tier Silicon Valley-based accelerators, only two platforms founded in the past decade have found success: Neo starting in 2017 and speedrun (from a16z) in 2023.
It turns out that creating a full-fledged accelerator platform from scratch is hard. It takes a lot of resources, investors who are experienced evaluating startups with virtually no traction, and an incredible number of high-quality, properly incentivized mentors. Creating a high-quality accelerator is, in fact, really, really hard.
But it is doable. Not only that, with so much latent opportunity — especially when it comes to startups outside of California — more elite Silicon Valley-based platforms are undoubtedly going to emerge. It’s just a question of when.
In the meantime, the majority of early-stage investors that have started rolling up their sleeves are taking a different approach. One that focuses almost entirely on the potential of individual founders while forgoing much of the complexity of a full-blown accelerator…
Fellowships as the New Montessori
If accelerators like YC and speedrun are the new MBA, then fellowship programs like South Park Commons, HF0 and Entepreneurs First are the new Montessori school.
If you’re unfamiliar with the term “Montessori”, it is an approach to early childhood education that focuses on encouraging children’s natural interests rather than providing formal, structured education. Montessori programs are designed around student-directed work, with a particular emphasis on uninterrupted work periods. The approach is based on the idea that children are naturally eager for knowledge and the primary role of teachers is to guide and mentor them.
At a high level, Montessori schools take a group of highly-motivated individuals and place them in a room with a handful of experienced, light-touch mentors in the hope of creating magic.
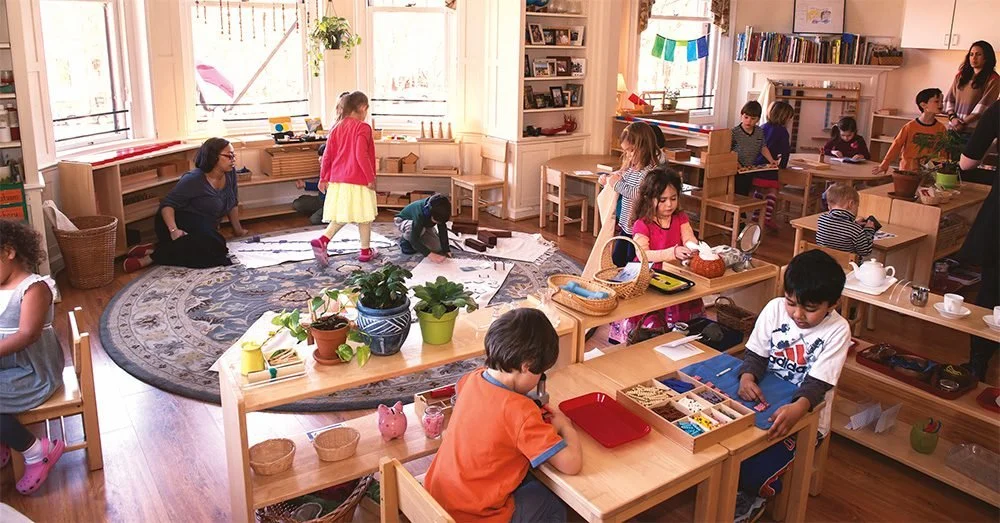
A Montessori “hacker house”
Which brings us to fellowships.
Fellowship programs invest in aspiring founders based primarily on their experience and pedigrees. These individuals are placed into a cohort and participate in activities designed to guide them towards founding high-potential companies (with a particular emphasis on ideation and cofounder matching). In other words, they take a group of highly-motivated individuals and place them in a room with a handful of experienced, light-touch mentors in the hope of creating magic.
Over the past few years, the number of fellowship programs has exploded. Not only are there an increasing number of standalone platforms (like South Park Commons, HF0 and Entepreneurs First), but many existing VCs have launched fellowship offerings as a means to increase their access to high-potential founders at the earliest stages. Some examples include a16z’s “alpha” fellowship (mentioned above), Conviction Partners’ “Embed” program, and Afore Capital’s “Founder in Residency” program.
Earlier, I alluded to the fact that fellowship programs forgo much of the complexity of a full-blown accelerator. Let me expand on that point — as it’s key to understanding why so many fellowship programs are emerging.
Both fellowship programs and Montessori schools are rooted in the notion that individual participants are highly-motivated and eager for knowledge. The corollary of that belief is that mentors need not be heavy-handed (either in their depth of programming or the help they provide). Montessori programs don’t so much teach children as they guide them on where to look for their own answers. Similarly, fellowship programs don’t focus on the type of “startup 101” programming that accelerators historically delivered. Instead, they provide frameworks for aspiring founders to search for answers while making introductions and connections to help them progress.
Guess what? That approach means fewer mentors, less time and effort developing programming, and significantly lower costs.
The simplest form of a fellowship offering is a VC partner providing regular mentorship and occasional connections to an aspiring founder. Which is exactly what many VCs have done for years through entrepreneur-in-residence (EIR) programs. From the perspective of traditional VCs, fellowship programs are little more than the cohort-ization (is that a word?) of something they were already doing.
Want to have your mind blown even further? Y Combinator — the world’s foremost accelerator — actually started out more like a fellowship program. Here is how Paul Graham originally described YC (then referred to as the “Summer Founders Program”):
The Summer Founders Program preserves many features of a conventional summer job. You have to move here (Cambridge) for the summer, as with a regular summer job. We give you enough money to live on for a summer, as with a regular summer job. You get to work on real problems, as you would in a good summer job. But instead of working for an existing company, you'll be working for your own; instead showing up at some office building at 9 AM, you can work when and where you like; and instead of salary, the money you get will be seed funding.
…
We'll have some smart people who are willing to talk over your plans with you, and suggest pitfalls and new ideas. We may also have connections to companies you'd like to do deals with. But how much you want to take advantage of our advice and connections is up to you.
We'll organize dinner once a week for all the Summer Founders, so you can meet one another and compare notes. We'll try to get some expert in technology, business, or law to speak at each dinner. But beyond that we'll be hands-off.

The first batch of YC’s “fellowship program”
To be clear, today’s top-tier fellowship programs provide significantly more that just a la carte mentoring and connections. They are full-blown platforms with programming and mentorship strategies that have been developed and iterated over many years. But the low “entry price” of starting a basic fellowship program, combined with the dramatic supply and demand imbalance I alluded to earlier (more and more founders looking for “cheat codes” but relatively few credible accelerators), is driving what I believe to be just the start of a wave of new fellowship offerings.
To recap:
The bifurcation of venture capital is forcing many VCs to invest earlier-and-earlier
Increased competition at the Pre-Seed stage is driving those investors to find new ways to differentiate themselves — which, for many, involves getting more hands-on with founders
Creating a new accelerator is difficult and prohibitively expensive for most VCs (a16z can afford to throw a ton of money at creating a new accelerator, but the funds who are moving upstream specifically because they can’t afford to compete against a16z most certainly cannot)
However, “systematizing” mentorship and/or scaling an existing EIR program is much more approachable for most VCs (and easy to justify from an ROI standpoint)
Bottom line: expect to see more and more fellowship programs emerge in the coming months (particularly from mid-sized Seed funds that are trying to figure out how to effectively compete at Pre-Seed).
On Terms and Terminology
Before I wrap things up, I want to share two final thoughts on terms and terminology:
On Terms
Many accelerators and fellowships are increasingly trumpeting large numbers when it comes to their investment amount. It’s not uncommon to see programs seemingly offering $1M of investment to startups.
But don’t believe everything you read.
The vast majority of accelerators and fellowships make either milestone-based or follow-on based investments. That means that (a) you might not receive the full amount, and (b) if you do, you may end up giving away a much higher portion of your company than you realized.
Consider the following examples:
Y Combinator
Top-line number: $500K
Actual initial investment: $125K for 7%
Follow-on investment: $375K (MFN)
a16z Speedrun
Top-line number: $1M
Actual initial investment: $500K for 10%
Follow-on investment: $500K (contingent on follow-on funding)
Entrepreneurs First (US)
Top-line number: $250K
Actual initial investment: $125K for 8%
Follow-on investment: $125K (MFN)
South Park Commons
Top-line number: $1M
Actual initial investment: $400K for 7%
Follow-on investment: $600K (contingent on follow-on funding)
Strictly speaking, there’s nothing wrong with this approach (in fact, it very much represents a standardization of the traditional venture capital strategy of “investing early and doubling down on winners”). But as a founder, it’s important that you read the fine print (here is a somewhat dated post on accelerator terms that I wrote a few years ago).
On Terminology
I’m not going dive into the etymology of (or debate over) terms related to accelerators / incubators / startup schools / etc., but I do think it’s important to share one point as it relates to fellowships (as they’re relatively new on the startup landscape and the language is still in flux):
The term “residency” is often used interchangeably with “fellowship” (e.g. Neo refers to its fellowship program as “Neo Residency”). However, it is also increasingly being used to differentiate between full-blown fellowship programs and lighter-touch coworking offerings that standalone fellowship programs are using to attract potential candidates (e.g. the Entrepreneurs First Residency and the South Park Commons Residency).
If you are considering a fellowship program, be sure to pay attention to the terminology and make sure you understand exactly what you’re applying to (lest you mistake one for the other).

What’s Going on with Seed Rounds?
Another major shift is underway and, this time, it’s throwing off founders, angel investors, and Pre-Seed VCs alike.
As we near the end of the first quarter of 2026, yet another major shift is underway in the funding / fundraising landscape. And this time, it’s throwing off founders, angel investors, and Pre-Seed VCs alike:
Seed VCs are increasingly not acting like Seed VCs.
“Let’s see who this “early-stage VC” really is!”
Rather than dive into a full history of early-stage investing, I’ll anchor this post with the following loose — but by no means dogmatic — definitions of early-stage VCs (at least, as we’ve come to define them over the past decade or so):
Pre-Seed: The first institutional round of capital. Often comes before any revenue or pilots. The investment decision is primarily based on an evaluation of the team, their initial idea, and its market potential.
Seed: The first round of capital where traction plays a factor in the investment decision. Initial traction (revenue, pilots, etc.) provides early evidence that the product solves a real problem in the market and that customers are willing to pay to solve that problem.
Series A: The first round of capital where traction is at the forefront of the investment decision. At this point, there is enough traction to demonstrate that there is a real market for the product and that initial traction wasn’t a “fluke”. The investment decision focuses on how large and how fast the company can scale its early wins.
To frame it another way, the key variable around which the investment thesis is built for each of these stages is:
Pre-Seed: Team
Seed: Market Hypothesis
Series A: Traction
The Market Hypothesis
If you are unfamiliar with the term “market hypothesis”, it’s the statement that underpins a startup’s primary focus and typically takes the following form:
“There is a market X in which problem Y exists and customers are willing to pay for solution Z.”
If this concept seems vaguely familiar, it’s because of its close relationship to product-market fit (PMF). One definition for product-market fit is the point at which a market hypothesis is proven to be true (through the creation of a product/solution that slots into the hypothesis statement):
“There is a market X in which problem Y exists and customers are willing to pay for our solution Z.”
At the Pre-Seed stage, a market hypothesis may or may not be fully formed. Even if it is, investors typically incorporate into their investment decision an expectation that one or more aspects of it may turn out to be incorrect (and, thus, focus primarily on the team and their ability to iterate in search of product-market fit).
At the Seed stage, the market hypothesis is (historically) at the center of the investment decision. While it may not be in its final form, VCs evaluate potential investments through the lens of the market hypothesis that founders provide. Do they believe that the market is big enough? Do they believe that the startup has the right team to go after that market? To what degree does the early traction support the notion that their solution (a) solves the problem the founders are describing, and (b) demonstrates that customers are willing to pay for that particular solution?
(This is why it’s so important that founders spend time refining their positioning and market hypothesis before fundraising!).
What Has Changed?
While Seed-stage investments have been anchored around the market hypothesis for more than a decade, in the past few months things have shifted considerably. And the reason starts and ends with “AI”.
AI is changing so many things at such a high velocity that many Seed VCs are struggling with how to evaluate startups when they no longer have conviction that the market hypothesis will hold over their 7-10 year investment horizon. Consider the following:
“There is a market X…” — will that market still exist in 10 years?
“…in which problem Y exists…” — will this still be a problem in 10 years?
“…and customers are willing to pay for our solution Z” — will they still be willing to pay for this in 10 years?
Live footage of a Seed VC
While the above comments might seem facetious, it’s important to understand that these are real questions within the context of the role that Seed VCs have historically played. For the past 10+ years, Seed VCs have been primarily responsible for funding companies from the point at which they had a clear market hypothesis and early signals supporting that hypothesis through to product-market fit.
What happens when Seed VCs can no longer rely on those market hypotheses being stable?
How Seed VCs are Reacting
According to Crunchbase, the number of Seed deals in North America has fallen for 3 consecutive quarters — despite the fact that total deal volume by dollars remaining relatively strong. That means capital is concentrating at the Seed stage.
In other words, fewer deals are happening with larger average deal sizes.
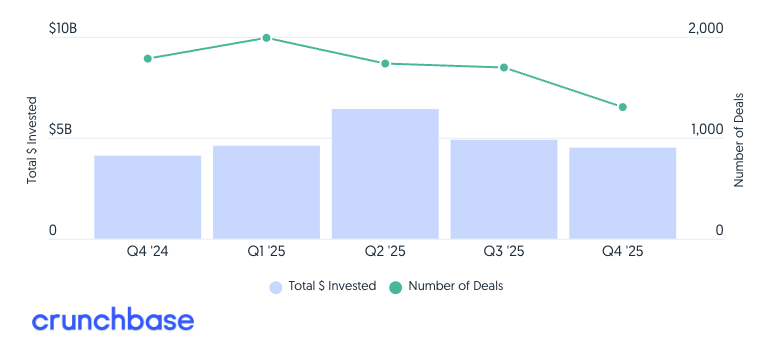
North American Seed Investment Through Q4 2025
Beneath the surface, Seed VCs are broadly reacting in one of three ways:
1. Reducing the Number of Deals
Some Seed VCs have reacted by doing fewer deals.
Over the past few months, I’ve spoken with a number of institutional LPs concerned by the fact that some of the funds they’ve invested in aren’t actively deploying capital. One early justification was the need to “slow things down” while they adjusted their investment theses to an increasingly bifurcated VC landscape. But at this point, it appears that some Seed VCs remain inactive / less active because they are simply unsure of what to do.
2. Chasing Repeat / Pedigreed Founders
Many Seed VCs are reacting by investing more in repeat founders and/or founding teams with a strong “pedigree” (graduated from top schools, worked at prominent companies, YC graduates, etc.).
Pitchbook showed a significant increase in the early-stage deal sizes commanded by repeat founders in recent years (in the chart below, “serial” founders are repeat founders who had an exit, while “unproven” founders are repeat founders whose prior companies failed).
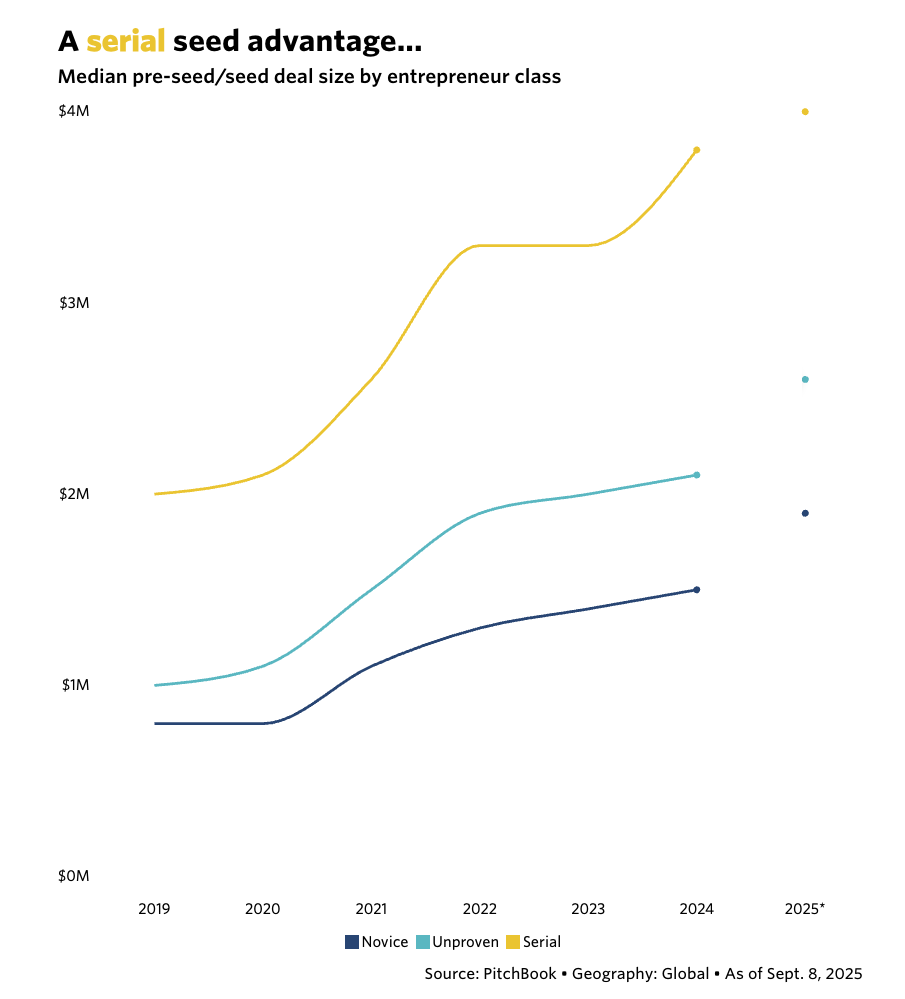
In the absence of conviction about the underlying market hypothesis, these investors are betting on the prior experience of the team.
“They figured it out before, so (hopefully) they can figure it out again.”
3. Focusing on Early Traction
The third trend has been to chase signs of early traction.
Early, disproportionate traction has always been something of a cheat code for startups. At the Pre-Seed stage, we often see deals happen quickly when a team comes to the table with unusually strong traction (revenue, users, GitHub stars, etc.), even if they don’t have a fully-formed market hypothesis.
The bet here involves a similar benefit-of-the-doubt as the one given to repeat founders:
“They figured out how to get to X traction, so (hopefully) they can leverage that to build a real product / get to product-market fit.”
Wait a Minute…
Ok, so to summarize what we’re currently seeing in the early-stage fundraising market:
Pre-Seed VCs generally discount the market hypothesis and focus primarily on the team and their ability to iterate in search of product-market fit
Seed VCs are increasingly discounting the market hypothesis and…focusing primarily on the team and their ability to iterate in search of product-market fit???
That’s right. Seed VCs are increasingly acting like Pre-Seed VCs when it comes to their investment decisions.
There’s a lot to unpack when it comes to the potential long-term implications of this shift. It’s especially fascinating within the context of the ongoing bifurcation of VC (and explains why some Seed VCs continue to sit on the sidelines — they simply don’t know how to invest based solely/primarily on the potential of a team). For now founders, angel investors and Pre-Seed VCs need to understand the following about what’s happening at the Seed stage:
Outside of markets that are unlikely to be disrupted by AI, the rubric with which many Seed VCs are evaluating potential investments has changed. Specifically,
The focus on traction has increased — not because it shows more evidence in support of the market hypothesis, but because it shows more evidence in support of the team’s ability to execute.
The focus on a team’s track record has increased.
The impact of whether or not a company is building in a “hot space” has increased.
While Seed VCs are increasingly acting like Pre-Seed VCs, it’s not exactly the same as raising another Pre-Seed round.
For starters, Seed VCs have a lot more data to analyze about your team and your trajectory (especially when it comes to velocity, the one metric that matters most).
It’s also important to understand that Seed VCs have promised their LPs a shorter path to returns than Pre-Seed VCs. In other words, they still need to get an exit in the same amount of time that they did before. This means that you have to be able to demonstrate meaningful progress towards something valuable (it’s not a do-over if you’re still wandering around in the woods in search of PMF).
Finally, this dynamic is most prominent with generalist Seed VCs. Specialized Seed VCs — particularly those in deep tech — are relatively unchanged in their behavior.
If you’re preparing to raise a Seed round, keep the following in mind as you fine-tune your pitch: in addition to analyzing the usual details on problem, solution, traction, etc., many Seed VCs are now asking themselves the following question as part of their investment process:
Can this team win (generate a return) even if one or more of their core assumptions is disrupted by AI? (In other words, can they still win if their market hypothesis gets disrupted?)
Unfortunately, it’s not at all clear yet how Seed VCs are testing for this. As a result, I suspect that we’re going to see a significant “crunch” at the Seed stage in the next few quarters. Startups that historically could raise funding based on a clear market hypothesis and reasonable early traction will struggle, especially if they can’t convince investors that the market hypothesis is viable over a long-term horizon.
Most Seed VCs don’t know what the future is going to look like, so they’re increasingly betting on founders who they believe can figure-it-out.
Who Should I Talk To?
I’m a big proponent of startup founders visiting San Francisco on a regular basis. But many make a fatal mistake when asking for on-the-ground introductions.
I’m a big proponent of startup founders visiting San Francisco on a regular basis. But there’s one mistake many founders make when planning their trip to Silicon Valley. Each-and-every week, I get at least one email from a founder that goes something like this:
“Hey Chris,
I’m coming to SF in a few weeks. Who are the 2-3 people I should absolutely talk to when I’m there?”
It seems like a reasonable enough request, right? Especially given Silicon Valley’s pay-it-forward culture. But emails like this are more likely to result in me hitting the trash button than typing out a reply.
Here’s why:
1. I Probably Don’t Know You
Granted, I don’t have the world’s best memory, but these emails generally come from people I barely know. In fact, they almost always come from founders I’ve spoken with exactly once.
Looking at the example above, the lack of familiarity is pretty obvious from the tone — you would never write an email like this to someone you’re friends with. But for some reason many people (particularly CEOs), think it’s okay to fire off what are effectively demands to relative strangers.

2. I Definitely Don’t Work for You
Not only are emails like this tone-deaf, they also imply a request: please do work for me.
In order for me to respond affirmatively to this request, I have to:
Look up our past interactions to refresh my memory on who you are and what your company does (granted, AI does help with this)
Then spend time to think about what help you might need at this point in your journey
After that, I need to think through the details of my personal and professional networks to match those needs with people I know
Next, I need to write a detailed email back to you about who these people are and why I think they might help you
Then…
Suffice to say, that’s a considerable amount of work for someone I barely know. And it certainly doesn’t show an understanding of the paradox of time.
3. I’m Very Protective of My Network
Even if I were to come up with 2 or 3 people that I think might be of use to you, I won’t promise you an intro.
In order for my friends to remain my friends, I need to be respectful of their time and ensure that all introductions are double opt-in.
How to Ask for Introductions
Chris Albinson, Managing Partner of True North Fund and cofounder of the Canadian expat network, C100, recently shared this advice with visiting Canadian founders,
“There are nearly 300,000 Canadians in the Bay and they sincerely want to help. But you have to show up prepared.”
This scenario is a great example of that.
Instead of asking someone to do all of the work for you, be specific in your asks,
“I’m hoping to meet 2 or 3 Pre-Seed investors to get feedback on my pitch before we start fundraising in the fall. Do you know any VCs who actively invest in X and might be willing to take a 20-minute meeting?”
“I want to meet CTOs of companies in industry X in order to ask about Y. Do you have any connections to such companies in your portfolio that you would be willing to pass along a request-for-intro email to?”
“I’m considering spending more time in San Francisco and would like to speak with a couple of expats who recently relocated there to learn about their experience. Do you happen to know anyone that might be willing to connect?”
Not only do each of these examples have specifics about the type of person the author wants to meet with, they’re also significantly more humble in their tone (which is likely to lead to more positive responses).
Here are some other tips:
Consider including a fully-written request-for-introduction email below the ask (so that the recipient can take action without having to go back-and-forth with you)
Use LinkedIn to research if a person is connected to individuals who meet your target and ask for specific intros (e.g. “I notice you’re connected to the following VPs of Engineering. Would you be willing to pass along a request-for-introduction email to any of them?”)
And always remember, to win transactions, don’t be transactional.
Hunters vs. Farmers
What does it mean if a VC is a “hunter” or a “farmer” and why does it matter?
Over the years, I’ve interacted with hundreds of VCs — first as a founder and, later, as an investor myself. And I’ve heard hundreds of investors pitch their funds. There is a distinct bifurcation in how VCs approach investing and, if you listen carefully to the words they choose to describe themselves with, that approach shows through.
The two approaches are known as “hunting” and “farming”.
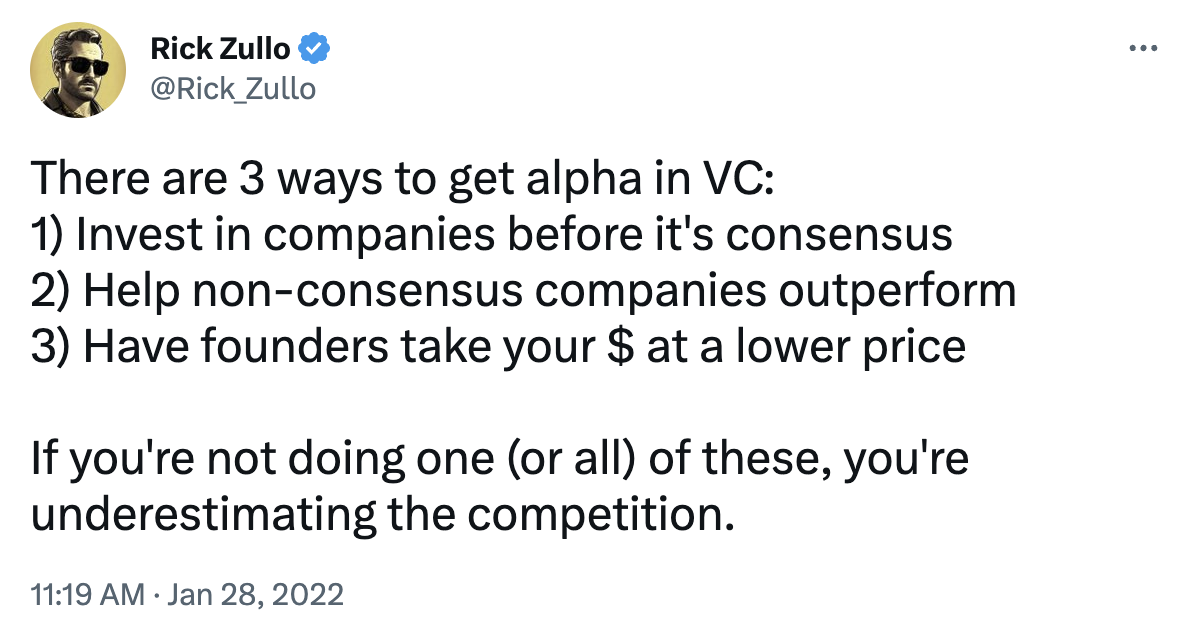
I’ve written before about hunting vs. farming within the context of how investors generate returns. In venture capital, “hunting” refers to going out and winning new deals (investing in new companies) while “farming” refers to increasing the likelihood that a company will succeed through post-investment support and services. In theory, investors should do both. In reality, VCs operate across a spectrum, with most firms focusing their efforts on one or the other.
I was recently at an investor conference filled with emerging managers (the VCs behind new, up-and-coming firms). As I listened to pitch-after-pitch from these aspiring VCs, it dawned on me that most founders probably don’t know how to recognize the signs that indicate if an investor is a hunter or a farmer. All VCs seems to use the same “value add” language when talking about why their fund is special, so how can you actually tell?
And why does it matter?
The Difference Between Hunters and Farmers
At a high level, “hunters” are VCs who spend most of their time and effort trying to get into the best deals. For the most part, they focus on companies that are (or will become) “consensus investments” — startups that at subsequent stages will be the hot companies that follow-on investors fight to get into.
Early-stage hunters focus on pedigree and traction as their primary signals. Things like:
Graduating from a top school or program (Stanford, MIT, Waterloo, IIT Bombay, Thiel Fellowship, etc.)
Early employees that left “hot” companies
Repeat founders
Hot sectors
Virality / significant early traction
They’re generally betting on the correlation between pedigree and outcome (or, at least, pedigree and quick markups).
Farmers, on the other hand, tend to cast a wider net. They’re betting on their ability to identify high-potential, non-consensus companies/founders and help them outperform. It’s not that farmers won’t invest in “hot” companies or founders with pedigree. It’s that they believe their edge comes from looking beyond those traditional signals.
It’s important to understand that both of these are valid investment strategies that can lead to great success. Not only that, you can find investors who do both to varying degrees at almost every stage of investment. Consider this map showing a selection of pre-seed investors:
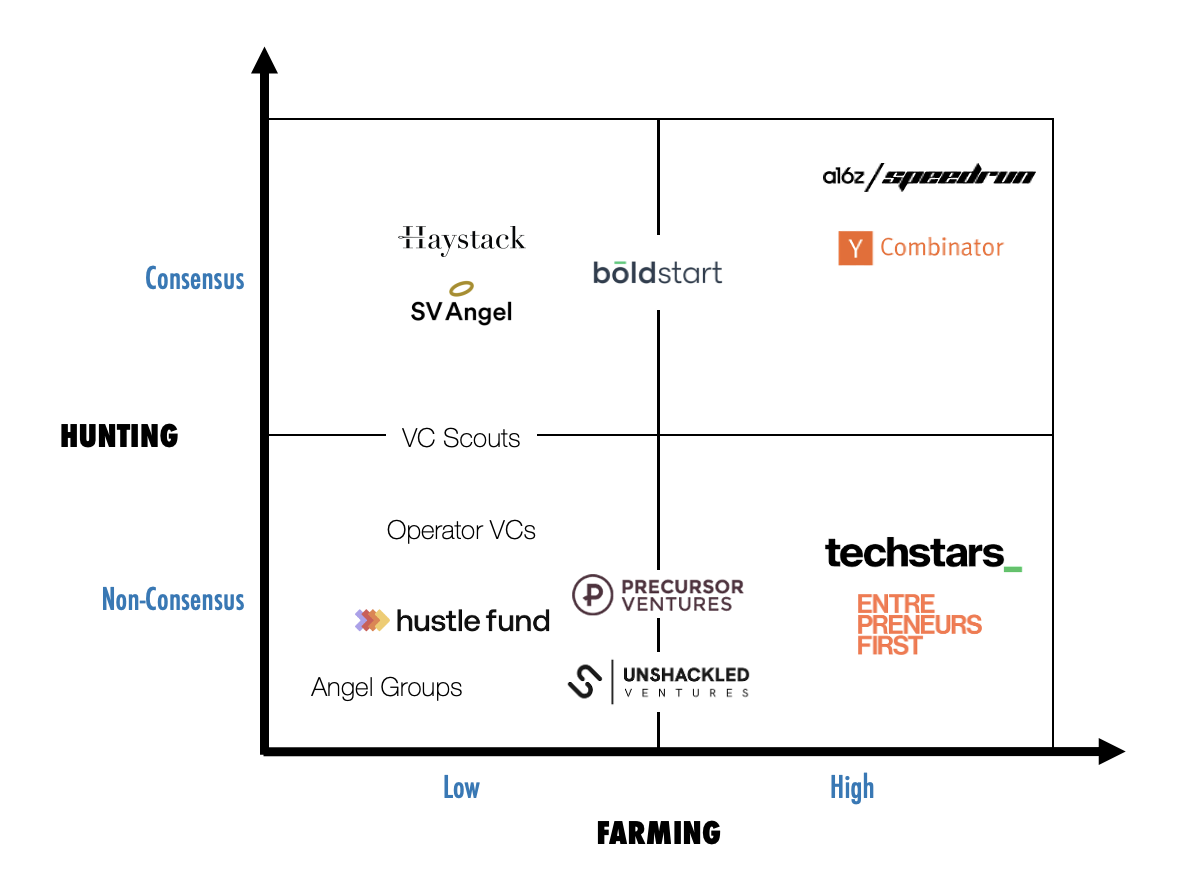
On the far right, you have accelerators. In the middle, are “hands-on” pre-seed funds (of which there are many). On the far left, you have hands-off investors, scouts and angel groups.
The Different Types of Farmers
You might be a bit confused looking at the above image, particularly given that many of the investors on the left side of the chart are known to be “very helpful” to portfolio founders. So let me specific about what I mean by farming. I consider a VC with a high degree of farming as one who regularly communicates with a founder (on at least a weekly basis) and provides hands-on help from the point at which they invest through at least the completion of their next round of funding. Accelerators and incubators typically have the highest degree of farming.
Investors with a low degree of farming might still be incredibly helpful, but that help is generally less frequent and/or lower touch. It might come in the form of on-demand introductions to potential customers, partners and follow-on investors or through “one-to-many” services.
Here is a very non-scientific ranking of the different types of VC farmers:
Passive Investors - After they invest, you rarely if ever hear from them (except occasionally in response to an investor update). Some can be very helpful with introductions and expertise but, generally speaking if you don’t call them, they won’t call you.
Automated Investors - These investors provide access to a selection of one-to-many resources (prerecorded videos, tutorials, webinars and online communities). Almost every email you get from them is from an automated system. One-on-one help is rare.
“Our Partners are Very Important People” Investors - These investors present as farmers — they often talk a big game about how they support portfolio companies — but after the deal is done, your point-of-contact suddenly switches from a partner to an associate or another lower-level member of the team. This approach is typically borne from VC firms trying to prioritize the “very important” partners’ time for hunting, as well as supporting the development of junior employees at the firm. While that sounds great on paper, it often feels like a bait-and-switch to portfolio founders (particularly when the “value-add” is provided by generalist team members with little or no real-world experience).
Board-Centric Investors - This category comprises a significant percentage of smaller VC firms (those with little or no support staff). Founders have a direct line-of-communication to their board partner (the partner who led the investment), but have little if any contact with anyone else at the firm. The board partner is often very hands-on, but the value provided is entirely dependent on what that individual brings to the table.
“We’re All Here for You” Investors - This is the next step up the farming ladder for smaller firms. In this case, founders have a direct (if infrequent) line of communication to all of the partners at the firm The board partner takes the lead on most matters, but the culture is such that founders are invited to reach out to any partner if they think they can help. Foundry Group (who invested in DataHero) had this approach — and I’ve always felt it to be the best strategy for small firms to take.
“We’re All Here for You” Investors II - Many mid-sized VC firms leverage analysts and associates to provide additional value add, like helping with research, market studies and financial analysis. The key difference between this category of VCs and “Our Partners are Very Important People” investors is that the associates/analysts provide services in addition to what the partner bring to the table instead of as a replacement for it.
Investors with a “Platform Team” - VCs with a platform team take the idea of additional support one step further by hiring experienced subject-matter experts to provide specific services to their portfolio companies. These hires can include recruiters, marketers, designers, media experts and even technical resources. Some of the larger traditional firms (most famously a16z) employ hundreds of people on their platform teams.
“We Have a Program” Investors - At the top of the farming pyramid are VC firms with “a program.” The difference between regular platform teams and platform teams at “We Have a Program” VCs is that startups who receive investment from the latter go through a formal program staffed by members of the platform team (as opposed to just receiving ad hoc support). Accelerators are the most well-known in this category, but an increasing number of traditional firms now have some form of post-investment programming (ranging from large firms like a16Z and Sequoia to smaller ones like Conviction).
(Strictly speaking, venture studios are at the tippy-top of the farming pyramid, but since most don’t invest in startups that are already up and running, I’ve omitted them from this discussion.)
How To Identify Hunters vs. Farmers
If all VCs seem to use the same, generic “value add” language when talking about their fund, how can you tell if they’re a hunter or a farmer? By listening to the subtleties in how they describe their approach.
In my experience, there are two topics where you can usually tell how a VC thinks about hunting vs. farming:
How the describe the founders they invest in
How they describe what they bring to the table (why they’re special / different / better than other VCs)
1. Who They Invest In
When describing the types of founders they invest in, hunters often use language that hints at pedigree and exclusiveness. Farmers, on the other hand, tend to emphasize the fact that they back founders from a variety of geographies, backgrounds and experiences:
| Hunters | Farmers |
|---|---|
|
"We only back the best founders" "We're looking for the top founders." "We invest in the top 1% of founders we meet." (Note: most VCs invest in about 1% of the founders they meet, but hunters often go out-of-their-way to make that point.) |
"We back founders from across North America." "We invest in founders from a variety of backgrounds." "We're less concerned with where you went to school and more interested in what you accomplished there." "We invest in founders from overlooked geographies." |
2. What Their Value-Add Is
When describing what their differentiation / value-add is, farmers tend to describe what they do (specific services / support offerings that they provide founders post-investment). Hunters, on the other hand, often focus on who they know.
| Hunters | Farmers |
|---|---|
|
"We know all of the top Series A investors." "We can introduce you to almost any C-level executive in your industry." "We host an annual CEO summit that brings together all of the founders in our portfolio with [insert celebrity CEOs here]." "We regularly host intimate/curated founder dinners with key industry stakeholders." |
"We facility monthly webinars with CEOs / CTOs / CROs across our portfolio to discuss specific topics." "We have a regular speaker series with subject-matter experts." "Each quarter, we host a fundraising bootcamp for companies preparing to raise their next round." "We have a number of resources on our platform team at your disposal. For example, we have a head of recruiting who can help you with executive hiring...." |
VCs can generate returns from almost any combination of hunting and farming. Which makes it essential to think in advance about what your ideal investor looks like.
Do you want a hands-on investor that will coach and mentor you through the next stage?
Do you feel confident in how to get from A to B, but need help with introductions?
There’s no right or wrong answer here, which makes diligencing a potential investor so important.
So when it’s your turn to ask an investor questions, turn the tables on them and ask the go-to question that so many VCs use:
“Why are you doing this, when there are so many other things you could be working on?”
“No, really. Why is this the thing you’re dedicated the next 10+ years of your life to?”
Then sit back and listen. You’re likely to learn more than anything you’ve read about them online.
I Have Questions…
Here are 5 red flags that leave VCs scratching their heads after reading your deck.
Over the years, I’ve written a number of posts about nonobvious mistakes that can hurt your fundraising process. There are the things that make VCs go "hmmm..." — subtle red flags that might not kill a fundraise outright, but cause enough potential investors to pause that they can meaningfully hurt your chances. There are phrases that founders often use without realizing that they have a different meaning for investors. And mistakes many international founders make when pitching US VCs.
In the lead up to last month’s Game On experiment, I reviewed hundreds of applications from founders across Canada (that’s right folks, although I use AI for many things, reviewing decks isn’t one of them). And there were a lot of things I saw that left me with more questions than answers.
Here are 5 red flags that leave most VCs scratching their heads after reading your deck:
1. Multiple Incubators / Accelerators
Let me get this straight: you did Rocket Founders? And then Instant Incubator? And Super Startups? And Awesome Accelerator after that…?
For a significant percentage of VCs, seeing multiple incubators / accelerators on a slide deck is a big red flag. In particular, seeing more than one equity-taking program on your slide deck makes me wonder:
Are you addicted to accelerators (like the startup equivalent of being a professional student)?
Did you not learn the material the first time?
Why haven’t you been able to generate enough revenue / raise enough capital that you need to keep doing this?
How messed up is your cap table…?
This is how most investors think about things:
0 or 1 incubators / accelerators: cool 👍
1 local / unknown incubator + 1 prominent accelerator: cool 👍 (e.g. SmallTown Startups followed by YC)
Multiple local / unknown incubators and/or multiple prominent accelerators: I have questions…
The only exception is non-equity programs (e.g. Creative Destruction Lab, 48 Hours in the Valley, Government-funded programs, etc.). These are generally useful and not held against you, but they also don’t show any particular signal to investors — so consider leaving them off your slide deck entirely.
2. More Advisors Than Employees
Nothing sets off a VC’s warning system quite like a team slide with 2 cofounders and 6 advisors.
I get it — when you’re just starting off, founders grasp for anything that will make them seem more credible. Big name advisors on the team slide do that, right?
What if you saw someone’s online dating profile and it had a single picture of them, followed by photos of their fitness instructor, their therapist and their financial advisor?
On the one hand, it’s great that you have those folks in the background helping you out. But they’re not the ones building the company.
If you have an advisor who is genuinely well-known (particularly in your domain), by all means put them on your team slide — it shows that you can attract prominent people to your mission. The problem comes when an advisor slide is filled with local nobodies. Although they might genuinely be helpful, they add zero credibility outside of a very small circle (and raise questions about why you need so many advisors).
Here’s my general rule of thumb: only put an advisor on your team slide if either (a) they are likely to be recognizable to the investors you’re pitching, or (b) Googling them immediately comes up with impressive accolades and accomplishments. Anyone whose LinkedIn profile starts with “startup advisor”or something equivalently generic should 100% be left off the slide deck.
Do not put guys like this on your team slide.
(P.S. Always remember that from a VC’s perspective, angel investors >> advisors — they believed in you enough to put their own money in!)
3. No Competition
If I get to the end of your deck and haven’t seen any mention of competition, then I have questions.
There is no such thing as a startup without competition. There might not be anyone else doing the exact same thing you are with the exact same approach, but your prospective customers/users definitely have alternatives.
Investors want to understand how they’re solving the problem today and why your solution is better. Most importantly, they want to know that you have a clear understanding of the market and what it’s going to take to win.
4. Too Many Awards
Similar to having too many incubators / accelerators, having a slide filled with goofy awards is a red flag for many investors.
Best Startup in Saskatoon for the Month of September!
Fastest Rising Founder according to Follower Count on Friendster!
Nantucket’s Next Best Nanotech Star!
Although awards like this can be genuinely helpful in some respects (particularly with early hiring and go-to-market), they mean absolutely nothing to investors. If anything, they’re likely to put more of a spotlight on the fact that you’re early in your journey (especially when paired with little-to-no revenue and/or a lack of supporting metrics).
Unless an award is genuinely interesting — such as one that comes from an industry conference or is paired with a significant non-dilutive cash prize — you should probably leave it out (note: if you did win a significant amount of money, make sure to put that amount in parentheses).
5. No Accomplishments
Wait…didn’t I just say too many awards is a bad thing?
As a potential investor, one of the most important things I’m trying to get is is a sense of your velocity. To me, that’s the one metric that matters most. When reviewing your deck, I’m looking for anything that hints at how fast you’re progressing — and those usually come in the form of bragging about accomplishments.
“We launched 3 months ago and already have $5K MRR!”
“In only 6 months, we built the MVP and signed 3 pilot customers!”
“Our prototype outperforms the old thing by 100x!”
Keep in mind that I’m looking for business accomplishments, not vanity metrics (see: goofy awards). Tell me what you’ve achieved as a team that genuinely matters and how fast you did it!
The Bouncer at the Nightclub
To succeed as a founder, you need to find ways to get past the bouncer.
We all know the scene.
There’s a long line outside of a packed nightclub. People dressed in their finest line the street, patiently waiting to get in. Except for those who don’t have to wait. You know the ones. The girls who flash a smile and strut past everyone. The guys who dap the bouncer as they confidently walk through the door.
Meanwhile, the normies dutifully stand in line, all-the-while grumbling about how unfair it is…
Now, let’s play make believe.
Imagine that instead of trying to get into a nightclub, you’re trying to get pre-release access to a new AI model. Or a meeting with a prominent VC. Access to an exclusive dinner for up-and-coming founders. Or an invite to the best private party taking place on the edges of that conference.
All of these scenarios have the same dynamic. And just like night clubs, it’s possible to work your way.
Here are four ways to get past the bouncer at the nightclub:
1. Get To Know the Owner
The most direct route into an exclusive club of any kind is to get to know the proverbial owner.
In Startupland™, that’s where the warm introduction comes in. In many cases, you can get direct access to any CEO, event organizer or investor through a warm introduction. The parallel to nightclubs comes from the fact that the introducer is vouching for you. They’re effectively saying to the nightclub owner, “this person is cool.”
Mind you, that doesn’t guarantee the introduction will work. In a world where the double opt-in intro is required etiquette, almost no one will promise you an intro.
If a warm introduction doesn’t work (or you don’t know anyone who can introduce you), you can often connect directly with someone via social media. In many cases, a well-written cold outreach can lead to success.
2. Get To Know the Bouncer
The next best approach is to make friends with the bouncer.
Whenever there’s exclusivity, there’s someone responsible for identifying high potential guests while keeping out the riff-raff.

Don’t mess with Bill Murray
In VC firms, it’s the Associates. In companies, it’s the front-line employees.
Spending time getting to know the people responsible for filtering access can help you eventually get the meeting, get access to the beta release or score an invite to the event.
3. Make Friends with the “In Crowd”
If you can’t get in on your own merits, making friends with someone who can get you in is the next best thing. Who’s already part of the club that you’re trying to get into?
If you’re hoping to raise from a particular VC, there’s no better intro than from one of their portfolio founders. Want to go to an exclusive event? Get to know the sponsors who are paying for it (your lawyers can probably get you into plenty of parties! 😂).
4. Slip the Bouncer a Twenty
I’m pretty old at this point, so I’m guessing that $20 won’t actually get you into a nightclub anymore, but you get the point. In a world of capitalism, there’s almost always a price. So what does that mean when it comes to startup founders?
Well, I’m certainly not suggesting that you directly try to buy your way into events (in most cases, it’s not going to work). But there is a parallel: selling your equity for access.

VCs love to brag about how much “value add” they bring to the table. One of the most impactful benefits investors can bestow on founders is access.
Almost every VC has some form of CEO summit (instant access to every CEO of every company in their portfolio). Most investors will brag about how extensive their rolodexes are. And many regularly host small format dinners and invite-only events. Whether it’s Sequoia or YC or one of numerous super angels, thinking intentionally about access as part of your fundraising decision can be a major cheat code.
“If I take capital from X, who (or what) can they help me get access to?”
Of course, you shouldn’t just take their word for it. Reach out to founders in their portfolio and ask how good they were at making connections and helping to “get them in the door.”
This may all sound very transactional, but getting access to the people, events and opportunities that can accelerate your business is an essential part of being a successful founder.
When it comes to startups, distribution wins. And networking is how founders distribute themselves.
If you spend time getting to know people who are well-connected and they see that you are genuine, high-value and have something to contribute (assuming that you are, in fact, all of those things), before you know it, you’ll start to find yourself nodding at the bouncer on your way in.
10 Nonobvious Things About Silicon Valley Fundraising
Here are 10 nonobvious tips about Silicon Valley fundraising from the VCs mentoring at Game On.
We’re in the final stretch of Game On, a 3-week experiment in founder velocity.
Week two was all about fundraising. Specifically, the second week focused on helping our out-of-town founders understand why fundraising from Silicon Valley VCs is different from raising capital elsewhere.
Here are 10 nonobvious things about fundraising in Silicon Valley according to our week two speakers:
1. Getting Warm Intros is Easier than it Seems
Charles Hudson, Managing Partner, Precursor Ventures
Charles Hudson has been investing in early-stage startups for more than 20 years. He noted that getting warm intros in Silicon Valley is far easier that it might seem from the outside.
“Trying to get warm intros can seem intimidating,” he shared with the founders. “But if you’re physically here in San Francisco, it’s far easier that it looks.”
Charles went on to explain that the Bay Area is effectively a “company town”. Almost everyone in the region is somehow connected into the tech/startup ecosystem.
“Of course you meet people at networking events,” Charles continued. “But you also see them at social events, community events or just bumping into each other.”
He encouraged founders to spend time in the Bay Area building connections and getting to know people as a way to prime their networks long before they need intros.
2. Cultivate Relationships Before You Fundraise
Emily Bennett, Partner, a16z
Emily Bennett, who co-leads a16z’s speedrun accelerator, similarly encouraged founders to cultivate relationships with Silicon Valley-based founders and other people within the “orbit” of the firms they hope to raise money from well before they go out to fundraise.
“As we get closer to investing in your company, we’re going to start doing backchannel references,” she explained. “That means we’re looking at LinkedIn and other sources to see who we know that you’re connected to.”
Emily went on to explain that for a16z, the number of connections a founder has to people known to partners in the firm is a factor in their investment decisions.
“Having a large number of connections to people in our orbit is a signal that you’re building relationships with the right people (or, at least, people who we think can make a difference for your company),” Emily continued. “Spending time getting to know founders and individuals connected to us long before you fundraise won’t just help you with warm intros, it will provide signal that you’re able to get into the right circles.”
3. People Will Open Doors…If You Come Prepared
Chris Albinson, Managing Partner, True North Fund
Chris Albinson has been traveling back-and-forth between Canada and Silicon Valley for nearly three decades, so he knows a thing or two about navigating ecosystems. The cofounder of C100 reinforced the willingness of people in the Bay Area to help visiting founders,
“There are nearly 300,000 Canadians in the Bay,” he remarked to the Game On cohort. “And they sincerely want to help. But you have to show up prepared.”
Chris went on to speak about the paradox of time — how people in positions of influence and power genuinely want to help but don’t have enough time — and the need for founders to come to meetings prepared.
“You need to know who the person is before you meet them,” he continued. “Don’t show up and ask them generic questions or things you can Google. Know who they are, what they’ve accomplished and how they, specifically, can help you before the meeting starts. If you do that, when you finish up and ask them to introduce you to 3 people who can help you with X, 99% of the time they’ll say yes.”
4. It’s Easier Than You Think to Get a First Meeting
Marvin Liao, Partner, Sukna Ventures
Marvin Liao, who has invested in nearly 500 early-stage startups during his career, echoed the notion that folks in the Bay Area are more open to initial meetings that it might seem.
“This is an ecosystem that’s built on knowledge and opportunities,” he shared with the founders. “Almost everyone in SF is from somewhere else. People here want to meet new people with new ideas.”
Marvin explained that simply walking up to someone and saying hi can lead to meetings and opportunities in ways you don’t generally see in other parts of the world.
“Whether you’re asking someone for a meeting at a conference, getting a warm intro from a founder, or connecting with someone at a hackathon, it’s way easier to get a first meeting than in other places.” But Marvin also cautioned the founders, “But that’s just the first meeting. After that, you have to earn it. If the first meeting sucks, you’re not getting another one!”
5. Pay-It-Forward Culture is Real
Angela Tran, General Partner, Version One Ventures
Toronto-born Angela Tran has spent the past 12 years investing in mission-driven founders as the San Francisco-based General Partner of Vancouver-based Version One Ventures. She admitted that after so many years in the Bay Area, she sometimes forgets how unique Silicon Valley’s “pay-it-forward” culture is.
“When I first came to the Bay Area, I was amazed how willing people were to do things without expecting anything in return,” Angela recounted. “People here will make introductions or find ways to help you after barely meeting you once.”
She went on to describe the contrast to other ecosystems she operates in,
“When I travel to other places, I meet people who make offers they don’t follow through on, or say things they don’t do. It’s those moments when I remember that Silicon Valley truly is special like that.”
6. Information is a Commodity
Alex Norman, Managing Partner, N49P
Alex Norman, Managing Partner of Toronto-based VC firm N49P and Cofounder of TechTO, noted that in Silicon Valley, information is a commodity amongst investors.
“First off, VCs are constantly sharing information with each other,” Alex offered. “They’re swapping decks, talking about startups they’ve met and otherwise trying to look smart. If you want to learn something from an investor or start building a relationship with them, offer them information.”
Alex referenced Mark Suster’s famous call to arms, Invest in Lines, Not Dots, and encouraged founders to find reasons to have touch points with the VCs they want to meet (check out this post for tips on how do do that).
7. The Best Founders Seem Inevitable
Gaurav Jain, Managing Partner, Afore Capital
A graduate of the University of Waterloo, Gaurav Jain cofounded one of the largest venture funds dedicated to Pre-Seed ($500M AUM). He observed that the best founders he’s invested in seem “inevitable”.
“You meet certain founders and it seems like their success is inevitable,” Gaurav shared. “They move fast. They’re impatient. They make you feel like they’re going to win with or without your help.”
He went on to share why that trait is so important to early investors.
“At my stage, I’m investing in the founders and not much else. The more confidence they have in themselves, the more appealing it is to me. But it’s not just about self-confidence, it’s also that they have a plan and know how they’re going to get there.”
8. Deck Design Matters More Than You Think
Arjun Dev Arora, Managing Partner, Format One
“Plenty of VCs claim that the design of your deck doesn’t matter,” started former founder and long-time investor Arjun Dev Arora. “But the reality is that deck design matters a lot.”
Potential investors are looking for the smallest signals in every deck they see, either as a reason to lean in or an excuse to pass.
“If you’re pitching a consumer app and your design sucks, you immediately lose credibility. Similarly, if you’re building back-office software for slow-moving enterprises but your deck looks like it’s for a Marin kombucha brand, it’s not going to fly. The design of your deck needs to reinforce what you’re trying to pitch to investors.”
Arjun went on to explain why seemingly small aspects of a pitch deck can matter so much.
“Ultimately, the pitch deck isn’t just a representation of the company, it’s a reflection on you as the CEO. Do you pay attention to details? Do you understand the market you’re going after?
Investors see dozens or even hundreds of decks a week — make sure you spend the time and effort to put your best foot forward.”
9. The Sense of Urgency is Palpable
Alysaa Co, Partner, Bain Capital Ventures
Alysaa Co is one of a very small number of people who have worked at both a Canadian-based VC firm and a Silicon Valley one. The former iNovia Associate and now Partner at Bain Capital Ventures noted that, from her vantage point, the sense of urgency that founders in the Bay Area have is unlike anywhere else in the world.
And investors in San Francisco are used to seeing that.
“Founders in San Francisco seem like they’re impatient about almost everything,” shared Alysaa. “It’s not just about 9-9-6. It’s as if they can’t wait to run through each obstacle and get on to the next one.”
After sharing several examples from her portfolio, Alysaa went on to observe that she’s become more cognoscente of urgency when evaluating new founders.
“You get used to seeing it. These days, if I don’t sense that urgency when I meet someone, I find myself less interested.”
10. You’re Just as Smart as Everyone Else
Dana Oshiro, General Partner, Heavybit
Vancouver-born Dana Oshiro, an investor in early-stage dev tools startups, channelled her nearly twenty years of experience living in Silicon Valley into words of inspiration.
“You’re just as smart as anyone here,” she offered. “The founders here aren’t smarter than you. They’re not better than you. What they have is a lot more reps and probably better networks. You can solve for that.”
Dana went on to encourage founders to find ways to operate at the speed of Silicon Valley,
“When you’re here, meet as many people as you can. Find out how they operate and figure out how to maintain that pace when you leave.”
How to Build a Silicon Valley Network
Here are the top tips for breaking into Silicon Valley and building a network that matters.
Last week, we welcomed 35 Canadian founders to San Francisco as part of an experiment in velocity called Game On. More than a third of the founders had never been to the Bay Area before, so we spent a good chunk of time helping them get acquainted with the unique culture and etiquette of the world’s preeminent tech ecosystem.
One of the big questions our founders had during week one was how to get to know quality people while in San Francisco. Here are some of the top tips for “breaking into Silicon Valley”, as shared by our speakers:
Leverage Your “Expat Network”
Michael Buhr, Executive Director, C100
As a former founder and the current executive director of the Canada’s tech expat network in Silicon Valley, Michael has been helping visiting Canadians build their San Francisco networks for more than 20 years. His number one piece of advice is to leverage that network to bootstrap local connections.
“Almost everyone in the Bay Area came from somewhere else — a different city, state or country,” shared Michael at the start of Game On. “And most everyone here genuinely wants to help. Reach out to people who grew up where you did and you’ll be amazed what happens.”
“If you reach out to a Canadian living in the Bay Area with a cold email or DM that starts with ‘I’m from Canada,’ 99% of the time you’ll get a response.”
Doing your homework before arriving in the Bay Area and looking up people you want to meet from the same city, school or former employer can give you a leg up when landing in Silicon Valley.
Follow Up Right Away
Ramneet Sran, Consul and Head of Office, Consulate General of Canada in San Francisco
The head of Canada’s Trade Commissioner Service in San Francisco, Ramneet Sran, emphasized follow-up in her advice,
“Try to follow-up with everyone you meet the same day. Don’t wait until tomorrow or next week or until you get home — they’ll forget about you by then.
Silicon Valley moves so quickly that one of the best things you can do is to simply make sure that there’s an email or text in their inbox before they go to bed.”
Even VCs have to remind themselves to do this
Do Things That Keep You Top of Mind
Tom Charman, CEO and Cofounder, Blok
Tom Charman has built multiple companies in the U.K., Germany and the U.S. He encouraged founders to find creative ways to stay top-of-mind, even when you aren’t in Silicon Valley,
“It’s easy to add people to your mailing list, but there’s so much more you can do,” he offered. “If you’re creating company swag, make extra and send it to the VCs, founders and other people in San Francisco you’re trying to build relationships with. For years, I’ve made a point of sending personalized Christmas cards to everyone I want to get to know.”
“Almost nobody does that anymore, so it really sticks out.”
Treat Your Visit Like a Vacation
Hiten Shah, CEO and Cofounder, Crazy Egg
Multi-time founder and prolific investor Hiten Shah offered this seemingly counterintuitive advice to visiting founders,
“Use every visit to the Bay like a vacation from your default settings.”
Hiten’s not suggesting that you kick it on Ocean Beach with a bonfire and a beer (though that can certainly be fun). Rather, it’s about being open to change and putting everything on the table,
“Go back with more urgency than you arrived with.”
Have a Plan
Clayton Bryan, Partner, 500 Global
Clayton Bryan has welcomed thousands of founders to San Francisco over the past decade. His advice was to make sure that you have a plan before trying to meet people,
“Too many founders spend their time in San Francisco all over the place,” he shared. “They’ll take our database of mentors and email every single one, without rhyme or reason. Or they’ll go to every single party and meetup they can…just because. That might fill your calendar with meetings, but it won’t move your business along.”
He encouraged founders to be clear on their goals and intentional about how they spend their time in the Bay Area,
“Who are you trying to meet? What are you trying to achieve? It’s cool to go to parties, but if you’re doing it for work, what will you consider a success?”
(If you want some tips specifically on how to get the most out of networking events, check out this post.)
Visit Often
Ian MacKinnon, Cofounder, Stingray Security
When Ian MacKinnon was building Later.com, he took full advantage of the fact that the company’s headquarters in Vancouver, British Columbia was only a 2-hour flight from San Francisco.
“I would regularly take the earliest flight down in the morning, go to investor or other meetings in Silicon Valley, and be back home in time for bed.”
By showing up in person periodically, you stay top of mind and build deeper relationships than you would if your interactions were entirely over Zoom.
“Plus, over time people will forget that you aren’t actually based in SF. Which is a huge advantage.”
For more ideas on what to do when you first land in San Francisco / Silicon Valley, check out these posts:
Get To The Point
When corresponding over email, it’s essential that you get to the point. Here are 5 common mistakes founders make when interacting over email.
If you’ve been reading my posts for awhile, by now you’ll likely have noticed that I regularly write about writing.
It’s not just because I’m pedantic about prose. It’s because we live in an era where a significant percentage of new relationships start in writing.
When you combine that fact with the paradox of time, the need to be concise in your writing becomes paramount. Whether your reaching out to potential investors, trying to cut through the noise with sales prospects or trying to get press for your startup, it’s essential that you get to the point.
Here are 5 common mistakes founders make when interacting over email:
1. Asking for Permission
Several times each month, I get cold emails from founders that include only partial details and then ask for permission to send the rest. For example,
“We’re raising a $1.5M pre-seed round. Can I send you the deck?”
Perhaps they once took a sales class where the instructor suggested this as a way to get a “buying signal”, but I can tell you that emails like this almost always go straight to my trash. I have neither the time nor the interest to go back-and-forth with someone I’ve never met to get the other half of an email I didn’t ask for.
If you’re going to do cold outreach (or even warm outreach!), make sure your emails contain all of the information necessary for the recipient to respond.
2. Explanation, Answer
Many founders — particularly those from Commonwealth countries — have a tendency to answer questions starting with an explanation or justification. In a verbal conversation, it might go something like this:
Investor: What is your revenue?
Founder: Well, we just started monetizing a few months ago,…
By the time you eventually answer the question, I’m convinced that you’re making excuses. So even if the answer is awesome, I’ll have already discounted it. Instead, answer the question directly, then add any context:
Investor: What is your revenue?
Founder: We’re currently at $1,500 MRR. We just started monetizing a few months ago,…
In writing, the impact of this mistake is amplified even more. When responding to written questions, make sure that you start with facts and then provide any explanation/justification afterwards.
Better yet, ask yourself if the justification is actually necessary. Oftentimes, you’ll come across as more confident by sticking to the facts and letting the recipient come back at you if they want additional details:
Investor: What is your revenue?
Founder: We’re currently at $1,500 MRR.
3. Having Someone Else Write Your Cold Email
Multiple times each week, I get cold fundraising emails in my inbox from someone who isn’t the CEO. They look something like this:
Hello Chris, thought you'd be the right person for this.
I represent a platform undergoing their Series A round with 125,000+ members and 40+ global partners built for independent professionals and enterprises. The company helps enterprises manage flexible talent while providing Individuals access to essential benefits usually reserved for corporate employees.
Can I share more details on their Series A round?
with appreciation,
[Redacted]
Revenue Growth Advisor(This one gets bonus points for also asking permission to share the rest of the details.)
Sometimes, these emails come from fundraising brokers. Sometimes, they’re from angel investors or advisors. Sometimes, the CEO has another employee at the company write the email. And sometimes they’re from a random person who I can’t for the life of me tell the nature of their relationship with the company.
Regardless, 100% of these emails go to my trash.
(Note: while early-stage fundraising brokers are common in some parts of the world, exactly zero credible VCs in North America will fund your Pre-Seed or Seed round if the introduction comes via a broker. So don’t waste your time or money with them.)
4. Unnecessary Sarcasm / Jokes
This is another strategy that, more often than not, is a turn off: starting with sarcasm or an unnecessary joke before getting to the point of the email.
Humor often works very well in-person, but amongst a flood of tightly-written emails, it often has the opposite effect. For example, I received a handful of emails after the deadline for Game On that started with some form of,
“I guess we didn’t get in…”
“I’m sure there were plenty of applications, bla bla bla…”
“I didn’t see an email after the deadline…”
I’m not sure what folks hope to gain with this. In contrast to the examples above, a number of applicants wrote very thoughtful emails asking for feedback, and I responded to almost every one. But the ones who started with unnecessary sarcasm or negging or jokes… 🤷♂️
5. Justifying No’s
This last point is less a mistake and more an opportunity for improvement.
One of the hardest personal evolutions for most founders is learning to say no.
In our early days, we worry that we might be missing out on something. We might close a door that could lead somewhere. Even when we become successful, we want to help and give back (hence, the paradox of time). But there’s a level beyond just learning to say no…
The S-tier evolution of this is learning how to say no without justifying the reason.
Believe It Or Not, Etiquette Still Matters
In the era of rage bait, showing deference, respect and etiquette in your interactions can make you stick out amongst a crowd.
A lot has changed over the past few decades when it comes to how we interact with the world around us. As a culture, we have become more casual, more concise and more curt. We are increasingly drawn to conflict, whether real or perceived. The Oxford Word of the Year for 2025 is “rage bait”:
rage bait (noun): online content deliberately designed to elicit anger or outrage by being frustrating, provocative, or offensive, typically posted in order to increase traffic to or engagement with a particular web page or social media content.
Recently, a number of startups that were clearly built with rage bait in mind were funded by prominent VCs, including Cluely (“cheat on everything”) and Chad (“the brainrot IDE”) — with plenty of opinions from the residents of Startupland™. A few weeks ago, Jordi Hays of TBPN published an excellent post on how we got to this point,
“To understand Chad IDE, Cluely, Icon, Friend, and the new class of Gen Z startups, you have to understand the online environment these founders grew up in. If you grew up on the internet and studied how and why certain people would regularly go viral, you know that making people mad has and always will be a highly effective way to get attention. The feedback loop is simple: 1) make something (product or ad) that makes people angry; 2) people comment/ share/ dunk; 3) because feeds are optimized to show posts with high engagement the most, you get more reach.”
He goes on to explain why he believes rage baiting ultimately won’t work as a product strategy. I’ll take it a step further: unless you’re specifically building in or around marketing, content, or certain subsegments of the direct-to-consumer market, it doesn’t even provide a short-term gain.
In other words, etiquette still matters.

Really…?
Like many former founders / early-stage investors, I interact with hundreds of people each week in marketing- and sales-related scenarios. I’m regularly:
On the receiving end of pitches (founders trying to raise money)
On the sidelines of pitches (founders asking for my feedback on both VC pitches and their own GTM)
On the periphery of pitches (doom scrolling social media like everyone else)
When rage bait first started to come to the forefront, I observed it mostly with idle curiosity. It seemed a pretty natural evolution of where we had been going culturally for some time. And for the most part, it remained squarely in the realm of marketing and content creators. Sure, a handful of creators leveraged their personas to build larger brands and companies, but none of this seemed to me all that different from the “villains” and “heels” of years past.
I started to pay more attention when rage bait began to creep into the realm of startups. First came the rage bait social media posts. Then bus stops and billboards. Before long, I started to see it in pitch decks and elevator pitches.
Here’s the thing: even in the early days of rage bait — when the approach seemed relatively novel (at least, to old guys like me) — the tactic didn’t come across differently from any other GTM approach. Except for one key aspect, which Jordi aptly noted:
“Rage baiting (whether at the marketing level or product level) is the most effective way to get people (who could be potential investors, customers, or team members) to actively pray for your downfall.”
So what does this have to do with etiquette?
Around the same time rage started to become more prominent, I noticed an uptick in what I’ll simply refer to as “rude” interactions with founders. I’m not talking about the handful of founders getting upset because they were rejected by a VC (that always happens). Rather, I’m referring to an increase in the number of interactions that were overly casual or unexpectedly disrespectful. It felt like there was more sarcasm, presumption and entitlement in many of my interactions — especially emails.
At first I wasn’t sure what to make of it, but before long I reached the conclusion that this was intentional (either that, or an unintended side effect of founders spending too much time in the realm of rage bait). In either case, a subset of founders seemed to be introducing a version of rage bait into their interactions with me. It was unmissable.
An increase in subtly condescending, overly casual introductions (“Yo lad,” “Hey bud,” etc.)
An increase in sarcasm in places it didn’t belong
Cold pitch emails clearly written as rage bait
The thing is, none of these worked (at least, not on me). If anything, they had the opposite effect. Requests I might have otherwise responded to went unanswered. PDFs I might have been inclined to open went to the trash.
After I announced next month’s Game On program, I received a flood of emails from founders. A non-insignificant percentage of those emails included some degree of rage bait, which got me thinking: what is my perception of people who use this as an intentional tactic?
Transactional
Short-term thinker
Fake
Untrustworthy
Unprofessional
…
Rage bait has become so widespread that it no longer resonates with me as shocking or creative or even worthy of a response. It’s honestly just lame.
If anything, I’ve found myself even more drawn to founders who exhibit basic etiquette and respect in their interactions. I’ve always been a sucker for a well-written cold email, but these days I’m even more likely to respond to emails that are simply polite.
The use of rage bait is still on the rise in Startupland™, but I suspect that it will be short lived. For now, just know that these days, showing deference, respect and etiquette in your interactions can make you stick out amongst a crowd. And always remember that you never get a second chance to make a first impression.
Know what I mean, bruh?
The Myth of the Magical Money Fairies
The myth of Silicon Valley’s magical money fairies is deeply entrenched in many ecosystems around the world.
There are a lot of myths and misconceptions that exist around the world when it comes to Silicon Valley. In my experience, no topic is more misunderstood (and, frankly, misrepresented) than fundraising.
It makes sense. Silicon Valley is by far the largest source of capital for tech startups. Combine that with the fact that most folks in other ecosystems learn about its dynamics through click-bait funding announcements loosely wrapped as “journalism” and its easy to understand how perceptions can be skewed.
There’s one myth in particular that I’ve seen do more damage to startups around the world than any other: it’s the myth of the magical money fairies.

The myth of Silicon Valley’s magical money fairies is deeply entrenched in many ecosystems around the world. And it really is a myth in the truest sense. For millennia, human folklore has contained popular stories about treasures and fortunes that have some grain of truth, but are vastly overstated in terms of likely outcome. For example, most children learn the old Irish myth about leprechauns with pots of gold at the end of a rainbow. All you need to do is catch one and, voila!
Replace “leprechaun” with “Silicon Valley VC” and you’ll see where I’m going with this one.
(As an aside, the leprechaun myth had its origins back when vikings invaded Ireland, buried looted treasure around the island and eventually left while leaving some of their stolen gold behind to eventually be discovered by locals…).
So what exactly is the myth of the magical money fairies?
Simply put, there is a pervasive belief around the world that it is easier to raise money in Silicon Valley, because VCs there are more risk-taking / willing to invest / willing to “take a chance”. Like magical money fairies, they will obviously be willing to invest. You just need to get to them.
Like any myth, there are grains of truth at its core. For example, VCs in Silicon Valley are more willing to invest in pre-prototype companies than VCs in other ecosystems. But it’s not because they’re more risk-taking, it’s because more of them have the technical background needed to “invest in napkins”.
Similarly, it is broadly true that founders can raise a round of funding quicker in Silicon Valley than in other ecosystems (which can feel like the investors are more risk-taking / willing to invest / willing to “take a chance”). In reality, there are two key dynamics at play:
There are generally more VCs in Silicon Valley that invest in a given industry than in other ecosystems (which makes it possible to have more credible pitches in a shorter period of time).
Silicon Valley VCs have learned to perform deep diligence much faster than VCs in other ecosystems (and often in ways that are imperceptible to founders). That can feel like they’re doing less diligence, though I promise that’s not the case.
What makes this myth particularly dangerous is the unrealistic expectations that many founders (and ecosystem proponents) have when it comes to Silicon Valley VCs as a result of it. Here’s a dynamic I’ve seen play out hundreds of times:
A founder tries to fundraise locally, but struggles.
They receive consistent, repeated feedback from multiple local investors. Rather than paying attention to the feedback and addressing it, they attribute it to “risk aversion” and keep going.
Emboldened by fundraising books, blogs and well-meaning supporters who loudly cheer “you just need one yes”, they keep going. They limp along from investor to investor, often for months.
As they approach the end of their runway, having lost 6+ months of time fundraising (and having not addressed the core challenges of the business or made further progress), they spend their last bit of money on a “Hail Mary” trip to San Francisco.
Landing in the Bay Area, they finally meet Silicon Valley VCs. All of whom see the exact same weaknesses in the business that their local investors saw, plus a company with no runway and a founder who wasn’t willing to listen to feedback.
The fundraising trip fails and the founder returns home, closing the business shortly thereafter.
Unfortunately, those stories rarely make it back into the ecosystem. Many founders who travel this path eventually realize their folly, but are too embarrassed to share their experiences publicly in ecosystems that are more likely to punish failure than celebrate the attempt.
Absent these important stories, the myth of the magical money fairies perseveres — in part because the handful of outlier founders who do end up raising in the Valley typically make a lot of noise about it.

It is, of course, true that Silicon Valley VCs often see things differently than investors in other ecosystems. But that goes both ways.
Silicon Valley VCs might see an opportunity that local investors don’t. They might be willing to take a chance on a founder that local investors aren’t convinced about (Jesse Rodgers refers to this as small-town bias).
But they’re just as likely to be skeptical about a business that local investors are tripping over themselves to back. I’ve seen plenty of startups over the years fail to raise in Silicon Valley, despite their hometown investors being incredibly bullish (a different perspective on revenue and growth is often the culprit).
Despite what many founders and ecosystem supporters continue to believe, it isn’t easier to convince a given VC in Silicon Valley to invest in a company — it’s much, much harder. But there are far more VCs in Silicon Valley than in other ecosystems and, generally speaking, they make faster decisions.
So what is a founder to do with this information?
Simple. If you are trying to raise a fundraising round, you should absolutely include Silicon Valley VCs in the mix. But don’t do it at the end of your process, do it in parallel. Understand that the vast majority of early-stage funding rounds happen locally — the mythical U.S. lead investor does not, in fact, exist. But fundraising is a numbers game and the more potential investors you have in the mix, the more likely you are to succeed.
Just don’t expect Silicon Valley VCs to gloss over legitimate concerns that local investors have raised. VCs in different ecosystems do see the world differently. But none of them are charities. Their job is not to “give you a chance”, it’s to generate a return on investment.
In that sense, they are actually magical money fairies…for their LPs.
Why Do 99% of Startup Accelerators Fail?
Why do 99% of startup accelerators fail to live up to their expectations?
In 2005, Paul Graham, Trevor Blackwell, Jessica Livingston, and Robert Morris decided to run an experiment. Paul had a hypothesis that undergraduates were undervalued when it came to starting companies. At a time when almost all VC’s required a “business cofounder” to run the company (aka a CEO with an MBA from a fancy school), Paul et. al. believed that the world was changing,
“This summer, as an experiment, some friends and I are giving seed funding to a bunch of new startups. It's an experiment because we're prepared to fund younger founders than most investors would. That's why we're doing it during the summer—so even college students can participate.
We know from Google and Yahoo that grad students can start successful startups. And we know from experience that some undergrads are as capable as most grad students. The accepted age for startup founders has been creeping downward. We're trying to find the lower bound.”
Their summer 2005 experiment — referred to as the Summer Founders Program — is today better known as Batch #1 of Y Combinator.
SFP included Alexis Ohanian (Reddit, Initialized Capital, 776 Ventures), Justin Kan (Kiko, Twitch) and Sam Altman (Loopt, OpenAI)
Fast forward twenty years and there are self-proclaimed “startup accelerators” around the world. Yet despite all of the innovations that have occurred over the past two decades — technologically, socially, and business-wise — YC remains the world’s preeminent accelerator — and it’s not even close.
So why is it that 99% of accelerators fail to live up to their expectations?
What is a Startup Accelerator?
Let’s start with a definition, to make sure we’re all on the same page.
The key characteristic of a startup accelerator is that it accelerates a startup.
You might think I’m being facetious, but I’m not. A startup accelerator is a program that is purpose-built to accelerate the trajectory of a high-growth tech startup. Implicit in that definition is that the participants are founders/cofounders of a startup with a clearly-defined market hypothesis (a business idea). They are not founders in search of an idea, a cofounder or a market for their technology.
This distinction is crucial (and we’ll get back to it later).
What Do Startup Accelerators Do?
The basic concept of a startup accelerator has changed very little since the Summer Founders Program. In October 2005, Paul Graham shared some of his learnings from the initial batch. It’s incredible how many of those observations remain at the core of today’s accelerators:
Mentorship
“Some we helped with technical advice-- for example, about how to set up an application to run on multiple servers. Most we helped with strategy questions, like what to patent, and what to charge for and what to give away. Nearly all wanted advice about dealing with future investors: how much money should they take and what kind of terms should they expect?”
Pitch Practice and Demo Day
“The weekend before the demo day for investors, we had a practice session where all the groups gave their presentations. They were all terrible. We tried to explain how to make them better, but we didn't have much hope. So on demo day I told the assembled angels and VCs that these guys were hackers, not MBAs, and so while their software was good, we should not expect slick presentations from them.
The groups then proceeded to give fabulously slick presentations. Gone were the mumbling recitations of lists of features. It was as if they'd spent the past week at acting school. I still don't know how they did it.”
Investor and Customer Intros
“I was surprised how much time I spent making introductions. Fortunately I discovered that when a startup needed to talk to someone, I could usually get to the right person by at most one hop. I remember wondering, how did my friends get to be so eminent? and a second later realizing: shit, I'm forty.”
Peer Learnings
“Just as happens in college, the summer founders learned a lot from one another-- maybe more than they learned from us. A lot of the problems they face are the same, from dealing with investors to hacking Javascript.”
Batch Format
“Another surprise was that the three-month batch format, which we were forced into by the constraints of the summer, turned out to be an advantage. When we started Y Combinator, we planned to invest the way other venture firms do: as proposals came in, we'd evaluate them and decide yes or no. The SFP was just an experiment to get things started. But it worked so well that we plan to do all our investing this way, one cycle in the summer and one in winter. It's more efficient for us, and better for the startups too.”
Twenty years later, startup accelerators around the world all follow roughly the same approach as that first Y Combinator batch:
Cohorts of startups / founders participate in a program that takes place over a defined period of time
The accelerator invests on standardized terms (typically at a lower valuation than a traditional VC would provide — thus pricing in the perceived benefit of the program)
Founders benefit from both peer learnings and the peer pressure that comes from being in a class / batch
The organizers provide mentorship and facilitate introductions to customers and potential investors
Most programs conclude with a “demo day” event, where potential investors can meet all of a program’s startups at once
The most significant evolution of accelerators has been the addition of standardized content intended to streamline learnings that almost all first-time founders have, such as:
Go-to-market (sales/marketing best practices)
Finding product-market fit
Fundraising
Startup Schools are Not Accelerators
A significant percentage of programs offered to startups around the world are not, in fact, accelerators. They are startup schools.
Startup schools teach founders the basics of running a company along with various concepts and methodologies related to entrepreneurship. But they do not accelerate a company in a fundamental sense.
True acceleration changes the trajectory of a startup by instilling founders with the best practices and work habits needed to succeed. And if we’re talking about building world-changing companies, then what we’re referring to is specifically, “instilling founders with the best practices and work habits needed to create billion-dollar companies.”
How does that happen? Through one-on-one mentorship.
If the definition of a startup accelerator is “a program that accelerates startups” and the primary means through which these programs effect change is through mentorship, then the quintessential requirement of a good startup accelerator is good mentorship.
But what is “good” mentorship?
The One About Youth Sports
Let me tell you about my friend Kenndal McArdle.
Like me, Kenndal is an early-stage investor. He is also a former founder. Kenndal and I have kids that are the same age and we both coach their sports teams. But there’s one big difference in what we bring to the table in that regard.
You see, one of us was a first-round draft pick of the Florida Panthers and played in the NHL. And one of us is me.

While we can both teach our kids the fundamentals of playing sports, only one of us has first-hand experience in the best practices and work habits necessary to reach the highest echelons of professional sports. Kenndal has a gold medal from the 2007 World Junior Championships. I watched the 2007 World Junior Championships on TV. We are not the same.
At a basic level, this is the fundamental flaw with 99% of startup accelerators. The mentorship in almost all of the world’s “accelerators” is provided by well-meaning individuals who have zero personal experience at the highest echelons of tech. Many have genuine experience building and/or investing in startups, but the vast majority have no firsthand experience building billion-dollar companies (as a founder, employee or investor).
They can teach topics, but they don’t actually know what it takes to reach the pinnacle.
Spotting Opportunity is Only the First Step
Almost all accelerators are founded by individuals who observe specific problems and/or opportunities within their ecosystems.
Y Combinator’s founding was a response to Paul Graham’s observation that “hackers” (specifically, undergraduate hackers) were not getting as much funding as he felt they deserved and that there was an investment opportunity to be had in addressing that need.
Techstars was founded in the tiny community of Boulder, Colorado by David Cohen, Brad Feld, David Brown and Jared Polis, who believed that there was a lack of funding available to founders in middle America and that there was an investment opportunity to be had in addressing that need.
Boulder is a wild place 🤘
500 Startups’ origins came from the observation that women, minority and foreign founders did not have access to the same degree of funding that white male Stanford graduates had access to and that there was an investment opportunity to be had in addressing that need.
So why did these accelerators flourish while so many others failed? It starts with the experience of the founders:
Y Combinator: YC cofounders Paul Graham and Robert Morris previously cofounded Viaweb, the world’s first application service provider. They subsequently sold the company to Yahoo! and witnessed Yahoo!’s meteoric rise through the dotcom bubble.
Techstars: David Cohen, David Brown and Jared Polis all cofounded multiple successful tech startups while cofounder Brad Feld cofounded both startups and VC firms (most notably Foundry Group).
500 Startups: In addition to founding his own startups, Dave McClure was a member of the famed PayPal Mafia and an early employee at Simply Hired.
In all three cases, the founders had firsthand experience working at globally-successful tech startups. While they were not the founders of those companies, they had experience working with (and observing) the habits of exceptional founders both as employees within such companies and as investors later on. They understood from multiple angles what exceptional looked like.
But, more than that, they also had direct relationships with dozens of other founders and early employees who had similar firsthand experience inside the world’s biggest tech companies. Relationships that they could leverage for the benefit of the startups that went through their programs. (Recall Paul Graham’s observation from Y Combinator’s first batch: “I discovered that when a startup needed to talk to someone, I could usually get to the right person by at most one hop.”)
Anatomy of a Premier Accelerator
Let’s get back to the topic of mentorship.
What sets the world’s best accelerators apart is the strength of the teams working with founders. The quality of the mentorship, as well as the introductions that mentors can potentially make.
This starts with the employees of the accelerator. The best accelerators employ partners, entrepreneurs-in-residence and even operational staff who have firsthand experience working in some of the world’s fastest-growing tech companies.
Here are just a few of the people I had the privilege of working with at 500 Startups back in its heyday:
Jake Gibson (previously Cofounder of NerdWallet)
Sheel Mohnot (previously Founder of FeeFighters, which he sold to GroupOn where he became VP of Business Development)
Marvin Liao (previously head of international markets for Yahoo!)
Arjun Dev Arora (previously Founder of ReTargeter)
Binh Tran (previously Cofounder of Klout)
Elizabeth Yin (previously Cofounder of Launchbit)
Eric Bahn (previously Founder of Beat the GMAT and early employee at Instagram)
Mike Sigal (multiple time cofounder with both acquisitions and IPOs under his belt)
A gathering of a few old friends
A few of these individuals were founders of unicorns. But all of us had direct, firsthand experience with billion-dollar tech companies (as key employees, founders/early employees of companies that were acquired into unicorns, and as investors). We had each seen firsthand the best practices and work habits necessary to reach the highest echelons of tech.
That experience is key. But it’s not just the employees. It’s their personal networks and the multiplier effect that comes from them.
On Density and Mentorship
The world’s best accelerators surround founders with mentors and subject-matter experts who have directly contributed to some of the world’s most successful tech companies. Some of those mentors are employees of the accelerator. Many more come from the employees’ personal networks.
It’s this ability to provide founders with a wide variety of high-quality mentorship that differentiates the best accelerators from the rest. Ultimately, quantity of “good” mentors matters to the ongoing success of an accelerator almost as much as quality.
The companies within an accelerator batch are generally trying to solve vastly different problems in a variety of markets. While some of the mentorship topics (e.g. fundraising) have commonality across the batch, many more — from sales and marketing to product development — differ. So being able to pair each founder with multiple mentors who have direct experience in their industry and with the specific problems they’re trying to overcome matters.
If you think about my friend Kenndal, he’s a phenomenal mentor for anyone who wants to play professional sports. But he has far more to offer someone whose specific goal is to play left wing in the NHL than others. As a mentee strays further away from his lived experience (from left wing to other hockey positions and from hockey to other sports), his experiences and mentorship will necessarily be less relevant and specific. Introductions that he can potentially make will similarly be fewer and less direct.
This is why accelerators in smaller ecosystems generally fail over the long term. Even if there are a handful of unicorns locally, the specific experience and advice of the mentors coming from those companies will only resonate with a subset of founders. You can also only call on those same people so many times. If you think about it as a “snowball effect”, it’s a lot harder to build a snowman when there isn’t much snow on the ground.
This is why Silicon Valley has such an advantage when it comes to startup acceleration: experience and mentorship compounds.
When I was at 500 Startups, if I wanted someone with a particular type of experience to stop by (for office hours, to meet with a specific company or to deliver a talk), I could easily reach out to multiple people at multiple companies and find someone willing and able to drop by our San Francisco office. That’s simply not possible anywhere else in the world.
Even YC — which originally split batches between Silicon Valley and Boston/Cambridge — ultimately shifted entirely to the Bay Area. In 2009, Paul Graham wrote the following:
“I think it will be better for the startups we fund to all be in the Valley. We never tried to claim to the startups in the summer cycles that it was a net advantage to be in Boston. The most we could claim was that we could mitigate the disadvantages sufficiently well—for example, by flying everyone out to California to present to investors at our Mountain View office. But we did worry that the Boston groups were losing out. Boston just doesn't have the startup culture that the Valley does. It has more startup culture than anywhere else, but the gap between number 1 and number 2 is huge; nothing makes that clearer than alternating between them.”
But, But, But…
“But wait!” you say, “What about all of those big name accelerators around the world?”
How could the above claim hold true if so many prominent accelerators have created programs in cities around the world?
Simple.
Those “global” programs aren’t actually startup accelerators. They’re mostly government- and corporate-funded startup schools.
About 10 years ago, governments and corporates started approaching some of Silicon Valley’s accelerators with a proposition: if we pay you money, will you run a program locally in our ecosystem / for our specific industry?
At first glance, there seemed to be clear synergies. Founders in underrepresented geographies or industries would get programming, education and mentorship from experienced Silicon Valley founders and investors. Accelerators would gain exposure, access to new markets and revenue. They could expand their impact globally (which many genuinely wanted to do). But it didn’t take long before the shine wore off.
It turns out that few, if any, of these programs consistently birthed companies that the accelerators actually wanted to invest in. So while the first few batches were typically led by experienced Silicon Valley founders and investors excited to visit new ecosystems, before long the quality of mentorship plummeted as the accelerators shifted resources. Out of town experts were soon replaced with inexperienced local mentors, augmented by a roving band of “digital nomad” mentors who travel the world, offering their services to any accelerator or incubator willing to pay their room and board (trust me, there’s a lot of them).
Over time, many of these accelerators became addicted to the (very significant) revenue that governments and corporates around the world offered. They created entire divisions dedicated to selling and staffing such programs (in some cases, those divisions became larger than the actual core fund / accelerator). A focus on DPI was replaced by an obsession with program margin, often with disastrous consequences.
But There Have Been Successes Outside of Silicon Valley
Yes and no.
Over the past 20 years, there have been a number of examples of accelerators operating successfully for brief periods of time outside of Silicon Valley. But almost none of them succeeded over the long-term. In many cases, these programs were founded in nascent startup ecosystems hungry for any sort of cohort-based programming and benefited from an initial "burst” of extremely high quality founders. In others, an initial set of high-quality mentors eventually gave way to inexperienced replacements, with the quality of the program (and its results) soon following. We really haven’t seen accelerators form outside of Silicon Valley that have repeatedly, consistently shown an ability to take early-stage startups and accelerate them into unicorns.
What we have seen come out of other geographies are some of the most incredible, innovative “pre-acceleration” programs. Recall my earlier assertion that a startup accelerator is a program that is purpose-built to accelerate the trajectory of a high-growth tech startup. What about before then?
In 2011, Matt Clifford and Alice Bentinck founded Entrepreneur First in London. Their observation: that there was a lack of mentorship and guidance available for talented individuals who had the potential to be founders but didn’t necessarily have a specific idea in mind.
In 2012, Ajay Agarwal founded Creative Destruction Lab at the University of Toronto. His observation: too many PhD researchers were being hired directly into large tech companies instead of commercializing their research.
Both of these organizations have become globally impactful, each with billions of dollars worth of equity value created and multiple unicorns emerging from their programs.
(At this point, I’ll admit that the line between accelerator and pre-accelerator is a blurry one at best. YC, for example, is known to accept some founders whose ideas aren’t yet fully formed, while both Entrepreneur First and Creative Destruction Lab accept incorporated startups. The distinction as I see it is about whether the program primarily focuses on helping founders figure out whether or not a concept could be massive vs. instilling the best practices and work habits necessary to accelerate and ultimately reach that level of success.)
Accelerating the Rest of the World
We’re getting to the finish line here, I promise!
If the quintessential requirement of a good startup accelerator is good mentorship and only Silicon Valley has a sufficient quantity and diversity of mentors to cater to a wide diversity of founders, how can we reasonably accelerate startups in the rest of the world?
By leveraging Silicon Valley’s talent.
Side note: I’ve found over the years that, for some reason, this simple, seemingly innocuous statement offends a lot of people.
If I were to say to a minor league hockey coach, “I can bring some former NHL players to come work with your kids for a week,” or “We’re running a camp on the sidelines of this year’s all-star game and we’d like to invite some of your kids to join,” every single coach would be over the moon. No one would respond, “No, no…we don’t need that. One guy from our town made the NHL 15 years ago. We’re good.” Yet for some reason that’s the reaction that comes from many ecosystem builders when it comes building connections with Silicon Valley.
I’m not going to go down the rabbit hole of why this happens (it’s surely a deep one). Suffice to say, the idea of leveraging the world’s largest pool of startup experience to augment local mentors shouldn’t be a controversial one.
In any case, there are two obvious ways to leverage Silicon Valley experience for the benefit of global ecosystems: bring Silicon Valley’s mentors to the world or bring the world’s startups to Silicon Valley.
Both approaches can work. In fact, they’re not even exclusionary.
I won’t go into a discussion of how to do this — that’s a post for another day. Instead, I’ll conclude with the following observation:
Like many things in Startupland™, the majority of accelerators around the world have failed as a result trying to replicate something that can (at least today) only work at scale in Silicon Valley. But that doesn’t mean there can’t be successes elsewhere.
They just won’t look like “the YC of X.”

How to Approach Someone at an Event
Knowing how to get the most out of an event is an underrated and unpracticed skill for many founders.
It’s the second week of September.
The memories of summer are already starting to fade away. The annual ritual of “back to school”, a glorious event celebrated by parents across the northern hemisphere, has come and gone. Burning Man is over. So is the After Burn. And the After After Burn.
For most of the world, that means back to the humdrum of office life. But for residents of Startupland™, the second week of September marks the start of fall event season. YC officially kicked things off yesterday with with their S25 Demo Day in San Francisco. In startup ecosystems around the world, the coming weeks will be filled with happy hours and hackathons, receptions and retreats, soirees and cinq à septs. (All while founders try their best to make actual progress on their business and VCs fight over the hottest deals.)
Packed room to hear the Mayor of San Francisco speak
It’s a busy time of year, but also one filled with opportunities…provided you play your cards right.
Knowing how to get the most out of an event is an underrated and unpracticed skill for many founders. I’ve previously shared tips for how to pitch a VC at a party. In this post, I’ll pop up a level and discuss more broadly how to make the most out of any work-related event.
1. Define Your “Why”
The best founders don’t go to events for the sake of going. At least, not after the initial buzz of being invited to “exclusive” events for the first time wears off (we’ve all been there). There has to be a reason for high achievers to take time away from work, friends, family and other priorities to attend a professional event. What’s yours?
There are plenty of reasons to attend an event, including:
Prospecting for customers
Prospecting for investors
Prospecting for employees
Getting feedback on an idea
Meeting other high-achieving founders (for inspiration, to build your network, etc.)
Showing support for someone or their company
Being seen and/or catching up with people you already know
Just getting out of the office (that’s okay too!)
Before you go to an event, take a moment to really think about your objective. What is your “why” for attending the event?
2. Quantity or Quality?
The second question to answer is “quantity or quality?”
Do you want to have deep conversations with a small number of people or are you hoping to connect with as many individuals as possible who fit your target persona?
Think about this question carefully. Would you be happy if you spent the entire night speaking to only one person? What if you already knew them? Are there specific people you absolutely have to speak to (if only so they know that “you were there”) or is your primary objective to meet new people?
Even if your reason for going to the event is simply “to get out of the office,” thinking about the types of conversations you hope to have and/or the types of people you hope to meet will help you to navigate the event with more intentionality.
3. Target List
Who are the people you absolutely, positively need to see at this event?
Write down those names or personas and what your objective is with each person (Is it simply to say hello and be seen? Do you want discuss a particular topic with them? Do you hope to get their contact information?) If you have access to the invite list, spend 5 minutes to review it and highlight anyone you specifically want to talk to. Think about the types of conversations you hope to have with each person and how much time you want to spend with each of them.

“At 7:35pm, the Series A VC will arrive…”
4. The Approach
Despite the title of this post, I’m not actually going to tell you how to approach a stranger at an event. There are plenty of books, posts and podcasts that have been made on the topic, so I’ll leave that as an exercise for the reader. But I will encourage you to be thoughtful about it. There isn’t necessarily a perfect approach, but there are plenty of ways that are guaranteed to fail.
Here are some actual approaches I’ve had from people at events:
A self-proclaimed “ecosystem leader” who rudely interrupted an obvious conversation that I was having with a young founder, positioned his back to the founder, and then proceeded to declare how influential he was in the ecosystem and that we should find time for a conversation
A founder who physically blocked me from walking onto a stage (while I was holding a microphone) and insisted on trying to pitch me despite my saying multiple times, “I have to go on stage”
A founder who followed me into a bathroom, stood beside me and attempted to pitch me while I was doing my business (that really does happen…)

In general, people who attend networking and other startup events are there to meet and talk to others. So if you’re patient, polite and just the right amount of assertive, chances are you can talk to almost anyone at an event. If only for a few minutes…
5. Make Your Move
You’ve patiently waited and finally have the opportunity to talk to the person you’ve had your eye on. What’s next?
If you’re doing any sort of prospecting, your goal is actually not to pitch the person on the spot. Rather, it’s to get their contact information so that you can have a proper 1-1 conversation later. Events are loud (at least, the good ones are). It’s hard to hear people and you frequently get interrupted. As such, it’s essential that you are concise.
Make your elevator pitch and see where the conversation goes. If the person shows interest, ask if you can get their contact information to follow-up later. By preempting your own pitch with an early ask, you signal respect for the person’s time and, in doing so, are more likely to get a ‘yes’ than if you gave them an extended pitch. At this point, they might happily give you their contact info or they might ask more questions (in which case, you can dig in deeper if you choose).
The other benefit of making the ask early is that you can be more efficient with your time. The faster you make the ask, the sooner you’ll close the “sale”. And the sooner you close the sale, the sooner you can move on to your next prospect.
(On the other hand, if your goal is quality over quantity, then by all means engage the person in a deep, lengthy conversation about whatever topic you have in mind.)
6. Watch for Yes
If someone offers you the close — i.e. they offer to share their contact information with you — take it. Even if you’re not ready.
It’s not uncommon for someone to interrupt your pitch during an event in order to preemptively offer you their contact information. I do it all the time. It usually goes something like this,
“This sounds great. Why don’t you send me an email and we can find time to continue the conversation later.”
Many times, founders are so focused on their pitch that they fail to recognize that the person they’re talking to just said yes and they continue pitching. By not watching for yes, they miss the signal in the response.
When someone interrupts you to preemptively offer their contact information, they’re not only saying “yes”, they’re also saying, “I want to end this conversation.” There could be any manner of reasons why they want to move on, but the critical piece is that they gave you a yes. If you fail to catch the double-meaning — and graciously cut off the conversation while taking their contact information — it’s possible they won’t offer it a second time. And you might ultimately lose the opportunity.
Also be prepared for the yes to come in a form you weren’t expecting. For example, you might ask for an email address and they might instead offer you their phone number or a LinkedIn QR code. Whatever form they offer, you should take it. Here’s an actual conversation I had with a founder recently:
Founder: “Can I have your email address?”
Me: “You already have it. The invite for tonight’s event came from my actual email…just hit reply and email me there.”
Founder (pulling out phone): “Ok, but can I have your email address?”
Me: “You already have it. The invite for tonight came from my actual email…just email me there.”
After the founder asked for a third time, I shrugged and said no.
That might seem harsh, but if someone has to repeat themself more than once, it’s generally a signal that you’re not listening (and as an investor, it’s not a great signal). So always remember, if you want people to say yes, you have to listen to them.
I’m sure that more than a few of you have made it to this point and are thinking “wow, Chris really overthinks things,” or “this all seems a bit over-calculated.”
You certainly don’t have to meticulously plan out each and every event you attend. By all means, show up to some events and just have fun. But if you take a few minutes to consciously set a goal for each work-related event you attend and then “debrief” with yourself afterwards (did you meet the goal? why or why not?), you’ll soon discover that you’re navigating events with far more intentionality and effectiveness than you were before.
And as a founder, every little bit helps.
Why Do VCs Make Startups Pay Their Legal Fees?
Why do VCs ask founders to pay their legal bills? How common is this practice and what should you do about it?
One of the most annoying surprises many founders encounter during fundraising is when they finally get a term sheet, only to discover a clause buried towards the end specifying that the startup must pay the investor’s legal fees.
WTF…?
This moment of shock happens so often that, every few months, a new thread pops up on social media decrying the widespread practice.
The initial post is inevitably followed by a pile-on of founders and armchair pundits dunking on greedy VCs. Then come the proud interjections of “founder-friendly” investors bragging about how they don’t make founders pay their legal bills (“not like those other guys…”).
What’s the deal here? How common is it for VCs to make founders pay their legal bills? Why is that even a thing (and what should you do about it)?
Why Do VCs Ask Founders to Pay their Legal Fees?
Let’s start off with the basic question of why VCs do this to begin with.
Don’t VCs have a lot of money?
If a VC is putting $5M into my company, why do they need me to pay $25K for their lawyers?
Venture capital firms actually have two distinct budgets:
1. The fund budget (the money a VC invests in companies)
2. The operating budget (the money a VC uses to operate the firm)
Whenever we talk about the size of a VC (e.g. “VC X is a $100M fund” or “VC Y is a billion-dollar firm”), what we’re referring to is the fund budget. Most founders are shocked to discover that the operating budget for a typical venture capital firm is only a tiny fraction of the fund size.
The majority of VC firms have only one source of revenue: management fees (the fees that a VC charges LPs to invest and manage their money). The standard management fee for VCs is 2% per year. Let’s do the math on that:
A VC managing a $100M fund has an annual operating budget of $100M x 2% = $2M / year
A VC managing a $250M fund has an annual operating budget of $250 x 2% = $5M / year
A VC managing a $1B fund has an annual operating budget of $1B x 2% = $20M / year
(For the purposes of this post, I’m not going to worry about billion-dollar funds — since those are pretty healthy budgets) — instead, I’ll focus on the more typical-sized funds that you’ll encounter as a founder.)
If a $100M VC firm did 8 deals each year that incurred $25K in legal fees, they would be paying 8 x $25K = $200K / year in deal-related legal fees. If they paid those fees from their operating budget, it would be about 10% of their annual budget. That’s a lot for any business — especially one that has no ability to increase it’s revenue.
Cry Me a River — Why is This My Problem?
I know, I know. This probably feels like me asking you to play a very teeny, tiny violin for the “poor, starving” VCs. But if you step back for a moment, what we’re really talking about is balancing budgets.
I promise you that VCs don’t like paying legal bills any more than founders do. All of the VCs I know would much rather spend their limited operating budgets on finding and supporting founders than paying lawyers. They also don’t want you to do it.
Seriously.
The last thing any investor wants to do is hand you a bunch of money and have you turn around and spend it all on legal bills. In most situations, that’s not helping anyone win (except maybe the lawyers).
What if I told you that for all the bluster, this isn’t strictly about VCs getting founders to pay their legal fees?
It’s about two things:
Getting the LPs who invest in VCs to pay their legal fees
Getting the prior shareholders who invested in the company to pay their legal fees
How VCs Get LPs to Pay their Legal Fees
I mentioned before that most VCs have limited options when it comes to increasing their revenue. But there are two ways that they can offload these expenses.
The most straight-forward way of doing this is to bill the legal fees back to their LPs as a “fund expense”. In venture capital, fund expenses are the costs of running and managing the fund, which include management fees, administrative costs, legal and accounting fees, and due diligence expenses. In other words, a VC firm can simply pass along the legal fees to the VC fund and get reimbursed. Case closed.

From a founder’s perspective, this is perfect. But it’s not ideal for the VC, for two reasons:
It directly reduces the amount of “investable capital” that the VC has (i.e. the amount of money that a VC has available to invest in startups).
The VC has no control over the scale of those legal expenses.
Many founders presume that if the legal diligence and closing costs get too high, then it must be the fault of the VC. But there are many reasons outside of the VC’s control that can lead to unusually high legal fees, including:
Inexperienced legal representation for the startup
Complex cap table situations that need to be resolved as part of the funding
Amendments to preexisting legal documents that need to be made
Multi-country complexities
IP issues
(One could obviously argue that a VC should know what they’re getting into before legal closing starts, but this isn’t always the case — particularly if a founder left out crucial details or didn’t realize that a particular situation might cause problems during closing.)
Which leads to the second option: offload the legal fees to the company.
How VCs Get their LPs and a Startup’s Shareholders to Pay their Legal Fees
When a VC asks a startup to pay their legal fees, this is what’s actually happening.
A VC can effectively transfer money from their fund budget to their operating budgeting by (1) investing in a startup and then (2) having that startup pay for something on their behalf.

Where do the startup’s other shareholders come in? By virtue of the effective dilution caused by those legal fees being shared across the cap table.
When our hypothetical VC invests $5M in a company and then asks that company to pay $25K in legal fees, the company only ends up with $4.975M. That’s $25K that could otherwise be used to generate a return for shareholders (which includes the incoming VC and all preexisting shareholders — founders, angel investors, other VCs, etc.).
More precisely, the payment of those legal fees results in a loss of value of the startup immediately following the close of the round of $25K (the money paid to the VC’s lawyers from the company’s bank account), which translates into a proportionate loss in the portfolio of each of the startup’s shareholders.
e.g. if our hypothetical startup has a post-financing cap table that is comprised of of 20% New VC, 15% Prior VC, 10% angel investors and 55% founders, then the effective loss of value incurred by each of those groups is:
New VC: -$5,000
Prior VC: -$3,750
Angel Investors -$2,500
Founders: -$13,750
By virtue of this strategy, the VC gains two benefits:
They offload their legal fees to both their LPs and the startup’s other shareholders (without directly reducing their investable capital).
They provide a “soft incentive” to control the overall legal fees (as everyone would now share the pain of out-of-control legal fees).
One More Thing…
There’s one additional (subtle) point to make about this that might not be apparent:
Regardless of how their legal fees get paid, the VC will ultimately end up paying a proportion of the startup’s legal fees (by virtue of the fact that those fees are typically charged after the round closes).

One could argue that the incoming VC will have taken into account the value of the startup post-legal fees when negotiating a valuation, but that’s never actually the case. So if each side ends up with $25K in legal fees — which isn’t unheard of — those fees are proportionately paid by all of the shareholders:
New VC: -$10,000
Prior VC: -$7,500
Angel Investors -$5,00
Founders: -$7,500
(For the VC, this is still very much a win, but it’s not quite the “slam-dunk” that folks who argue about this practice being founder-unfriendly might have you believe.)
What About the VCs Who Don’t Make Startups Pay Legal Fees?
I mentioned at the start of this post that whenever a social media thread on startup legal fees gets going, it inevitably becomes a “me too!” list of VCs bragging about how they don’t do that.
Guess what? A lot of those investors are Pre-Seed VCs. And almost all Pre-Seed VCs invest on SAFEs.
In other words, many of the VCs bragging about how they don’t make founders pay their legal fees generally don’t incur any legal fees when they make new investments.
When I was a partner at Panache Ventures, we did not charge founders legal fees related to our investments. We could do that without reducing our investable capital because almost all of our deals were done on a standard SAFE with a standard, pre-written side letter. Occasionally, we would incur legal fees when some peculiarities arose in the deal or we were following another lead in an equity round, but those were typically a drop the bucket of our operating budget and not worth passing along (to either the startup or our LPs).
To say it differently, a Pre-Seed VC bragging that they don’t charge founders legal fees is like someone puffing their chest after buying you lunch — when all you ordered was a $3 coffee.

“I insist…”
There are absolutely some VCs that don’t ask startups to pay their legal fees, but it’s still relatively rare (and mostly done by established firms with more substantive operating budgets and/or larger funds).
Tips for Founders
Let’s wrap this post up with a few quick tips:
You should expect VCs to ask you to pay legal fees on equity rounds. Generally, this starts at Seed or Series A.
If it’s your first equity round, the costs should be relatively low (as most countries have standardized agreements). Of course, this assumes that you’re coming in with a relatively straight-forward situation.
Most term sheets that ask you to pay legal fees have a cap. That’s good for everyone.
Most reputable legal firms offer fixed pricing for early fundraising rounds.
Make sure your legal team has experience working with startups. Nobody wants you to end up with a giant legal bill because of inexperienced lawyers marking up standardized documents.
If an investor asks you to pay their legal fees on a SAFE round, it may be a red flag. Ask them why they included that clause.
If a Pre-Seed VC wants to do an equity investment instead of a SAFE round, ask if they’re willing to pay the associated legal fees (I personally have no qualms about Pre-Seed equity rounds, but if you’re in a competitive situation where the other offers are all on SAFEs, don’t be afraid to bring this up).
Last but not least, if you’re really annoyed by this, you can always ask the VC to increase the round size to neutralize the effective dilution. Usually, this is a small fraction of the round size — so it might not be the hill to die on if there are other, larger issues to negotiate — but it’s certainly an option.
Bottom line, this practice is neither completely innocuous to founders nor is it a nefarious plot hatched by greedy VCs to take advantage of them.
At the end of the day, the goal on all sides is to get across the finish line and get back to building your business. And everyone wants you to have as much money as possible to do that.
VCs are Changing Their Tune on Conflicts
VCs generally do not invest in startups that compete directly with existing portfolio companies. But that norm is changing.
Founders and investors aren’t always on the same page.
But for most of the history of Startupland™, there has been one industry norm that both sides agreed on: in general, VC firms do not invest in startups that compete directly with existing portfolio companies. In fact, most VCs go to great lengths to ensure that (1) there are the no direct competitors in their portfolio, and (2) there is enough “room” between portfolio companies to allow them to pivot without risk of running into one another.
I previously wrote about this norm in a post titled Don’t Talk to Your Competitor’s Investors. The post walks through the historical reasons for this norm (both moral and legal), while noting that,
“The best investors don’t want to be in a position of conflict. They don’t want to have to choose between your company and their portfolio company, so the moment they sniff an overlap, they’ll pump the brakes.”
But the tides are changing and this long-accepted norm may soon be a thing of the past.
Last week, Charles Hudson of Precursor Ventures suggested that, with multi-stage funds getting larger and larger, the tradition of venture firms not investing in competitive companies may soon go away:
“As venture fund sizes keep getting larger, I do think that the tradition of venture firms having a norm (if not a stated policy) to not invest in competitive companies is likely to go away. This is simply a function of the fact that as venture funds have grown larger, it has become increasingly essential for those firms to be associated with the biggest and most important companies. The larger the fund, the more important it is to be an investor in the companies that are true outliers; there is no way to make the fund math work if you are not in those companies unless you are in other, similarly-situated companies. My sense is that there is more money chasing outliers at the moment than there are outlier companies to fund.”
Charles goes on to suggest some approaches that large funds can take to reduce the impact of such conflicts-of-interest, though he also notes that, “this is an issue where the business model for funds is at odds with what most founders want.”
His post focuses mostly on the dynamics of large multi-stage funds, but smaller funds and single-stage specialists are also starting to rethink their approach to competitive investments.
Why the Change of Heart?
Before you rush to the conclusion that this shift is simply another case of greedy VCs behaving badly, it’s worth noting that a couple of significant changes have happened in the past few years that fundamentally change some of the assumptions underpinning venture capital portfolios:
1. Companies are Staying Private Longer
Venture capital firms have historically been built on an assumption that most exits would occur within 7 - 10 years. Over the past decade, that number has crept higher, as many businesses have chosen to stay private longer. Add to that the many macroeconomic shocks we’ve had in recent years, and its increasingly common for early-stage VCs to hold positions in their winners for 15 years or more.
Think about what you were doing 15 years ago.
In my case, Aster Data was raising its Series C (it wouldn’t be acquired for almost another year — and DataHero wouldn’t be founded for a year after that). The cloud wasn’t really a thing yet. Neither Stripe nor Snowflake had been founded. And peer-to-peer anything hadn’t caught on.
So yeah…
2. Technology is Changing Faster
Step back and think of everything that has come into being technologically speaking over the past 15 years. Now think about how much faster innovation is happening as a result of AI.
In the past, it was reasonable (and, in many cases, prudent) for an early-stage fund to remain steadfast in its commitment to avoiding portfolio conflicts even after 10 years. After all, the fact that a company survived to its tenth birthday suggested that it was probably doing well. Moreover, a slower rate of change of technology implied that a new startup entering the same sector was likely to be a genuine competitor.
Things are different now. Even if two companies with an age gap of 10 years are likely to be competitive from a sector standpoint, chances are their technologies, target personas, and value propositions are fundamentally different.

3. Startups are Pivoting Sooner
A third major shift that’s occurred as a result of AI is that startups are able to validate (or invalidate) concepts sooner than ever before. It’s now increasingly common for investors to back a company, only for the founders to pivot within months of the investment closing.
In the past, it might take a company 6 - 9 months to determine that its original hypothesis wasn’t going to work, and then another 3 - 6 months to come up with something new. Today, startups can achieve both of those in a single quarter. In addition, we’re seeing early-stage startups pivot further away from their original ideas, making it harder than ever before for VCs to ensure adequate “space” between portfolio companies.
At this point, some early-stage VCs are investing with the presumption that the original idea will fail. They’re backing strong teams, but with no real idea of what the ultimate product will be (an approach founders typically love, but one that can result in unintended consequences — especially when it comes to portfolio conflicts).
4. Companies are Living Longer
Last but not least, many more startups that failed to achieve product-market fit have found ways to survive longer than ever before. Historically, if a VC-backed company didn’t achieve its goals, that company would either be acquired or shut down. Today, we’re seeing many more companies transition into long-term sustainable (but slower growing) businesses. While that can be great for the founders, it’s not necessarily the outcome investors signed up for.
The problem occurs if a company has changed trajectories to one that no longer fits the VC business model, yet the founders expect their investors to continue to uphold a moratorium on investing in potential competitors.
What Can Be Done?
First off, I agree with Charles’ assertion that the norm of VCs not investing in competing companies is going away. As a former founder, I hate this. But as an investor, I understand it.
From the perspective of multi-stage funds, they simply have to chase extreme outliers, portfolio conflicts be damned. Mega funds will increasingly do this until it’s widely-accepted behavior (hopefully, with some of the best practices Charles suggests).
On the other hand, I think that most early-stage / single-stage investors continue to believe that “the norm of not investing in competitive companies [is] a feature, not a bug” (I sure do!). The best Pre-Seed and Seed stage VCs are so involved with their portfolio companies that any conflict — real or perceived — is going to cause problems. So my assertion from two years ago — “the best investors don’t want to be in a position of conflict.” — still holds true.
That said, it’s no longer pragmatic for early-stage investors to think about conflicts in such absolute terms. Especially not over a 15-year horizon.
As we look ahead, I think there are some practical approaches that Pre-Seed and Seed-stage VCs can take to reasonably mitigate conflicts and maintain strong founder relationships, while future-proofing their ability to make reasonable new investments. All of which require clear, transparent communication with founders. For example:
Adopting an “expiration date” policy for avoiding portfolio conflicts — Instead of having a blanket moratorium on investing in competitive companies, consider a policy that expires after a certain amount of time or under certain conditions (e.g. no material forward progress in 36 months). The goal here isn’t to abandon companies that are struggling or to normalize “do-overs” (though I’m sure some investors will do that). Rather, it’s to provide clear guidelines as to when the investor might reasonably consider a competitive investment. Conceptually, this is closer to a standard employment non-compete (which founders and investors alike are very familiar with).
No guarantees in the case of a pivot — This is a touchy one for founders, but from an investor’s perspective, it can be challenging to support a competitive moratorium after a startup makes a significant pivot. Especially if the VC is not confident in the pivot (or in the team’s ability to execute the pivot). Early-stage VCs generally have little control over a startup deciding to pivot. Most still want to back their portfolio companies after a pivot — at a bare minimum, they have a financial incentive to do so — but if the pivot is into an area that the founding team has no prior experience in, it’s not unreasonable for the investor to want to keep their options open.
No guarantees below a minimum ownership — This is another one I’ve seen cause problems (in both directions). On the one hand, I’ve seen founders squeeze investors down to an inconsequential amount of ownership, only to expect that VC to not invest in competitors. On the other hand, I’ve seen VCs intentionally write small scout checks, then use the information they gain to make large investments in competing companies. Making clear the expectations in both directions will go a long way towards a smoother, long-term relationship.
Interestingly, I think that founders will broadly “get over” a shift in behavior by multi-stage funds and that conflicts within early-stage funds will end up being more prominent. (We generally don’t expect good service from Chase or Comcast, so we’re not disappointed when our experience sucks.) Conflicts within smaller funds — particularly those known to be more “founder-friendly” are where we’re likely to see the drama.
How investors choose to adapt their policies on competitive investments — and how transparent they are about those policies — may very well become a future marketing point. Regardless, founders should absolutely ask potential new investors what their current policy is on investing in competitive companies, how they view that in light of pivots, and whether or not they expect it to change in the future.
Some final thoughts from Charles:
“Most founders lack significant “hard power” (i.e., the right to block an investment) in these negotiations; funds can and do invest in competitors if they choose to do so. However, there will always be a set of founders who possess soft power and will utilize it to encourage their investors not to engage in such behavior. The universe of founders with meaningful soft power to influence this is very small, but that universe of founders is very powerful.”