Can This Be Canada's "San Francisco" Moment?
Could Canada’s productivity crisis serve as the breaking point for a tech industry that historically stayed out of politics?
To say that the past few months have been rough when it comes to productivity sentiment in Canada would be an understatement.
If you haven’t spent any time north of the 49th recently (or read/listened to any Canadian news media), then you’d be forgiven for assuming that everything in Canada was as happy as a polar bear chugging maple syrup while waiting for the puck to drop on the 2024 NHL playoffs.

Did I miss the opening face-off?
But for the last six months, the focus of much of Canada’s business community has been on an expanding productivity crisis in the country. Things came to a head last week, when the governing Liberal party released their 2024 budget. It included a significant increase in the federal capital gains tax that was immediately met with an uncharacteristic tsunami of opposition from business and tech leaders across the country.
Could this moment serve as an inflection point for the relationship between tech and politics in Canada?
How Did We Get Here?
Coming out of Covid, most countries saw productivity increase as companies found their footing and identified ways to leverage new technologies and modes of operating. Canada, however, experienced the inverse. This chart from a November report by BMO’s Chief Economist highlights the contrast in productivity between Canada and the U.S. post-pandemic:

The implications have been significant:
As a result, Canada has steadily drifted down the relative productivity rankings in the OECD. Not only have the Nordic economies moved well north of Canada, along with the U.S., but so have most of Western Europe and Australia.
Our closest comparables are Italy and Spain; feel free to draw your own conclusions.
Beneath the hood, a dramatic drop in real GDP per capita is wreaking havoc with Canada’s productivity. After 25 years of tracking the U.S. on this measure, a gap began to open in 2015 that has ballooned post-Covid:

The continued increase in real GDP per capita in the United States is very much the result of positive developments south of the border — so we should give credit where credit is due. The issue for Canada is not that it’s southern neighbors are pulling ahead — it’s that Canadian productivity has been effectively flat since 2017.
Lighting a Match on a Tinderbox
The volume of discourse around Canada’s drop in productivity has grown significantly louder over the past six months.
In March, the Senior Deputy Governor of the Bank of Canada, Carolyn Rogers, proclaimed that the need to improve productivity had reached an emergency level,
“You know those signs that say ‘In an emergency, break the glass?’ Well, it’s time to break the glass.”
Then last week, a report was released showing a stark increase in Canada’s public sector employment post-pandemic, and contrasted it with a slowing rate-of-growth in the private sector and an effectively flat level of entrepreneurship:

Suffice to say, people in tech took notice:


Two days later, the Liberal party released their annual budget, with a significant increase in the federal capital gains tax front and center.
The Backlash
Personally, I wasn’t at all surprised that the Liberal Party chose to introduce a capital gains tax in this budget. For left-leaning parties, increasing capital gains taxes (or, at least, announcing a desire to do so) is a common tactic used to curry favor with their base — especially in the lead-up to a difficult election. President Joe Biden announced his own intent to increase capital gains taxes in the U.S. only a month ago:

The difference between these two announcements is that President Biden wasn’t attempting to increase capital gains taxes in the shadow of a national productivity crisis and an ongoing debate about how to better support the innovation economy. To say that Canada’s Minister of Finance failed to read the room on this would be an understatement.

Capital gains tax. Saving democracy since 1972.
Thus far, Minister Freeland has failed at her attempts to convince the tech community to get on board. In an interview with The Globe and Mail, she claimed that the decision to increase the capital gains tax was based on extensive research showing that there would be no adverse impact on startups and the innovation economy. But the academic literature she cited actually supported the opposite conclusion, including:
“evidence about the long-run economic impact of higher capital-gains taxes are mixed and not easily quantified.”
“economic analysis confirms the adverse effects of higher capital gains taxes on the creation and success of young enterprises.”
“a 2005 European Central Bank analysis of 14 countries found a lower corporate capital-gains tax rate increased the share of venture capital investment in early-stage high-tech enterprises.”
“a 2019 study of 32 countries found that higher capital-gains taxes leads to a reduction of startups receiving venture capital in a statistically and economically significant way.”
What Does This Have to Do With San Francisco?
Frequent readers of The Quiet Part Out Loud are forgiven for rolling their eyes and wondering why I’m referencing San Francisco yet again (and what SF could possibly have to do with a Canadian federal budget).

In the days after the budget was announced, the reactions and discussions I saw across WhatsApp channels, email threads and Zoom calls reminded me of the discourse flowing through the Bay Area a few years ago:
People talking about leaving Canada / how to leave Canada / where to go for tax reasons
Founders talking about moving their startups to the U.S.
People from across the political spectrum expressing frustration with a government that had been in power for a long time and had become more idealogical in its actions
Sound familiar?
It was only a few years ago that San Francisco was being similarly left for dead. Prominent VCs and other tech leaders were loudly proclaiming that the government was failing and making sure that everyone knew it on their way out the door.

The media narrative was increasingly one of a dystopian city spinning out-of-control in a doom loop that could only lead to failure.
But…

Amidst all the negative sentiment, an innovative and resilient tech community — one that was historically ambivalent to politics — hit its breaking point. Born-and-bred San Franciscans like Garry Tan of Y Combinator and SF transplants from around the world, like Zach Coelius, decided they had had enough.
And they started to mobilize.
In less than 2 years, San Francisco has gone from being left for dead to ground zero for the AI revolution. (Oh…and most of those folks who loudly slammed the door on their way out have quietly come back). It’s by no means back to its former glory, but the vast majority of people I know went from all-but-writing San Francisco off to being long San Francisco (at least, publicly 😉).
Could This Happen in Canada?
This brings us to the question posed by the title: can this be Canada’s “San Francisco” moment?
Outside of lobbying efforts, the majority of Canada’s tech leaders have historically stayed out of politics. But in recent years, we’ve seen a handful of former entrepreneurs cross over, such as Vancouver’s new Mayor, Ken Sim, and British Columbia’s Minister of Jobs, Economic Development and Innovation, Brenda Bailey.

Archive photo of BC’s “JEDI” Minister (seriously…is that not the coolest job title ever?)
But we haven’t yet seen this at a federal level in Canada.
A big part of this is that Canada’s parliamentary system doesn’t provide the same direct openings that the U.S. political system offers for new entrants. You can’t simply declare that you’re going to run for Prime Minister, for example, so there aren’t Canadian equivalents of Michael Bloomberg or Ross Perot.
But could that ever change? What would it take for more successful, experienced tech leaders to enter Canadian politics?

The tech industry has always been very diverse when it comes to political ideologies, so this isn’t about left or right. It’s about pragmatism vs. ideology.
As I watch the shift happening in San Francisco right now, I see the weight and influence of the tech industry slowly pulling the city back from political extremes that did not reflect the majority of the city’s population. San Francisco isn’t suddenly becoming conservative — it is and has always been one of the most progressive cities in the U.S. — it’s simply becoming more functional and sustainable.
Canada has the same opportunity.
Regardless of the reaction to the recent budget and the results of the next election, Canada isn’t suddenly going to become a conservative country — it has always been a progressive beacon for the world — but Canada is a country that at its best balances business, economic and social interests for the betterment of all.
Regardless of your political beliefs, if we want Canada to remain competitive in the long term and maintain its standing as an example for the world, we simply can’t afford to sacrifice innovation and competitiveness in the name of ideology. As the world continues to become more competitive, the countries that continue down that path will lose.
Perfectly Creamy Scrambled Eggs
The secret to perfectly creamy, silky-smooth scrambled eggs is patience.
Scrambled eggs are one of the simplest dishes to make, but almost everyone does it wrong:
Scramble the eggs, cook over medium-to-high heat, done in 3 minutes. The result? A rubbery, dry, pile of eggs.
The secret to perfectly creamy, silky-smooth scrambled eggs is patience — in this case, 30 - 40 minutes of patience (the perfect amount of time to listen to a Saturday morning podcast). And it’s absolutely worth it.
(P.S. These perfectly creamy scrambled eggs have no added cream 🤫.)
Perfectly Creamy Scrambled Eggs
Serves: 2
Preparation time: 3 minutes
Cooking time: 30-40 minutes
Ingredients
4 - 5 eggs
Salt and pepper
2 tsp fresh dill, chopped fine (optional)
2 tbsp unsalted butter
Preparation
Crack the eggs into a bowl and beat them with a whisk or fork until the yolks and whites are just starting to combine (you don’t want to beat them until smooth).

Season with salt and pepper (and, optionally, chopped dill).
Place a nonstick skillet over medium heat for about a minute. Add the butter and swirl it around until it just melts, then turn the heat to low.
Add the eggs and cook over low heat, stirring occasionally with a spatula.
Nothing will appear to happen at first. Resist the urge to increase the heat — this is normal. After about 10 minutes, the eggs will begin to form curds.

Continue to cook the eggs on low, stirring every few minutes to break up the curds.

The process might feel like it’s taking forever, but don’t give up! As the curds form, the scrambled eggs will take shape — but with a far creamier texture than you’re likely used to.

After 30-40 minutes, you’ll have perfectly creamy scrambled eggs. Instead of a lump of dry rubber, the result of cooking low and slow is a mixture of soft, silky smooth curds.
Serve immediately.

Velocity: One Metric that Matters Most
As an early-stage investor, velocity is the #1 thing I’m trying to measure when I meet with founders.
One phrase that you frequently hear in the startup world is “one metric that matters” (OMTM). It refers to the concept of focusing everyone in a company on a single metric, such as users, downloads, leads or revenue. For early-stage startups, rallying around a single metric can provide tremendous focus on a journey that’s filled with decisions and distractions.
But more than revenue. More than users. More than any other metric a company can measure, there’s one attribute that has a bigger impact on the success or failure of a startup than anything else: velocity.
And as an early-stage investor, it’s the #1 thing I’m trying to measure when I meet with founders.
What is Startup Velocity?
Let’s start with a definition of startup velocity:
Startup Velocity is the rate at which a startup achieves its milestones.
It’s that simple. How quickly can a startup achieve the goals and objectives necessary to move the company forward?
Here are a few examples of the many milestones an early startup might need to achieve:
Building an initial prototype
Launching a website
Signing 5 pilot customers
Hiring a developer
Getting the first $1 of revenue
Raising a round of funding
If we’re measuring velocity in days or weeks, it might seem obvious to directly tie a startup’s velocity to the number of hours you work each day. But startup velocity is far more than just hours worked (a nuance that many adherents to startup “hustle” culture get wrong). Velocity is not only about how hard you work, it’s about how you work.
At a fundamental level, startup velocity is a measure of a company’s sense of urgency.
Are You Playing to Win?
When I meet a founder for the first time, this is one of the key questions going through my head.
Are you playing to win?
Not win your city. Not win your country. Not win your initial market.
Are you playing to win the whole damned world?
Many years ago, I was at an event where Tobi Lütke, the founder of Shopify, was asked to describe the difference between Canadian entrepreneurs and American entrepreneurs.

His answer perfectly captured the key cultural advantage that American’s have when it comes to entrepreneurship:
“Canadian entrepreneurs aim to be the best in Canada. American entrepreneurs aim to win the world.”
If your goal is to build a world-changing, globally impactful tech company, you have to behave as though you’re competing against every other founder on planet Earth who is trying to solve the same problem you are.
If you understand that your competition is global from day one, the importance of startup velocity is evident.
(It’s also why one of the questions that’s always in the back of my mind as an investor is “Can you beat my friends?”)
Where is Your Benchmark?
When you’re in a race, everything is relative.
If you can run a 10-minute mile, you’re the fastest person in the race if everyone else takes 12 minutes. But you’re dead last if the rest of the field can do it in 8. As a founder, you need to be cognizant of (and intentional about) who you’re comparing yourself to.
This is one area where founders in cities with smaller startup communities and/or more laid-back lifestyles are at a disadvantage. If everyone around you is kicking back working a 9-to-5 job or running a lifestyle business, you might think you’re the hardest working team in town. But how does that compare to what’s going on in a top-tier ecosystem? How does that compare to your actual competition?
Marvin Liao recently wrote a great post titled, Steel Sharpens Steel: Picking your Tribe and Environment on the impact of being surrounded by ambitious people. In it, he includes a response that famed VC Bill Gurley recently gave to the question of where he would start a company today:
“Place can be very impactful. If I were a 22-year old founder starting something [today], I’d go to Silicon Valley just because it would increase your odds of success. I think many cities — whether it’s Austin or Miami — they have a problem that sounds ironic. They are a lot of fun. And so there is a question whether you attract the very most determined founders.
I think there are a lot of contagious qualities to successful startups. Constantly being around other people all in the same game is super helpful.”
The lesson here is not that every company needs to move to San Francisco. But if you’re a tech founder, you need to benchmark against what companies there are doing. Moreover, if you’re not in Silicon Valley, you need to be intentional about surrounding yourself (either physically or virtually) with other high achieving founders.
How Do You Measure Velocity?
When it comes to measuring startup velocity, I’m not talking about using formulas. The journey of every startup is unique, so it’s difficult to make a true apples-to-apples comparison.
I tend to can look at velocity from a binary perspective: a startup is either high velocity or it isn’t.
In my experience, the velocity of a startup generally follows the tendencies of the founding team. If the founders are high velocity individuals, the company tends to develop a high velocity culture (and vice versa). So when I meet with founders, I’m looking for signs that they are high velocity individuals.
Here are some examples of behaviors that signal a high velocity founding team:
Very responsive in communication (answers emails, texts, etc. very quickly and does so at all hours of the day)
Proactive in communication (reaches out whenever a question or issue comes up, rather than waiting for the next scheduled interaction)
Communication style often includes deadlines (e.g. “I’ll get back to you with this on Wednesday” vs. “Let me get back to you on this”)
Milestones are specific and measurable
Works on multiple milestones in parallel (e.g. reaching out to prospective customers and building pipeline while product is still in development)
Ruthlessly protective of their time
Schedules important meetings/calls within hours or days
Willing to travel on extremely short notice when necessary
Incorporates new ideas/information very quickly
And here are some examples of behaviors that can signal a low velocity founding team:
Takes weeks to schedule important meetings/calls
Unwilling to schedule important meetings/calls outside of their personal business hours (evenings/weekends, different time zones, second-tier/regional holidays, etc.)
Describes milestones in a strictly linear fashion and/or with unnecessary gates between steps (e.g. not willing to start selling the product until a particular feature, approval, etc. is complete, even when that completion date is known)
Over-engineers product / unwilling to release in beta until everything is done
Struggles to get employees to work outside of normal business hours, even in cases of big deadlines
Easily distracted by stories in the media / spends too much time comparing to others (especially when it comes to fundraising)
Spends too much time at conferences, speaking engagements, panels, etc. (when those things aren’t core to GTM)
Overly focused on customers / users / competitors in their local market / resistant to expanding beyond local market
Resists incorporating new ideas/information
Neither of these lists are exhaustive. Very few founders do all of the items in the first list. And almost all first-time founders do some of the things in the second list. But they’re signals.
The more signs I see that support a sense of urgency / high velocity, the more likely I’m going to lean in as a potential investor. On the other hand, the more signs I see that lead me to believe that you might not have that sense of urgency, the louder the voice in the back of my head gets worrying that you’re not going fast enough.
To be clear, as a founder you absolutely, unequivocally do not need to be high velocity if building a globally-impactful company isn’t your goal. There’s nothing wrong with taking another path. But in my experience, a high velocity founding team — and, thus, a high velocity startup culture — is absolutely a necessary (but not sufficient) condition to create a billion-dollar company. That’s why it’s so important to me as a VC.
I’ve met many smart, experienced founding teams with unique insights, great products and who on-paper looked like stellar investments. But as I got to know them, the nagging voice in the back of my head got louder,
“They’re not going fast enough…”
I’ve also met founding teams that didn’t have it all figured out, but were iterating and progressing forward at such a high rate that felt inevitable that they would figure it out.
Guess which teams I invested in?
The Best Kale Salad You've Ever Had
If you’ve been struggling to eat kale straight out of a bag hoping to be healthy, I’m here to save your salads.
It seems like you can’t go anywhere these days without seeing kale on the menu, and with good reason. Kale is one of the healthiest ingredients around. It’s high in vitamins A, C and K, is full of axioxidants that help fight inflamation, and can even act as a natural detoxifier for your body.
The only problem? If it’s not prepared correctly, raw kale tastes bitter and has a fibrous texture that can be off-putting to even the most diehard health nut. If you’ve been struggling to eat kale straight out of a bag hoping to be healthy, I’m here to save your salads!
Thankfully, preparing kale correctly takes only a few seconds. Once you learn to do it right, there’s no going back.
And what makes this both the best kale salad you’ve ever had and one that you’ll add to your regular meal rotation?
Two things:
It’s made with Your Favorite Ingredients™
You always have those ingredients ready-to-go
Before we jump into the recipe, it’s helpful to understand the basics of what makes a good salad, so that you can be sure you’ve got the right ingredients ready.
The Basics of a Good Salad
A good salad combines multiple ingredients from each of the following categories:
Textures
Flavors (sweet, salty, umami and, potentially spicy and/or bitter)
Healthy food groups (proteins, vegetables, grains, healthy oils, beans and/or fruits)
Colors (because you eat with your eyes!)
Making sure that your salad has at least three different items from each category will give you a delicious, complex and incredibly healthy meal every single time.
It’s worth noting that how a particular ingredient fits in will often depend on how you prepare it. For example, a protein like chicken can be neutral in flavor (plain grilled chicken), sweet (e.g. teriyaki chicken) or spicy (e.g. cajun chicken). Similarly, garbanzo beans / chickpeas can provide a soft texture if they’re boiled or a crunchy texture if they’re fried.
Here are some of my favorite ingredients to use, by category:
Textures
Soft: avocado, cherry tomatoes, goat cheese, queso fresco, fish, boiled eggs
Hard: strawberries, red pepper, prawns
Crunchy: croutons, sunflower seeds, fried chickpeas, green beans, snap peas
Flavors
Sweet: berries, tomatoes, avocado, bourbon braised smoked tofu, dried cranberries
Salty: seasoned croutons, parmesan cheese, anchovies, caesar salad dressing
Umami: steak, salmon, sesame oil, teriyaki / soy sauce
Spicy: blackened / cajun chicken, jerk chicken
Bitter: Coffee-crusted steak, broccoli, asparagus
Food Categories
Proteins: chicken, salmon, steak, prawns, tofu, boiled eggs
Vegetables: snap peas, asparagus, red pepper
Fruits: cherry tomatoes, avocado, blueberries, strawberries
Beans: edamame beans, black beans, green beans
Grains: croutons, sunflower seeds, corn, puffed quinoa
At the bottom of this page, I’ve included a selection of my favorite salads. So let’s get into it:
Kale Salad
Serves: 2 as a main / 4 as a side
Preparation time: 10 minutes
Ingredients
1 bunch of curly kale
2 tbsp extra-virgin olive oil
Your Favorite Ingredients™ (see below for suggested recipes)
Preparation
Remove the kale leaves from their stems and tear into bite-sized pieces. Place the kale leaves into a large bowl and discard the stems.

The key to a good kale salad is to massage the kale with extra-virgin olive oil, which breaks down the fibrous leaves, thus softening their texture, while removing the natural bitterness of the kale.
To do this, pour the olive oil over the bowl of leaves and then use your hands to gently massage the kale. As the olive oil coats the kale leaves and you massage them, you will noticeably feel the texture change after 1-2 minutes. There should be just enough olive oil and the leaves get coated (and your hands feel oily!) but not so much that it pools at the bottom of the bowl.

Let the kale sit for 5-10 minutes after massaging — this is when you slice, dice and prepare the rest of Your Favorite Ingredients™.
Once you’ve got everything ready, assemble your salad as follows:
1. Take ⅓ of each of Your Favorite Ingredients™ and add them to the bowl with the massaged kale leaves.
2. Drizzle your salad dressing of choice overtop of the bowl. Note: if you are making your own oil-based dressing, remove 1 tbsp of extra-virgin olive oil to account for the extra oil already in the salad.
3. Mix the ingredients together and divide into serving bowls.
At this point, your salad dressing should be nicely mixed in with the kale leaves and a portion of Your Favorite Ingredients™. You’re probably wondering, “Why did we only add ⅓ of Your Favorite Ingredients™?”
When you add all of the ingredients to a salad before mixing, they fall down to the bottom of the bowl (you know what I’m talking about 😉). As a result, you end up with a salad that doesn’t deliver balanced, multi-textured bites. By mixing ⅓ of each of Your Favorite Ingredients™ into the salad and plating the rest on top, you end up with a salad that looks and eats like it should.
Which leads to the final step:
4. Evenly distribute the remaining ⅔ of Your Favorite Ingredients™ on top of the salads, in the following order:
Soft and hard ingredients first (vegetables, fruits, etc.)
Crunchy ingredients next (croutons, seeds, etc.)
Protein third
Herbs or garnishes last
Doing this takes only a minute or two, but it ensures that each and every salad you make is truly the best kale salad you’ve ever had.
(And yes, I do this every time I make a salad — just ask my coworkers.)

Suggested Recipes
Here are examples of kale salads with my Favorite Ingredients™ (each recipe serves 2 mains, as above):
Kale Caesar Salad with Blackened Chicken
1 bunch massaged curly kale (as above)
1 blackened or cajun-spiced grilled chicken breast, sliced
½ avocado, cubed
12 cherry tomatoes, halved
½ cup garlic croutons
⅓ cup caesar salad dressing (if making from scratch, I love this recipe)
¼ cup shredded Parmesan cheese
6 anchovy fillets (optional)
Kale Salad with Bourbon Braised Smoked Tofu
1 bunch massaged curly kale (as above)
2 cups Bourbon Braised Smoked Tofu
½ avocado, cubed
12 cherry tomatoes, halved
½ cup garlic croutons
½ cup boiled or grilled corn, removed from cob
½ cup boiled edamame beans, removed from shell
Combine 2 tbsp of the BBQ sauce from the tofu with 1 tbsp of extra-virgin olive oil and squeeze of lime juice for the dressing
Kale Salad with Coffee-Rubbed Steak
1 bunch massaged curly kale (as above)
1 NY striploin, crusted in bourbon smoked chili & coffee rub and grilled medium-rare, sliced
½ avocado, cubed
12 cherry tomatoes, halved
½ cup blueberries
½ cup red pepper, diced
½ cup garlic croutons
Balsamic vinaigrette (1 tbsp extra virgin olive oil + 2 tbsp aged balsamic vinegar + salt & pepper, to taste)
Kale Salad with Pan-Seared Duck Breast
1 bunch massaged curly kale (as above)
1 pan-seared duck breast, sliced
12 cherry tomatoes, halved
½ cup blueberries
½ cup red pepper, diced
¼ cup dried cranberries
½ cup garlic croutons
Orange-balsamic vinaigrette (1 tbsp extra virgin olive oil + 2 tbsp aged balsamic vinegar + orange zest + salt & pepper, to taste)

Kale Salad with Bourbon Braised Smoked Tofu
How to Diligence a VC
Plenty of posts have been written about how investors diligence startup founders, but how can founders diligence VCs?
Plenty of posts have been written about the process VCs use to diligence startups. Heck, I’ve written a bunch myself. Like this one. And this one. And this other one. But what about the inverse? As a founder, it’s easy to get so caught up in the ultimate goal of fundraising — to raise money — that you forgot or run out of time to learn more about the source of the funding.
But it’s essential that you diligence potential investors before they end up on your cap table.
If things go well, you’ll likely interact with them week-in-and-week-out for 10 or more years. Even more significantly, you’ll have to work with them when things aren’t going smoothly (something that’s guaranteed to happen). Your choice of investors will impact the direction of your company and your journey as a founder, so it’s essential that you understand who they are and how they conduct themselves.
Here are 5 tactics you can use to diligence a VC:
1. Ask for References
The bare minimum you should do in terms of diligence is to ask potential investors for references from founders they’ve previously backed. Of course, this is like asking a potential hire for references — they’re only going to introduce you to people who will say amazingly positive things about them.
You should still talk to those founders and ask them about their experiences. You may be surprised by how candid they are. Then take it one step further: ask the VC for references to founders of companies they previously backed but which ultimately shut down.
The goal here is to understand not only how helpful the VC is when times are good, but how they work when things get tough. Pay attention to how an investor responds to this request. The best VCs will gladly make such introductions. The worst will make excuses.

(Note: The absolute best VCs will offer an introduction to any founder in their portfolio. Don’t be afraid to take them up on it.)
2. Talk to Former Founders
You wouldn’t be doing your diligence if you only talked to the references that a VC gives you. The next step is to find your own. Luckily, there’s an app for that.
Imagine if the next time you considered getting into a long-term relationship, you had a list of every one of that person's ex's and could call any of them to ask anything you wanted to. That's what Crunchbase is for founders.

You can literally go online and find each and every company an investor has previously invested in. Look for companies that not only had success, but also shut down. Then reach out to the founders.
Fun fact: while investors typically use warm introductions as a way to filter requests, 99.99% of founders will respond to a cold email titled “Founder Looking for Diligence on <X>” (if <X> was someone on their cap table). Every founder who’s ever raised capital understands the information imbalance inherent in fundraising and are more than happy to help even the odds. They’ll sing the praises of the investors who helped them the most, spill the tea on those who wronged them, and help you to understand the nuances in how a given investor operates.
To this day, I get cold emails from founders asking about investors in my previous companies (and that was more than a decade ago).
3. Ask Your Existing Investors to Backchannel
Getting the real story on a VC is one area where your existing investors can help. A lot.
Both angel investors and VCs spend a considerable amount of time meeting and getting to know other investors. So even if they don’t have first-hand knowledge of a particular VC, they should be able to get multiple points of reference for you.

Your existing investors have a vested interest in helping you to bring the right partners on board, so leverage each and every one of them to backchannel on your behalf.
4. Reach Out to Later-Stage Investors
In the course of your founder journey, you’ve likely come across investors that you were too early to raise from. In some cases, you might have had multiple touch points and have started to develop a relationship with them (aka a “dotted line”).
If they’re genuinely interested in your company, then they’ll also have an interest in seeing you raise from strong early investors (albeit not as significant an interest as your existing investors).
If you’ve started to build a relationship with one or two later stage investors, don’t be afraid to reach out and ask, “We’ve got a term sheet from <X>. Curious what your thoughts on them are?” The answers can be enlightening.
5. Trust Your Gut
Above anything else, trust your gut. If something seems off about your interactions with a potential investor, don’t be afraid to call them out on it. Or add it to the list of questions to ask other founders about.
At the end of the day, if something feels like a red flag, it probably is. This is your company. And your future.
Perfect Yogurt Parfait
What if I told you that you could have ice cream for breakfast every morning, and it would be one of the healthiest breakfasts possible?
What if I told you that you could have ice cream for breakfast every morning, and it would be one of the healthiest breakfasts possible?
That’s the pitch my wife made to me years ago, and believe me, I was skeptical.

Then she pulled it off.
The trick? Using flavored liquid stevia as a sweetener.
Yogurt has an incredible number of health benefits. The problem is, plain yogurt tastes pretty awful. Flavored yogurts taste great, but contain a significant amount of added sugar. And while there are some low-sugar flavored yogurts on the market, they often include a host of ingredients that normally wouldn’t find their way onto a yogurt label.
By taking your favorite, healthy plain yogurt (cow milk, sheep milk, or greek yogurt — for extra protein) and adding a few drops of vanilla-flavored liquid stevia, you instantly have healthy breakfast magic.
With incredible tasting vanilla yogurt as your base, you can then top with your favorite fruits or berries and, optionally, granola.
(Speaking of which, if you happen to find yourself in Montreal, I encourage you to visit La Finca and pick up a jar of their homemade granola. I have no idea what kind of French Canadian black magic is in that stuff, but it’s absolutely addictive. Just don’t have too much, or you’ll completely negate the low-sugar premise of this entire recipe 😂.)
Perfect Yogurt Parfait
Serves: 1
Preparation time: 5 minutes
Ingredients
1 cup plain yogurt (cow milk, sheep milk, greek yogurt, etc.)
2-3 drops of vanilla liquid stevia
½ cup berries or other sliced fruit
½ cup granola (optional)
Preparation
Combine yogurt with 2-3 drops of vanilla liquid stevia in a serving bowl.
Top with fruit and optional granola.
Enjoy!

Things I Think I Think - Q1 2024
The frost of winter is finally thawing and spring is upon us. Will the tech market begin to open up like early spring flowers?
The frost of winter is finally thawing and spring is upon us. Will the tech market begin to open up like early spring flowers?

In homage to sports columnist Peter King, who announced his retirement last month, here are 5 Things I Think I Think - Q1 2024 Edition:
1. Canadian Fundraising is Springing Back to Life
In my Q4 2023 thoughts, I observed that Canadian founders had largely come to terms with the shift in market conditions and predicted that we would see the Canadian fundraising market return in the first half of 2024.
If Q1 is any indication, we’re well on our way.
At Panache, we saw the largest number of companies presented to our investment committee in a single quarter since 2022 (this a key step in our investment process: when a partner shares a prospective investment with the entire Panache team).

As with any good Canadian winter, the level of activity was relatively slow until the end — the bulk of fundraising activity in Q1 took place towards the end of the quarter. January was a slow month across the country. By mid-February, early-stage fundraising activity had started to pick up. By the time spring was within sight, the level of activity had increased dramatically — March 2024 was easily busier than any single month we had observed since 2022.
That said, the resurgence in fundraising activity has not been equal across the country. Toronto-Waterloo experienced by far the most significant pickup, with the majority of early-stage deals in Canada taking place there. Vancouver and Montreal also saw an increase in fundraising activity, but not nearly to the extent that Toronto-Waterloo did. At this point, I expect their recoveries to lag Toronto-Waterloo by a quarter or two. The rest of Canada remains relatively nascent — while there certainly many companies in the Prairies and Atlantic Canada that kicked off fundraising processes in Q1, the uptick in those regions was not nearly as prominent as in the rest of the country.
Overall, the increase in domestic fundraising activity is a strong signal for the Canadian tech sector and bodes well for a strong Q2 across the country. From my previous quarterly update:
Assuming that the level of geopolitical conflict remains relatively contained, I would expect a strong (but not mind-blowing) Q1 in the Canadian private markets, followed by a notable uptick in Q2 as we head into the summer.
2. Series A is Still Glacial
While early-stage funding is rebounding around the world, Series A activity remains frozen solid (outside a handful of notably hot sectors). Two things appear to be happening:
Funds that specialize in Series A investments are being extremely cautious coming back to market, with many still remaining on the sidelines.
At the same time, multi-stage funds that leverage Series A investments as an entry point are reducing their rate of new investments at Series A in favor of doubling down on their winners at Series B and C.

I’ve spoken with dozens of Pre-Seed and Seed VCs in the past month and almost everyone is seeing the impacts of these dynamics on their portfolio companies:
Strong companies that previously raised Seed and/or Series A funding from multi-stage funds are increasingly fielding preemptive term sheets from inside investors for Series B and C rounds
Many companies that did not previously raise from multi-stage funds are struggling to generate momentum for Series A and later rounds
While most Series B and later companies had prepared themselves for a difficult 2024, many companies that had planned to raise their Series A funding in Q1/Q2 2024 are instead having to look at ways to extend their runway in order to delay fundraising into the back half of the year.
The longer-term risk here is that if the Series A freeze continues beyond the summer, it will start to propagate back to earlier stages — as Seed funds are forced to bridge more companies in their portfolios. I personally don’t expect that to happen — especially if both the early-stage and Series B+ markets continue to accelerate — but companies that are planning to raise Series A funding anytime in 2024 would be well advised to consider backup plans, just in case.
Note: Within the context of the dynamics described above, the eagerness of multi-stage funds to preempt rounds in their portfolio winners is unfortunately leading to bad behavior on the part of some VCs. I know of multiple companies who had existing investors issue preemptive term sheets, signed those terms sheets (thus delaying a full-blown fundraising process), only to have those investors renege on their commitment.
Let’s be clear here: absent the discovery of something materially negative during diligence, pulling a signed term sheet is already amongst the worst behaviors a VC can do. Pulling a signed term sheet from a company that you’re already an investor in is completely, absolutely, utterly inexcusable.

3. The Great Shutdown is Underway
In my Q3 2023 update, I predicted that we would see a lot of startups who raised their last round of funding during the ZIRP heyday of 2020-2021 but failed to achieve product-market fit close their doors. Q4 saw the beginning of that prolonged period of startup closures, a movement that accelerated in the first quarter of 2024.
But there’s a glimmer of light amidst the darkness of this incredibly difficult time for many founders: a significant number of failed startups are being acquihired.
For founders who started off with billion dollar dreams, the idea of an acquihire can be a difficult pill to swallow. But compared to shutting down the company completely, an acquihire can potentially be very lucrative for both founders and employees.
The reason this development is somewhat surprising is that, last year, the acquihire market for early-stage startups was ice cold. Going into 2024, the general consensus was that acquihires would remain few and far between. Large tech companies were continuing to shed headcount while the overall hiring market’s pendulum was clearly swinging back towards employers. As a result, most smart people (including yours truly) predicted that there would be little-to-no demand for failed startups.
It turns out that there remains a significant number of large and growing tech companies that are thriving and continue to place a premium on top performers — and top-performing teams. These outcomes won’t have a material impact on investors, but if this trend continues, we’ll see fewer outright shutdowns and less resulting doom-and-gloom across the tech sector.
4. AI Sliding Into the Trough of Disillusionment
Last quarter, I noted that we were entering a period of calm before the AI storm. We’re now well on our way into the AI trough of disillusionment.

Need proof? Think about how quickly the discourse around any new AI release flips from “this is so cool!” to “look at all the things that are broken”. Need more proof? A lot of generative AI startups that were funded in late-2022 / early-2023 on the back of unprecedented hype are quietly closing their doors.
“But Chris,” you say, “I keep hearing about generative AI startups that are raising massive Seed and Series A rounds at nonsensical valuations. How can we be headed towards the trough of disillusionment if there’s still so much hype around AI companies?”
One fascinating side-effect of the AI industry moving so quickly is that a visible split has developed in terms of the perception of where it is on the hype cycle depending on your vantage point. For early-stage investors like myself, it’s clear that we’re past peak hype and are already seeing many of the early generative AI startups wash out. In contrast, many later-stage investors are currently swimming in hype (just last week, Gary Survis of Insight Partners — a well-know later stage VC fund — shared his view that the generative AI market is currently at peak hype).
Regardless of vantage point, we’re barreling towards the part of the cycle where it’s crystal clear that a lot of the early hype was overblown. At the same time, there are an incredible number of well-funded companies that are quietly working with customers, refining their products and value propositions, and preparing their go-to-market strategies.
In the short term, expect the punditry about how overblown the hype of AI is to get really, really loud. But the real value is coming.
5. I Left My Wallet in El Segundo
While the hype around generative AI is starting to quiet, the noise around hard tech is reaching Stanley Cup final decibel levels. And El Segundo, California is ground zero.

Today, we’re seeing renewed interest in hard tech on a number of fronts:
Global conflicts shining a spotlight on defense tech
A reversal of globalization driving interest in supply chain and energy technologies
A new golden era of space accelerating research into communications, manufacturing and transportation technologies
A growing focus on climate change accelerating research into climate and sustainability technologies
A few weeks ago, I wrote about this emerging hard tech renaissance and the reasons why Canada risks missing out. One aspect I didn’t dig into in that post — but which I expect to have a significant impact on where the winners in these fields will ultimately emerge — is the growing “American dynamism” movement.
The term American dynamism entered U.S. tech vernacular as the result of a 2022 essay authored by a16z General Partner Katherine Boyle (there is now an entire section of a16z’s website dedicated to the theme). The essay served as a siren’s call to builders who not only wanted to focus on hard tech, but wanted to advance the national interests of the United States.
And many across the country have answered the call.

There is an incredible amount that one could unpack about this growing movement and its emergence in a period of increasing political and cultural conflict both within the U.S. and internationally. From a purely economic standpoint, I suspect that we may look back at this period as a key inflection point in the resurgence of manufacturing and productivity in the United States. If only a fraction of the companies that are being built in America today around hard tech themes reach their potential, the economic impact will be absolutely massive.
Founders and investors around the world — even those who don’t fancy themselves in “hard tech” — should pay close attention to what’s happening in the U.S. right now. Never underestimate the multiplier that deeply felt nationalism can be on the drive and velocity of already highly-motivated founders. That, plus massive amounts of funding and government support.
Is It the Government's Job to Fund VCs?
There are strong economic arguments for governments to help foster the creation of new venture funds to support their startup ecosystems. But how should they approach this?
Earlier this week, OG Canadian investor Matt Roberts wrote a lengthy post on the history of Canadian pension funds and their declining support of Canadian VCs, titled “Who Killed Canadian Venture?” The epic post clocks in at nearly 8,000 words and dives into three main topics:
A history of the Canadian Pension Plan (Canada’s equivalent of the U.S. Social Security system)
The evolving investment strategies of CPP and other major Canadian pension funds, like the Ontario Teachers Pension Plan (OTPP) and the Ontario Municipal Employees Retirement System (OMERS)
The impact of changes in government investment regulations on Canada’s VC ecosystem — specifically, the elimination of mandates that pension funds invest a minimum amount of their capital into Canadian companies
Matt’s post is incredibly well researched and touches on some of the key debates currently surrounding public pension funds, notably the tension between maximizing fund performance vs. leveraging those funds to drive domestic economic development. If you’re in any way, shape or form interested in Canadian venture capital or private equity, I recommend you give it a read.
All of that said, I must admit that I disagree with Matt on one of the underlying premises of his post: that it is the role and responsibility of public pension funds to subsidize the Canadian venture capital ecosystem.

Some Things I Think
I believe that, all things equal, government-affiliated investors should default to investing domestically.
Of course, this shouldn’t be contentious. (And it isn’t.) The Chief Investment Officer of the Healthcare of Ontario Pension Plan (HOOPP), Michael Wissell, said as much in a statement to Matt,
“…all else being equal, we prefer to invest in Canada when the risk and reward are appropriate.”
Where I diverge with Matt is on what the appropriate expectation should be when investment opportunities are not equal. Should a public pension fund be required to invest in a domestic company — say, a VC fund — when that investment is objectively worse than a comparable investment in an international company?
I don’t believe so.
While I believe wholeheartedly that government can — and should — play a role in encouraging new business creation across all industries (more on that later), I disagree with the notion that a public pension fund should be forced to make investments for reasons other than driving financial returns.
In that respect, I share the perspective of Jim Leech, the former CEO of Ontario Teachers’ Pension Plan,
“You’ve got to create the opportunities. It isn’t forcing or enticing people into Canadian investments, it’s providing sufficient good investments in Canada.”
Broadly speaking, pension funds have a singular goal: to maximize the performance of the fund for the benefit of their pensioners. John Ruffolo, who founded pension-backed OMERS Ventures in 2011 and is now the Founder and Managing Partner of PE fund Maverix, recently echoed this sentiment,
“I’m not in favour of mandating pension allocations,” John shared with Betakit this week, “…the world-renowned success of Canada’s pension funds is the singular focus of their mandates: to get maximum returns on their retirees’ money.”
Demanding that a pension fund do anything other than maximize performance is akin to imposing a tax on the pensions of each-and-every person who stands to benefit from the fund. Nobody would think it reasonable to force a 5th grade teacher from Mississauga to pay a tax to support her local VC. Why is it any more acceptable to force the Ontario Teachers’ Pension Plan to do so?
Adapt, Evolve, Compete or Die
American hedge fun manager Paul Tudor Jones famously used this phrase to describe the need for traders to constantly evolve as markets change, and it very much applies to venture capital funds. Our industry is, by definition, intensely competitive. We have to compete with other investors for the privilege of investing in the most ambitious startups we meet and we have to compete with other asset classes to raise investment dollars from potential LPs.
For VCs in Canada, that level of competition has increased significantly in recent years as Canada’s tech ecosystem has continued to reach new heights. Canada’s tech ecosystem today is amongst the best in the world and Canadian startups are second-to-none. As a result, the amount of venture capital money flowing into Canada from around the world — and from Silicon Valley in particular — is greater than it’s ever been.

Sauron’s eye is turning north…
We can choose to look at this development in one of two ways:
It’s a good thing, because ambitious Canadian founders are attracting the best investors from all over the world
It’s a bad thing, because ownership of Canada’s fastest-growing companies (and the subsequent returns generated by those investors) is leaving the country

While there are valid economic considerations for (2), as a former founder, I very much align with the first perspective on this and consider it to be a hugely positive shift for Canada’s tech ecosystem. More capital — and more high-value capital — is flowing into Canadian startups, whose founders no longer need to restrict their search for investment to funds located above the 49th parallel.
Of course, that makes my job immensely more difficult than if the most competitive VC funds in the world politely left their ambitions at the border. But that’s the nature of competition.
These days, Canadian founders are rightly looking me dead in the eye and asking, “why should I take your investment instead of one from XYZ Fund from San Francisco?” And potential LPs are looking at me dead in the eye and asking, “why should I invest in your fund instead of XYZ Fund in San Francisco?” And that’s happening to investors across the country.
And across the country, investors are adapting, evolving and competing. Where I’m based in Vancouver, Version One has established itself as one of the best micro funds in North America, investing in mission-driven founders in both Canada and the US. Active Impact Investments, which recently launched its third fund, is quickly becoming one of the world’s premier early-stage climate tech funds. And Evok Innovations, a growth stage clean tech fund, is leading investments in carbon, clean energy and minerals companies around the world.
But it’s a long, hard road to get there. And that’s where government can help.
Calling in the Reinforcements
Here are some of the ways that governments can support the development and maturation of their domestic venture capital industry without forcing that responsibility onto adjacent stakeholders:
1. Lower Barriers to Investing in VC
Governments can make it easier for individual investors in the private sector to opt in to supporting venture capital funds. Many countries (including Canada) impose restrictions around who can invest in venture capital funds, referred to as accredited investor requirements. Reducing and removing these barriers can unlock new sources of capital for venture capital firms and, as a result, startups.
2. Make it Easier to Create New VCs
Governments can support programs and take other actions that make it easier for new and diverse individuals to launch new venture funds. I’ve previously shared some ways that governments and industry groups can support the creation of new VC funds in this blog post.
3. Create Dedicated Government Fund-of-Funds
To the extent that governments want to subsidize venture capital funds through direct investment, they should create and maintain dedicated allocations of capital to do this. In Canada, many individual provinces have taken this approach and can act as anchor investors in new VC funds.
4. Entice the Private Sector to Invest in VC
Finally, governments can establish programs to entice the private sector to invest in domestic VC funds. In many jurisdictions, tax breaks are used by governments to encourage individual investors to invest in tech startups and other small businesses (e.g. QSBS in California, EBC in British Columbia and SEIS in the UK). Similar programs could be established to encourage LP investments into new and emerging funds.
At the end of the day, there are strong economic arguments for local governments to help foster the creation of new venture funds and the development of a healthy domestic venture industry. But they shouldn’t sacrifice the competitiveness of adjacent stakeholders — such as startups and public pension funds — in order to do this.
Cullen Skink
Cullen skink is one of my favorite dishes to eat when it’s cold. It’s a a traditional, Scottish chowder made with smoked fish (think “New England clam chowder, but with smoke fish instead of clams”).
If you’ve never been to Scotland, then you’ve likely not heard of cullen skink before. After haggis, cullen skink is undoubtedly one of Scotland’s most famous dishes. It’s a traditional, cream-based chowder made with smoked fish (think “New England clam chowder, but with smoked fish instead of clams”). The dish originated in the town of Cullen in the far north of Scotland. Today, it can be found on the menus of most pubs and restaurants across the country.
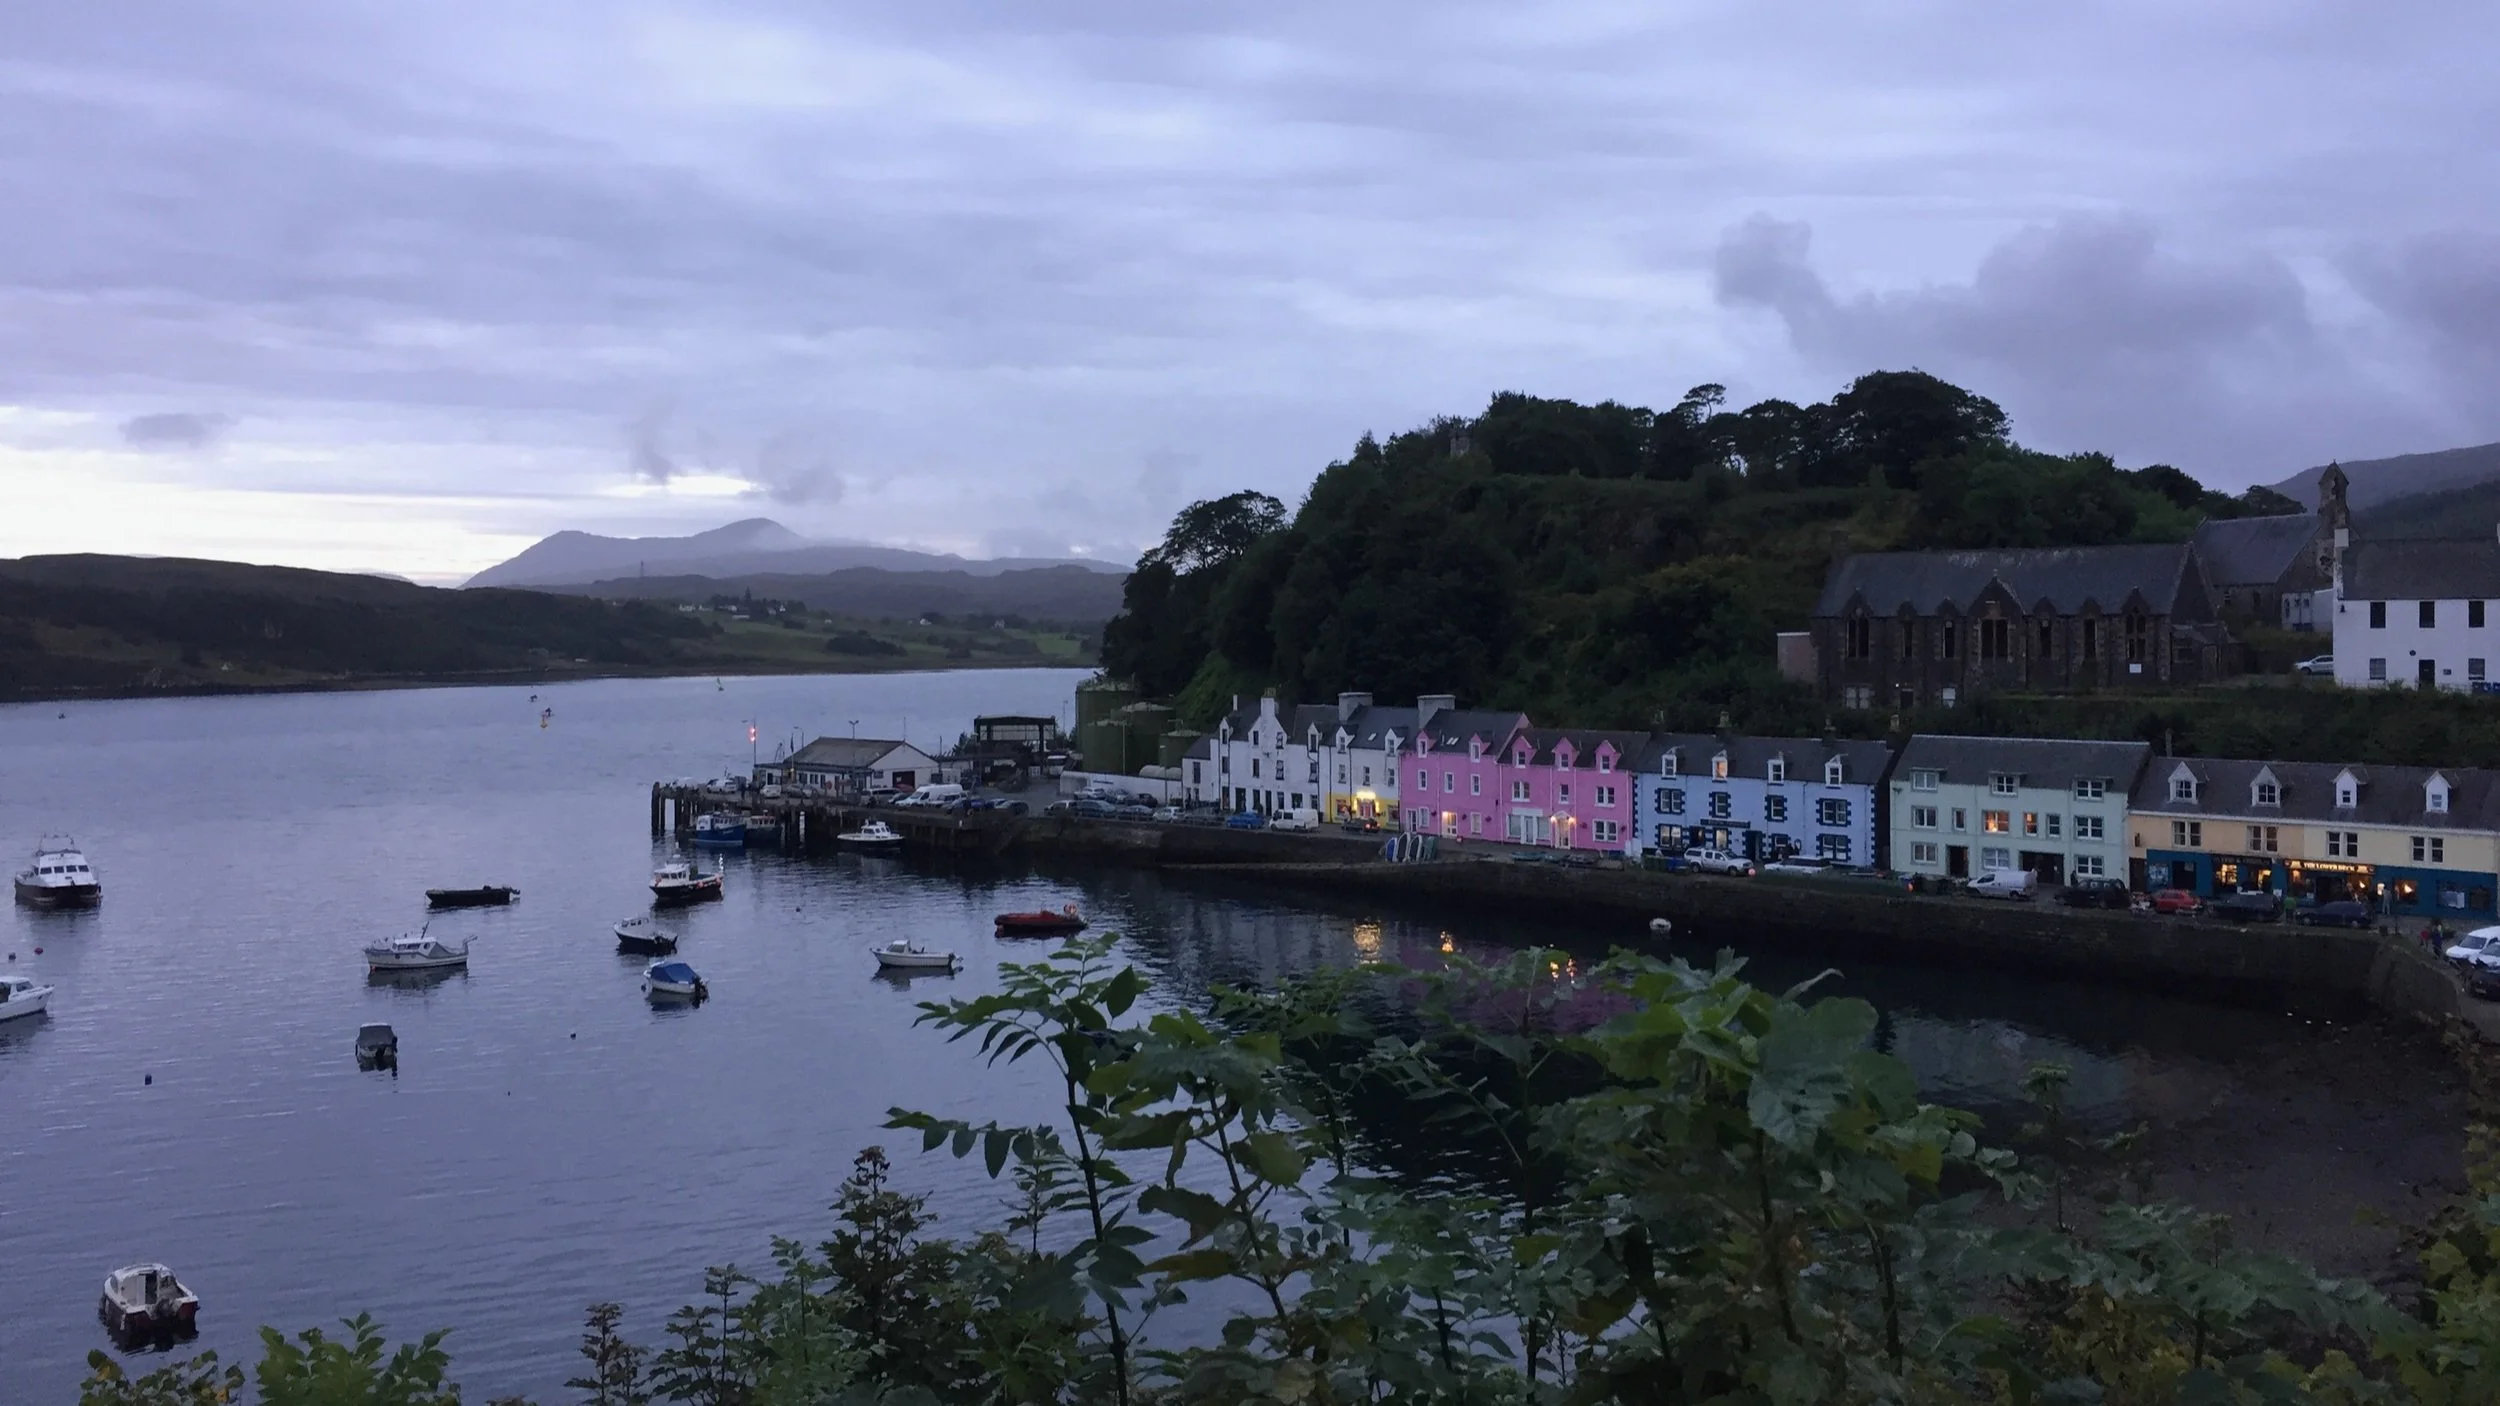
The majestic Isle of Skye
Cullen skink is one of my absolute favorite dishes to eat when it’s cold. Whereas New England clam chowder uses bacon to add a degree of smokiness to the soup, cullen skink gets it directly from the smoked fish. The depth of flavour that gets infused into the soup as a result is next level — even the best New England chowders don’t come close.
Traditional cullen skink is made with smoked haddock (known as finnan haddie in Scottish), an ingredient that’s incredibly difficult to find in North American. Thankfully, we have something on this side of the pond that can serve as a worthy substitute: smoked black cod.
Black cod (also known as sablefish) is one of my favorite ingredients from the Pacific Northwest (I’ve previously shared a recipe for miso-marinated black cod that you should definitely check out). Many seafood markets (and even grocery stores) carry smoked black cod, so it’s relatively easy to come by (though by all means, try making this dish with finnan haddie if you can find it).
Cullen Skink
Serves: 4 - 6
Preparation time: 10 minutes
Cooking time: 30 minutes
Ingredients
1 lb cold-smoked black cod (or finnan haddie — aka Scottish smoked haddock)
4 cups of whole milk
3 tbsp unsalted butter
1 medium yellow onion, diced
1 medium leek, diced thin (see Notes)
Juice from ½ lemon
1 lb Yukon gold potatoes, pealed and cut into ¼-inch cubes
½ cup of heavy cream
1 bay leaf
Kosher salt and freshly ground black pepper
Cholula (or another vinegar-based hot sauce)
Preparation
Pour the milk and bay leaf into a medium saucepan. Heat at medium-high until barely simmering and reduce the temperature to medium low (you want the milk to be barely simmering but never actively boiling, as that will dramatically change the flavor of the milk — and not in a good way).
Add the smoked black cod to the saucepan and cook the fish until it just barely starts to flake (5-6 minutes). The fish will significantly plump in size as it absorbs the milk and rehydrates.
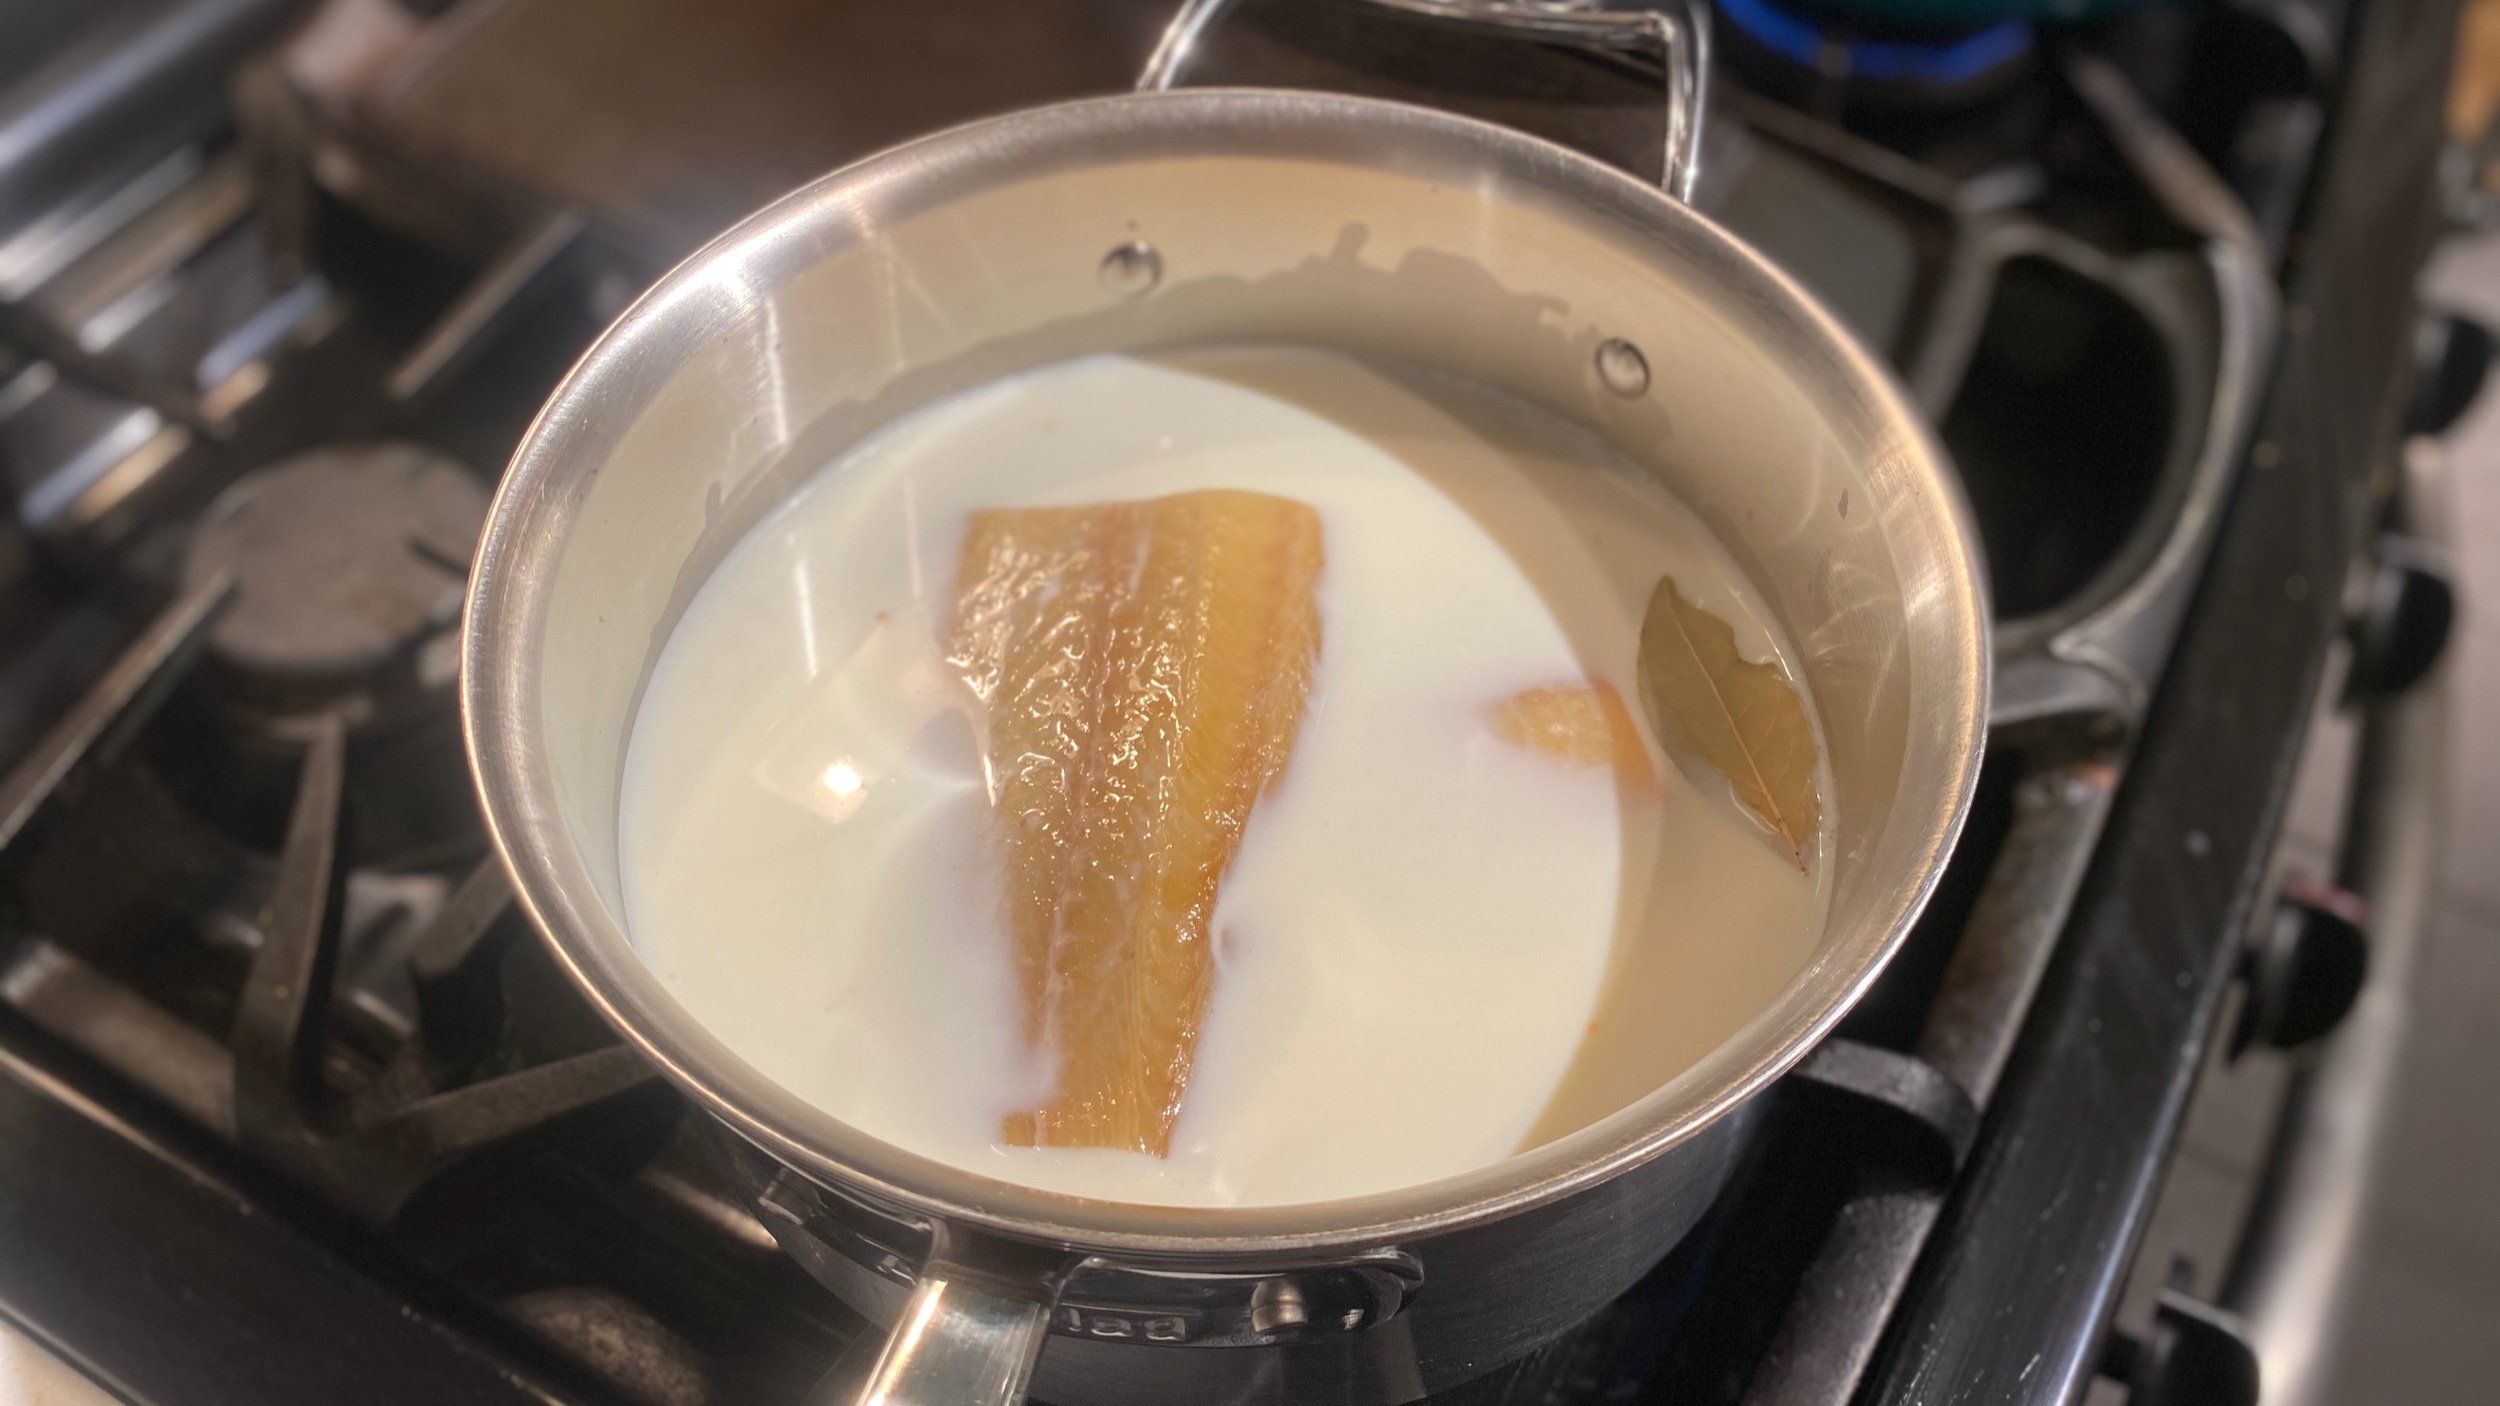
Remove the fish from the milk and place on a paper towel-lined plate to drain.

Remove the bay leaf from the milk and discard. Pour the milk into a heatproof bowl and set aside.
Place your Dutch oven or a large pot onto the stove and heat to medium-high (if reusing the same saucepan from before, make sure to thoroughly wash it before proceeding to this step). Heat the butter until it melts and stir in the onions and leeks.
Sweat the onions and leeks for about 10 minutes while stirring frequently. The longer you sweat the mixture down, the sweeter and more flavorful your soup will be. Reducing the heat if it starts to scorch at any point.

Add the lemon juice, several grinds of black pepper and 4-5 dashes of Cholula and sweat for 2-3 more minutes, stirring frequently.
Mix the potatoes into the pot and cook for 5 more minutes, stirring regularly. This will both infuse the potatoes with the flavor of the onions and leeks while helping to release some of the starch from the potatoes (which thickens the soup).

Pour the milk that was previously used to cook the fish into the Dutch oven and heat until it is just barely simmering (again, make sure it doesn’t boil). Cook until the potatoes are tender, about 10 minutes. Make sure to regularly stir and scrap the pot so that the milk does not scorch.
While the soup is simmering, peel the skin off of the fish and remove any bones. Pull the fish apart into bite-sized pieces (it should flake naturally) and set aside.

Once the potatoes are tender, use a potato masher (or a large wooden spoon) and press into the soup 4-5 times to crush some of the potatoes. The idea here isn’t to mash all of the potatoes. The goal is to break up a portion of them in order to get a variety of shapes and sizes while releasing more of the solids to thicken the soup.
Add the shredded fish and heavy cream to the soup and stir to combine. Let cook an additional 2-3 minutes and then season to taste with salt and pepper.

Serving
Serve immediately and top with chives.
Cullen skink can be kept for 2-3 days refrigerated.

Notes
The use of leeks adds a distinct sweetness to cullen skink. Some recipes omit the leeks to reduce the sweetness of the soup. If you find this recipe to be too sweet for your likely, feel free to omit the leeks.
How to Get the Best Out of Your Investors
The relationship between a founder and an investor can last 10 years or more. Just like any long-term relationship, you need to put in effort to stay aligned.
The vast majority of the content that has been written about founder-investor relations is about fundraising. That makes sense considering how important the outcome of a fundraising process can be to a startup. But if you think about it, the fundraising dance represents only a small portion of the relationship between a founder and an investor — one that can last 10 years or more. Just like any long-term relationship, you need to put in effort to stay aligned.
Here are 5 things every founder should do to more effectively manage investor relations in order to get the best out of your investors:
1. Send Regular Investor Updates
When I was a founder, I wrote weekly investor updates. Every Sunday night, I dutifully spent 1-2 hours in front of my computer writing them.
And you know what? I hated every minute of it. But it was one of the most important, impactful things I did as a founder.
Consistency breeds trust. And trust is one of the most important things a founder can develop with their investors. Moreover, sending regular investor updates ensures that all of your investors have context into the business, which places them in a much stronger position to help when you need it.
2. Hold Quarterly Check-in Calls
In addition to sending regular updates, schedule a check-in call with each of your investors every quarter. Not just the board members. Not just the VCs. All of your investors.
Many founders deprioritize communicating with smaller investors — particularly angel investors and early-stage VCs — as the business grows. This is a huge missed opportunity. On one hand, you only have so many hours in the day. On the other hand, your earliest investors are the individuals and firms who believed in you from the start. They tend to have the strongest emotional connection to your success and are generally the closest aligned to your goals as a founder. They might not have the largest financial stake in the company, but they’re often the ones most willing to roll up their sleeves when things get tough.
The best founders I know make a point of checking in with all of their investors on a quarterly basis. Part of this is customer success 101 — you want to make sure that your investors ❤️ still you — but it also helps to foster an unfair advantage in your corner. By staying top-of-mind with all of your investors, you increase the likelihood that they’ll opt in to helping you when you need it (whether that’s for introductions, feedback or more money).
3. Be Intentional with All Investor Communications
I can’t tell you how often I get a DocuSign link asking for a signature related to a company I’m an investor in without any context or advanced notice.

A couple of points here:
The first time I hear about a legal document shouldn’t be from your lawyer (unless I’m getting sued).
The first time I hear about a legal document shouldn’t be the moment you need a signature.
I received the above DocuSign link from the law firm of a startup that I’m an angel investor in, having not heard anything from the founder for more than 6 months. This kicked off a week-long email thread as I tried to come up to speed on the purpose of the legal document, its background context and the implications for me as an investor. The document ended up being completely innocuous, but the unnecessary back-and-forth wasted my time (and that of other investors), plus added weeks to the process.
It also put a spotlight on the fact that none of us had heard from the founder in months.
In the course of your founder journey, there will be countless legal agreements that you need to execute, many of which require investor signatures. Founders often spend so much time working on these documents with their counsel and board that they forget that every other investor needs time to review and digest the documents. If you don’t give everyone a heads-up, you’re likely adding 2-3 weeks to the process (plus making your smaller investors feel unvalued). In contrast, if you send all of your investors a quick email a couple of weeks in advance, you can manage any questions while the finishing touches are being put on the documents and have everyone lined up and ready to sign.
Imagine if, instead of receiving the DocuSign link above as my first touch point, I received this email from the founder:
Dear Chris,
I hope you’re doing well. Just giving you a heads-up that we’re working on X (which is going to require your signature). Here are the implications of X on you as an investor:
…
Feel free to reach out if you have any questions. You can expect to receive a DocuSign from Y in about a week.
(This took me 45-seconds to write…so there’s legitimately no excuse for not doing this.)
4. Don’t Outsource Your Investor Relations
Another common mistake I see founders make is trying to “outsource” investor relations to someone else in the organization (typically a chief of staff or business development role). Similar to (2), I understand the desire to do this — managing smaller investors can seem so far down the list of priorities as the company grows — but it’s an optimization that is rarely worth it.
Given that the CEO is the person responsible for all fundraising, each-and-every investor on your cap table ultimately made a decision to invest in you. Not your company. Not your product. You. Which means that once in a blue moon, that person or firm will want to hear from the CEO. And they deserve to. Notwithstanding particularly needy investors (and let’s be clear, those exist), you should continue to personally field emails and calls from every investor on your cap table — regardless of size — until the finish line.
The big picture cost is minimal — maybe a half-hour every six months. And the upside can be significant. There’s usually a reason beyond money why each investor is on your cap table. Remind yourself of that fact and you can often find the smallest of investors will continue to deliver outsized value for you and your company.
5. Assume Your Investors Talk to Each Other
Another mistake I see many founders make — particularly first-time founders — is that they presume that their investors don’t talk to one-another. While this is typically a reasonable assumption to make when it comes to angel investors (especially if they have no prior relationship), it’s hardly the case with VCs or board members.
By the time the ink is dry on your cap table, you should assume that most of your investors have spoken to each other.
This is not to say that your investors are plotting against you behind your back, but it’s important for you to keep in mind that back-channeling is happening regularly. Investors will often connect after board meetings to debrief on the proceedings or to get another perspective on significant changes in the business. They’ll also regularly speak on topics related to fundraising, investing and potential exits.
More often than not, these conversations are innocuous and beneficial to the business (in my experience, the most common topic of conversation between co-investors is how they can work together to support the startup). But keep in mind that these touch points exist, especially when managing sensitive communications.
Bourbon Braised Smoked Tofu
This delicious and easy-to-make recipe provides a memorable vegan/vegetarian option for BBQs and is great for anyone (it’s in frequent rotation at the Neumann household).
I do a lot of smoking, which typically entails making ribs, brisket, pulled pork and other meaty classics. But smoking isn’t only about meat. This delicious and easy-to-make recipe for Bourbon Braised Smoked Tofu provides a memorable vegan/vegetarian option for BBQs and is also great for anyone (it’s in frequent rotation at the Neumann household).
If you don’t have a smoker, you can prepare it in your oven (you just lose out on the smokey goodness).
Bourbon Braised Smoked Tofu
Adapted from Brown Sugar Kitchen by Tanya Holland.
Serves: 4-6
Preparation time: 5 minutes
Cooking time: 60 minutes
Ingredients
1 454g (1 lb) package of firm tofu
½ tsp kosher salt
½ tsp paprika
½ tsp onion powder
¼ tsp garlic powder
¼ tsp ground black pepper
¼ tsp dried oregano
¼ tsp dried thyme
1 cup bourbon BBQ sauce
2 cups water
Preparation
Remove the tofu from the package and gently press on all sides with a paper towel to remove the excess moisture. Cut into ¾-inch / 2-cm cubes.
In a large bowl, combine the salt, paprika, onion powder, garlic powder, black pepper, dried oregano and dried thyme. Add the tofu cubes and toss to coat.

Cooking
Prepare smoker at a temperature of 225 - 250ºF with a light wood (alder, apple, maple or hickory). This is the same temperature range you typically use for ribs, brisket and many other meats, so you can easily slide this into your smoker alongside other foods if you’re preparing a vegan option for a BBQ).
If you don’t have a smoker, preheat your oven to 225ºF.
Spread the tofu in a single layer on a grilling pan (or a baking sheet lined with parchment paper if you’re cooking in the oven).

Put the tofu in your smoker and cook until the tofu is infused with the flavor of the smoke — 25 - 30 min. If using an oven, cook the tofu for 25 minutes.

While the tofu is cooking, combine the BBQ sauce and water in a large sauce pan. Bring to a boil and then reduce to barely a simmer. Cook the mixture until it thickens (about 25 - 30 min). If you’re doing this right, the tofu and braising liquid will be ready at the same time 😃.
Remove the tofu from your smoker or oven. It should have a nice golden color.

Add the smoked tofu to the saucepan and simmer until the tofu is infused with the sweet, smokey flavor of the BBQ sauce.
Serve immediately.

Notes
For this recipe, you can use your favorite BBQ sauce or experiment with different flavors. Using a molasses-based BBQ sauce, for example, will give you a thicker, “stickier” sauce with a heavier flavor than using a ketchup-based sauce.
My favorite choice for this recipe (and most things) is bourbon BBQ sauce. This recipe from Meat Church is easy-to-make and, with a heavy dose of pepper, holds up well to smoked flavors.
Stop Trying to Replicate Silicon Valley
Along with death and taxes, one of the certainties of life is that every politician, journalist and armchair entrepreneur thinks that their city can be the next Silicon Valley.
A few weeks ago, I participated in a panel titled, “Building Realistic Ecosystem Dreams”. The goal of the session — part of a day-long conference focused on Alberta’s tech ecosystem — was to discuss and debate what a realistic future for the local tech ecosystem could be and how best to support it’s growth.
It was a fantastic conversation that covered a wide variety of topics. Of course, it was only a matter of time before someone asked the well-meaning but inevitable question,
“How can we make our tech ecosystem more like Silicon Valley?”

I’ve had the privilege of working with dozens of startup ecosystems around the world, and I can say from experience that along with death and taxes, one of the certainties of life is that every politician, journalist and armchair entrepreneur thinks that their city can be (and should be) the next Silicon Valley. There’s Silicon Alley, Silicon Beach, Silicon Slopes, Silicon Wadi, Silicon Glen…
You get the point.
While I completely understand — and support — the desire to build entrepreneurial ecosystems around the world, I’ve always found it odd how many people think it’s possible to replicate Silicon Valley. We don’t think that way about any other industry (when was the last time you heard someone ask, “How can our city be the next Wall Street?”).
Of course, there are plenty of organizations that are more than happy to sell the Silicon Valley dream to anyone who will listen.
“For the low, low price of [redacted], we can drop a shiny new ACME™ accelerator in your city and it’ll be instant success!”
…
“Well, no…we won’t actually invest in any of the companies that go through the program…”

So if we can’t replicate Silicon Valley, are there opportunities to leverage it to foster the growth of global entrepreneurial ecosystems?
Absolutely.
First off, despite my cynicism when it comes to replicating Silicon Valley, I believe wholeheartedly that there are lessons for other ecosystems to learn from Silicon Valley. In fact, that was the original premise behind the first generation of startup accelerators.
There have also been countless books written to encapsulate various aspects of Silicon Valley’s culture and best practices, from The Lean Startup and Zero to One to The Cold Start Problem and Secrets of Sand Hill Road. There’s also Brad Feld’s excellent book, Startup Communities: Building an Entrepreneurial Ecosystem in Your City and its follow-up, The Startup Community Way, both of which offer a cornucopia of lessons from “the Boulder Experiment” and its impact on startup ecosystems around the world.
Which brings us to the million dollar question: what can governments do to support local entrepreneurs if “bringing Silicon Valley to a town near you” isn’t the answer?
They can send local entrepreneurs to Silicon Valley.

“But wait,” you might be thinking, “don’t governments already do that…?”
Sort of.
Governments, corporates and other ecosystem supporters around the world have been sending entrepreneurs on tours of Silicon Valley for years (Canada was one of the pioneers of this, with the C100’s “48 hours in the Valley” program nearly 15 years ago). But that’s not what I’m talking about.
Last month, the Scottish government did something almost unheard of: they paid for 12 startups to relocate to San Francisco for a month as part of the country’s Tech Scalar program.
To be clear: the Scottish government didn’t pay for a startup tourism trip, as many governments do (“Next, we’ll visit Google’s cafeteria…”). Nor did they fly the entrepreneurs all the way to Silicon Valley only to make them sit through a program run by compatriots who travelled to Silicon Valley with them. Instead, they did something revolutionary: they gave the startups office space…and let them work.

It may seem like an exaggeration, but in backing this initiative, the Scottish government made a mental leap that few governments around the world have ever made: they stopped being scared that their entrepreneurs might stay in Silicon Valley and instead focused on the long-term benefit of helping them to work there.
The Scottish government successfully overcame a globally-shared insecurity that is deep within many countries’ cultures: a fear that, if given the opportunity to spend time in Silicon Valley, their entrepreneurs will choose not to return. While there’s definitely some validity to the worry, ultimately this short-term thinking is the economic policy equivalent of an insecure boyfriend who doesn’t want his partner to go out or do anything for fear that they may leave him.
Here’s the thing: if governments really want to accelerate their tech ecosystems, they should be encouraging their founders to travel to Silicon Valley in order to learn from and work with the best. Sure, a few might stay. But the vast majority won’t for a wide variety of reasons. And guess what? Those who do stay will learn a ton while they’re in the U.S. And a good number of them will one day repatriate home and bring back with them the knowledge and experience they gained. And for those who choose not to return, where do you think they’re going to open their first remote office…?
Of course, it’s understandably difficult for politicians worried about getting reelected and corporate executives trying to get their next promotion to support this kind of long-term thinking, but it can be done.
And all it takes is a plane ticket and some office space.
Not a program. Not a detailed itinerary. Not another tour of Google’s cafeteria. Just a plane ticket and some office space.
Imagine the ROI on that.

Pan-Seared Duck Breast
Duck is a great source of protein and iron, easy to prepare and absolutely delicious. The key to delicious duck breast is crispy skin, and the key to crispy skin is cooking it low and slow.
I’m a huge fan of duck. It’s a great source of protein and iron, easy to prepare and absolutely delicious (it’s also a lot cheaper than you might expect given what most restaurants charge for it).
The key to delicious duck breast is crispy skin, and the key to crispy skin is cooking it low and slow. This recipe — inspired by Chef Thomas Keller’s Ad Hoc at Home cookbook — uses balsamic vinegar, orange zest and nutmeg to add brightness to the natural flavor of the duck.
Pan-Seared Duck Breast
Adapted from Ad Hoc at Home by Thomas Keller.
Serves: 2
Preparation time: 10 minutes (followed by 1 - 12 hours of resting time)
Cooking time: 30 minutes
Ingredients
2 duck breasts
1 orange
2 bay leaves
2 sprigs of thyme
Balsamic Vinegar
Ground nutmeg
Salt and pepper
1 tbsp vegetable oil (for cooking)
Either 1/4 cup of blueberry jam or 1 cup of dry red wine plus 1 tbsp of butter (see Cooking below)
Preparation
(For best results, the duck should be prepped and refrigerated 8 - 12 hours before cooking, so try to do this in the morning before work.)
The first preparation step is to “score” the duck skin. To do this properly, you’ll want to make sure the duck is cold (so remove it from the fridge and score it right away). Use your knife to cut a cross hatch pattern with lines approximately one inch apart. Be careful to only cut the skin and not pierce the flesh underneath (though don’t be surprised if you do the first few times you try this — it’s okay).

Some butchers will score the skin for you
Next, flip the duck breast over. You should notice a tendon running the length of the breast. Use a paring knife to carefully remove the tendon.
Season the flesh side of each duck breast with salt, pepper and a pinch of nutmeg. Grate a small amount of orange zest onto the flesh using a microplane (or the finest setting on a cheese grater, if you don’t have one). Next, sprinkle a few drops of balsamic vinegar onto the flesh. Finally, place one sprig of thyme in the center of the duck breast and cover it with a bay leaf.

Flip the duck breast back over and season the skin side with a generous pinch of salt and a pinch of nutmeg.
Place the duck breasts skin side down on a baking sheet lined with parchment paper and refrigerate uncovered for at least 1 hour and up to 12 hours. This step is crucial, not only because it allows the flavors of the seasoning to penetrate the duck flesh, but because the salt acts to remove moisture from the skin, which is essential to getting nice, crispy skin.
Cooking
Preheat the oven to 300ºF.
In a large, oven-proof pan, heat the oil over medium-low heat. Remove the thyme and bay leaves from the duck breasts, placing the thyme springs in the side of pan so that the duck fat gets infused with the flavor of the thyme.
Place the duck breasts skin side down and sear the skin on low (this is the part that takes some patience). It will take about 20 - 25 minutes to get a nice, crispy skin. Periodically use a small spoon to remove excess duck fat from the pan (make sure to keep this for other uses!). Move the duck breasts around every few minutes to ensure even browning.
Once the skin is nice and brown (see below), flip the duck breasts over and “kiss” the flesh side for about 30 seconds. After that, flip the duck breasts back over so the skin side is down and place the pan in the oven (remove the thyme sprigs before placing the pan in the oven).

Cook the duck breasts for about 5 minutes for medium rare (the internal temperature should be 125ºF).
Remove the duck breasts from the oven and place them skin side down on a cooling rack (it’s really important that you use a cooling rack and not rest them directly on a plate or cutting board — doing so will ensure that any juices that drip off fall through the cooling rack as opposed to pooling and ruining your nice, crispy skin!).
While the duck breast are resting for 5 - 10 minutes, you can choose one of the following finishes:
Warm, blueberry jam
Blueberries and duck is a natural pair. Take 1/2 cup of your favorite blueberry jam and warm it in a small saucepan.
Red wine reduction
Pour any excess fat from the pan you used to cook the duck and pour the red wine into the pan. Increase the temperature to medium high while using a wooden spoon to scrape up any tasty browned bits.
Simmer the wine until it reduces to 1/3 (about 5 minutes). Reduce the temperature and add the butter, along with salt and pepper to taste.
Serving
Slice each duck breast into about 8 slices.

Plate each duck breast, topping either with warm blueberry jam or red wine reduction.
Duck breast pairs with all manner of side dishes, including potatoes, risotto, roasted root vegetables or kale salad.

Treat Yo' Self!
If your goal as a founder is to build a world-changing company you need to put yourself in the best position to run an epic, decade-long marathon. Which means you need to treat yo’ self!
If you spend any time on social media, you’ll quickly realize that there are as many different perspectives on what the founder journey is supposed to be as their are actual founders. On one end of the spectrum, there are the founders for whom a startup is a means to an end. For them, the journey is one of 4-Hour Work Weeks, automations and optimizations. The goal isn’t to build something big, so much as it is to finance a full life with the minimum work possible. At the other end of the spectrum are the devotees of hustle culture. For these founders, startups are all about sacrifices, doing Hard Things and never giving up. Their goal is nothing short of changing the world, and they believe that there are no shortcuts in such a pursuit.
As I’ve gotten older, I’ve come to believe that there’s a space in the middle. If your goal is to build a world-changing company, I am firmly of the belief that hard work is essential and there are no shortcuts. You simply can’t work remotely for 3 days a week, taking breaks whenever you feel like it to surf and expect to build a billion-dollar company. (You can absolutely finance a full life with such an approach, but this blog isn’t for those founders).
For the founders who are genuinely trying to change the world — the founders for whom the goal is to build a world-changing, multi-billion dollar company — I believe that it’s essential that you put yourself in the best position to run an epic, decade-long marathon. Because if you are ultimately successful, that’s what you will have done. But to survive that long, you need to treat yo’ self.
If you have no idea what I’m talking about, it’s a reference to an episode of Parks and Rec titled “Pawnee Rangers”. Two of the show’s main characters, Donna (Retta) and Tom (Aziz Ansari), embark on their annual “Treat Yo’ Self” shopping extravaganza, where they give themselves permission to buy and do whatever they want without feeling guilty.

The pair invites along a third character, Ben (Adam Scott), in the hope of cheering him up. As the episode progresses and Ben fails to relax, Donna and Tom realize that treating yourself might look different for Ben. They encourage him to find his own way to enjoy something without guilt, which leads to him purchasing a movie-quality Batman costume.

I’m not suggesting that you necessarily hold in everything and wait until one day a year to treat yo’ self (though that could certainly be fun). What I am suggesting is that allowing yourself the space to enjoy life during your entrepreneurial journey is not only is something you deserve, but it’s something that can make you a more successful entrepreneur.
For most people, starting a new company is an exercise in frugality. You start off bootstrapping, perhaps with a bit of money from family and friends along the way. And you have to make it last. Over time, this scarcity mindset can get deeply entrenched — particularly for first time founders — and it’s hard to undo.
As an example: shortly after we raised our Series A at Aster Data, travel picked up for many of us as we started to grow revenue and had to make frequent sales trips (this was long before selling over Zoom was a thing). Despite the fact that we had raised more than $5M, we frequently took brutally inconvenient flights with multiple layovers in order to save $10 or $20. It was only when we hired our first sales rep that he looked us in the eyes and asked, “what are you guys doing to yourselves???”

If you sit back and take a long view of the entrepreneurial journey, not only is it important that you stay focused and put in consistent, concerted effort. It’s also essential that you take care of yourself and line yourself up for long-term success. Through that lens, some things that might be considered unnecessary or “luxuries” not only can be justified, but can actually increase your chances of winning.
Here are some examples:
For the home:
A good mattress / pillows
A comfy chair for working or reading
Blackout curtains for your bedroom
A good shower head (Seriously — how many of us lived with a crappy shower head and were frustrated every time we took a shower? You can get a really nice one for $50-100 and it takes about 3 minutes to install.)
High-quality knives/pots/pans if you cook a lot
If you travel frequently:
High-quality luggage that is easy/efficient for packing
Noise-cancelling earphones for the plane
A credit card that gives you access to airport lounges
Plus grooming, massages, clothing and more

This isn’t to say that you should suddenly go out and blow all of your money, but a few nice things can make a huge difference when you’re working 80+ hours a week on your startup.
So in between your startup hustle, treat yo’ self!
Mashed Sweet Potatoes
Sweet potatoes aren’t just for Thanksgiving. This easy-to-make recipe uses brown butter to add a depth of flavor to the traditional favorite.
For as popular as sweet potato fries are, most people I know only eat mashed sweet potatoes at Thanksgiving and Christmas. But sweet potatoes are full of vitamins, easy to make, and absolutely delicious. After trying this recipe, they’ll be in regular rotation at your home (especially if you have kids!).
But first, let’s talk about the types of sweet potatoes. Everyone is familiar with orange sweet potatoes, but there are actually many different types. In North America, you’ll find 5 different varieties of sweet potatoes in most grocery stores:
Orange skin with orange flesh
Purple skin with purple flesh
Yellow skin with white flesh (aka hannah sweet potatoes)
Red skin with orange flesh (aka garnet sweet potatoes)
Purple skin with white flesh (aka Japanese sweet potatoes)

Each variety of sweet potato has a unique flavor and texture. For this recipe, I recommend using either traditional orange sweet potatoes or Japanese (purple skin / white flesh) sweet potatoes, as they are naturally the sweetest and have a high moisture content.
The secret to this recipe is the brown butter, which adds a depth of flavor and balance to the sweetness of the potatoes and maple syrup.
Mashed Sweet Potatoes
Serves: 4 - 6 people as a side dish
Preparation time: 10 minutes
Cooking time: 2 hours
Ingredients
4 lbs of sweet potatoes — about 4 large potatoes
For this recipe, I recommend using traditional orange or Japanese sweet potatoes, as they are naturally the sweetest
8 sprigs of thyme (6 sprigs whole / 2 sprigs with leaves removed and chopped)
6 tbsp unsalted butter
1/4 cup maple syrup
Pinch of salt
Preparation
Adjust oven rack to center position and preheat to 300ºF.
Take two large sheets of heavy-duty aluminum foil and place them on top of each other. Put 2 of the sweet potatoes in the center of the sheet and place 3 sprigs of thyme on top.

Fold up the foil and crimp tightly (the goal is to steam the potatoes in their natural moisture, so we want to prevent air from escaping). Then, flip over the packet and wrap in a second sheet of aluminum foil.

Repeat with the other 2 sweet potatoes, place the foil packets side-by-side on a baking sheet and put in the oven for 2 hours.

Remove the sweet potatoes from the oven after 2 hours and open one of the foil packets (be careful, the hot steam will escape!). If the sweet potatoes are fully roasted and cooked through, the skins will appear moist. If they still look dry/matte, close the packet back up and put in the oven for another 15 minutes (you can also test with a toothpick - inserting a toothpick into the potatoes should have no resistance if they’re fully cooked).

When fully-cooked, the sweet potato skin will be moist/glistening
Once the sweet potatoes are fully cooked, open up both foil packets and set aside to cool.
While the sweet potatoes are cooling, melt the butter in a small saucepan over medium-low heat. Gently swirl the butter around until the liquid starts to turn golden brown and smells “nutty” (this should take about 2-3 minutes).
Immediately pour the melted butter into the bowl of a stand mixer fitted with a flat beater attachment (or a large glass or metal bowl if you don’t have a stand mixer). Combine with the maple syrup and the chopped leaves from 2 sprigs of thyme.
Next, peel the skins off of the sweet potatoes. If they’re cooked all the way through, the skins should just “slide” off (be careful not to burn your fingers if they’re still hot). After peeling, check the ends of each potato and remove any discolored nubs. Add the sweet potato flesh to the bowl containing the brown butter, maple syrup and chopped thyme leaves.

Beat the sweet potatoes in your stand mixer on medium low (a setting of 3 or 4 out of 10) for about 2 minutes until smooth and fluffy. If you don’t have a stand mixer, use a handheld mixer. If you don’t have a handheld mixer, it’s time to roll up your sleeves and get to work.
Season to taste with a pinch or two of salt (just enough to cut the sweetness).
Serving
Serve immediately or make ahead (mashed sweet potatoes will last 4 - 5 days in the refrigerator or up to a year in the freezer).

Why Do Solo Founders Make VCs Nervous?
One topic that gets founders riled up is the fact that many VCs won’t invest in solo founders. Why do solo founders make investors so nervous?
One topic that gets startup founders riled up is the fact that many VCs won’t invest in solo founders. It’s frustrating to be asked over-and-over again about your cofounders when you’re a solo founder. After awhile, it can easily begin to feel like a lazy cop out. So why do solo founders make VCs nervous?
Before I get into that, a quick aside…
Many of you have likely seen some version of the chart below from a 2018 study called Sole Survivors: Solo Ventures Versus Founding Teams:

This study is often pointed to as a repudiation of investors who are unwilling to back solo founders with some variation of the claim, “Solo founders are 2.6x more likely to succeed than founding teams!” But alas, that’s not what the study said.
In fact, this study wasn’t even about venture-backed startups. It was about kickstarter projects that were crowdfunded between 2009 and 2015. And that 2.6x number? It has nothing to do with success — it’s simply a measure of which companies were still alive when the study was done.
Speaking of companies, many of those “solo founder companies” referenced in the study were actually just single-person companies. Which isn’t to say that they aren’t to be commended, but defining success as a “single-person LLC that isn’t dead” isn’t what we typically think about when we’re talking about high-growth ventures.
So let’s focus on high-growth startups and dig into some of the concerns that potential investors have when it comes to solo founders.
Just as it’s important during fundraising to get a VC to see past your resume, understanding the reasons why solo founders make VCs nervous can help you to present your company (and yourself) in a way that asuages those fears.
Here are 5 reasons why solo founders make VCs nervous:
1. Are you difficult to work with?
This is the low-hanging fruit of risks: are you a solo founder by choice, or because nobody wants to work with you?

“Hi Peter. What’s Happening? We need to talk about you being my cofounder.”
Like it or not, it’s a legitimate concern. You can mitigate this by assembling a strong team, but if it’s just you…why is it just you?
2. Do you have a sounding board?
Another major risk that solo founders face is that they often don’t have a sounding board in the same way that CEOs with cofounders do.
When you’re a solo founder, everyone else in the company works for you. That means they’re unlikely to give you the type of direct feedback that you would get from cofounders. On top of that, when feedback is given, many solo founders dismiss it for all manner of reasons.

Over the years, I’ve invested in many solo founders and almost every one struggled with this point. In some cases, I would argue that the lack of a trusted sounding board ultimately led to the failure of the company.
If you’ve got a proven track record, this isn’t as much of an issue. But if you’re a first-time founder, showing investors that you’ve assembled a trusted pit crew (not just an advisor slide with fancy names and logos), can go a long way in building confidence in your ability to survive the startup rollercoaster and not get caught up in your own tunnel vision.
3. Can you go fast enough?
When I pass on a strong solo founder, this is easily the #1 reason why.
It’s not that I don’t think you’re smart. It’s not that I don’t think your idea is a good one. It’s that I’m not convinced that you can go fast enough to win in a competitive market where other startups have 2, 3 or 4 equivalently awesome cofounders on day one.
I’ve written before about the fact that when I meet a promising Canadian startup, the #1 question in my head is always, “Can you beat my friends?” A nuance to that is that every single one of my friends who created a unicorn had cofounders. On day one of their company, they were a highly motivated, highly incentivized and highly aligned team.

Who are you handing off to?
Obviously, there’s a bit of selection bias here, but the velocity and trajectory of a startup with multiple cofounders is fundamentally different from one founded by a single, highly-experienced cofounder, unless you’re starting off with an extremely strong supporting cast.
I recently passed on a company with a very strong, experienced solo founder whose concept and early validation with impressive. Unfortunately, when we started talking through his roadmap for the next couple of years, it was a clear that the company’s velocity was already bottlenecked by the founder having to fill multiple strategic roles. And there was no clear path to unblocking him. As a result, I simply could not envision a version of the future where this founder wouldn’t lose out to the other companies I knew to be already in market with teams of 3 or 4 equivalently strong cofounders.
4. Do you have the right network / can you hire?
Another team-related risk of solo founders focuses on whether or not you can hire the right people.
A significant percentage of the companies I’ve met at Pre-Seed with solo founders have teams that consist of a strong solo founder, perhaps one senior-ish engineer, and a couple of junior devs. It makes sense, considering that the engineers are all likely looking for decent salaries and the company hasn’t yet raised meaningful capital.
The problem is, if you’re going to win in a competitive market, you need to have a competitive team. And that can’t just be cheap, junior devs. Who’s going to be your CTO? Your VPE? Your head of sales? Etc.

Can you recruit a top-tier leadership team?
You don’t have to have all of the answers, but if you can demonstrate a strong professional network and/or identify one or two key hires you intend to make after completing the round, it will go a long way to convincing potential investors that you’ve got the right connections.
5. What if you get hit by a bus?
This may sound facetious, but it reflects a legitimate risk: a company with a solo founder has a single point of failure from day one.
Absent a strong executive team, the company’s progress (or lack thereof) is directly pinned to your personal well-being. What happens when you get sick? What happens when you take a vacation (or, worse, what happens if you don’t)?
Back when I was at Aster Data, our CEO Mayank went back to India one year for holidays…and U.S. immigration didn’t let him back in. I won’t go into the details of how ridiculous this situation was (there’s a reason why immigration is America’s Achilles’ heel) but it goes without saying that it was less than ideal for a fast-growing startup.
It was more than 3 months before Mayank was allowed back into the US. And while it was certainly disruptive (this was back before Zoom or Slack or remote work), our team didn’t miss a beat. (I got really good at saying, “Hi, my name is Chris Neumann. Unfortunately, Mayank’s flight got delayed…”)
While this was obviously an unusual situation, it’s not at all uncommon for founders to unexpectedly need to take time off. That’s life. Demonstrating that you’re setting up redundancies within your company early on — including to mitigate founder burnout — is something to keep in the back of your mind when speaking with potential investors.
Miso-Marinated Black Cod
Made famous by Nobu, this traditional approach to cooking black cod (sablefish) from Kyoto involves marinating the fish in a white miso-based marinade for 2-3 days.
Peruvian-Japanese restaurant chain Nobu is one of the most recognizable brands in the culinary world. At the core of this restaurant powerhouse is Chef Nobuyuki Matsuhisa’s elevated take on Peruvian-Japanese cuisine. (The fact that his restaurants are name-dropped in countless songs certainly hasn’t hurt.)

Eatin' crab out in Malibu at Nobu
Introduced back in 1994, the restaurant’s most famous dish involves a surprisingly simple preparation that makes it ideal for busy founders. The approach, known as saikyo yaki, is a method of preparing fish that involves marinating the fish in a white miso-based marinade called saikyo shiro miso. It originated in Kyoto before refrigeration was available as a means to preserve fish.
This particular recipe uses black cod (also known as sablefish), a mild white fish native to the North Pacific Ocean (British Columbia, Washington and Alaska). Black cod is high in omega-3 fatty acids, EPA, and DHA, making it extremely healthy. It’s high fat content also makes it very forgiving when cooking — in other words, it’s really hard to screw this recipe up. Black cod is a year-round fishery, so you can get this fish fresh and wild anytime of the year. It’s also relatively inexpensive (in Vancouver, you can even get fresh black cod at Costco!).

But there is one unusual aspect of this recipe to be aware of: the fish must be allowed to marinate for 2 to 3 days.
The high fat content of black cod makes it take longer for the fish to absorb flavors. If you don’t let this recipe marinate for at least 48 hours, you simply won’t get the deep flavor of the miso for which this dish is famous. For optimal freshness, you should marinate the fish the same day you buy it. So if you buy and marinate your fish on a Monday, you should plan to cook and eat it for dinner on Wednesday or Thursday. And so on.
This recipe specifically uses white miso, which is milder and sweeter than other forms of miso. Most grocery stores will carry at least one brand of white miso, but be aware that taste and quality vary widely by brand. My favorite North American miso producer by far is a small craft producer in San Francisco called Aeden Fermented Foods. In fact, this miso is so good that I regularly bring back 2 or 3 containers when I’m visiting San Francisco.

Miso-Marinated Black Cod
Adapted from Nobu: The Cookbook by Nobuyuki Matsuhisa.
The recipe below is for one full fillet (side) of black cod. To make more, simply increase the recipe accordingly.
Serves: 2 - 3
Preparation time: 5 minutes
Cooking time: 15 minutes (2 - 3 days later)
Ingredients
1 full fillet (side) of black cod or 4 x 8oz portions
¼ cup sake
¼ cup mirin
¼ cup white miso paste
3 tbsp granulated sugar
2 tbsp vegetable oil (for cooking)
Preparation (2 - 3 days before cooking)
In a small saucepan, bring the mirin and sake to a boil over high heat. Let it boil for 20 - 30 seconds to give time for the alcohol to evaporate.
Reduce the heat to low, then add the miso paste and whisk until it has completely dissolved (note: there may still be “chunks” of soybean in the mixture if the miso itself is not smooth).
Turn the heat back up to high, add the granulated sugar and whisk until the sugar has completely dissolved. Make sure to whisk constantly during this part, so that the sugar does not burn at the bottom of the saucepan.
Remove the saucepan from the stove and pour the marinade into a bowl, then let it cool to room temperature.

While the marinade is cooling, remove the black cod from the packaging and pat dry with a paper towel to remove excess moisture.
To marinate, you can either place the fish into a Tupperware container or use Ziplock bags. For full fillets, I find that using quart-sized Ziplock bags with the fillet folded in half yields the best results (as there is very little room for air). Pour the marinade into the container, ensuring that the fish is completely slathered, and then place in the fridge for 2-3 days. If using a Ziplock bag, turn the bag over once per day to make sure the fish gets full coverage from the marinade.

Cooking
Preheat the oven to 400ºF.
Remove the container of marinating fish from the fridge and get a large plate. One at a time, remove each fillet or fish portion from the container and use your fingers to remove excess marinade from the fish (you don’t want to rinse the fish…you just want to remove excess marinade so that it doesn’t burn when cooking). After removing the excess marinade, place each fillet or fish portion on the plate.

After 2-3 days, the black cod will take on a dark golden color from the miso marinade
In a large, oven-proof pan, heat the vegetable oil over medium-high until shimmering. Place the fish flesh-side down (skin-side up) in the pan and cook until the marinade starts to caramelize and the flesh begins to brown (or even blacken in a few spots). This should take 2-3 minutes.

If you don’t have really large pans, portion the fillets before marinating
Carefully flip the fish over so that the skin side is down. Cook for 1 more minute to allow the skin to slightly crispen and place the pan into the oven.
Cook for 5 - 10 minutes until the fish is opaque begins to slightly flake.
Serving
I generally serve this with rice and one or two steamed or stir-fried vegetables (bok choy, broccoli, edamame and gai lan are all favorites in the Neumann household).

(The fish on the left is slightly over-cooked — there should not be that much flaking 😉)
A Hard Tech Renaissance is Happening and Canada Risks Missing Out
Canada has a long, proud history in hard tech but risks missing out on the current renaissance for one key reason.
Over the past two years, as the tech world emerged from the rubble of the ZIRP crash, an undercurrent of hard tech that has been quietly developing began to rapidly accelerate. And not just around AI. Today, we’re seeing renewed interest in hard tech on a number of fronts:
Global conflicts shining a spotlight on defense tech
A reversal of globalization driving interest in supply chain and energy technologies
A new golden era of space accelerating research into communications, manufacturing and transportation technologies
A growing focus on climate change accelerating research into climate and sustainability technologies
Last week, Y Combinator put a spotlight on this movement in its most recent request for startups, which Techcrunch noted had a significant emphasis on hard tech. At the same time, it seems like every VC who rushed to set up shop in Miami is now tripping over themselves trying to find office space in SoCal.

I left my wallet in El Segundo
Canada has a long, proud history in hard tech and there is no shortage of Canadian entrepreneurs working in these areas today. In fact, many individuals and organizations across the country recognized this shift early on and have worked over the past several years to build support for this country’s most ambitious hard tech founders. Prominent accelerator Creative Destruction Lab, for example, has programs dedicated to space tech, energy, mining, AI, climate, manufacturing, ocean tech and quantum computing (amongst others).
Yet despite all of this support, Canada still risks missing out on the hard tech renaissance for one key reason: a lack of early-stage capital for hard tech startups.
What is Hard Tech?
Let’s start by defining what “hard tech” is.
Hard tech (also known as deep tech) typically describes a category of startups whose product development involves solving significant scientific or engineering challenges.
We’re not talking about B2B SaaS here. We’re talking about technologies for which success is not a foregone conclusion. Technologies for which the underlying R&D is genuinely hard and, at the end of the day, might not actually work.
It’s worth noting that, contrary to popular belief, hard tech does not necessarily involve hardware. While many hardware-based startups fall into this category, a significant number of software-only companies do as well. In fact, it wasn’t long ago that almost all tech was considered “hard”.
When we were building Aster Data twenty years ago, the engineering challenges we had to solve were really really hard. No one had ever created distributed database software designed to run on commodity hardware before. What started with Mayank’s PhD thesis at Stanford (which itself was 5 years of hard work on his part), was followed by 6 months developing a prototype that could only execute 8 hard-coded SQL queries.
But that was enough to convince David Cheriton, Anand Rajaraman, Josh Kopelmen (of First Round Capital) and Ron Conway (of SV Angel) to invest.
After that, it was another year before we had a semi-functional beta version of the product (one that was held together by virtual duct tape and still couldn’t do database joins) and a year more before we had a dollar of revenue. Seriously…this stuff was hard!
But guess what? Early investors weren’t scared to invest in the company. In those days, the first round of funding was rarely enough to get to first revenue. It was par for the course.
Which leads me to suggest an alternate definition of “hard tech”:
Hard tech startups are companies for whom 2 or more rounds of funding are required to generate initial revenue.
Rather than defining hard tech in terms of the underlying technology or the subjective difficulty of the engineering challenges that need to be solved, we can think about these companies in terms of the amount of capitalization required to get to first revenue.
The corollary of this definition?
Hard tech startups not only require angel investors and Pre-Seed VCs who are willing to invest pre-revenue, but also Seed VCs and potentially even later VCs.
The Vanishing Hard Tech Investor
It used to be that most tech startups fit my definition of “hard tech” and most early-stage investors were fine with that. But over the past dozen or so years, things changed.
Today, there’s an entire generation of investors who grew up in the era of The Lean Startup and AWS and all of the other developments that made it seem like every startup should be able to hit a million users or $100K MRR or whatever other arbitrary metric investors deem appropriate within 18 - 24 months.
An entire generation of investors who believe that any company that doesn’t have traction within its first 18 - 24 months is not “VC-backable”.
Let’s be clear: this idea is utter nonsense.
The average life of a VC fund is more than 13 years, with many lasting 16 or more. So it’s simply not credible to claim that a startup which needs 3 or 4 years to get to initial revenue is not VC-backable or won’t exit within the time horizon required by a VC.
In reality, the claims that hard tech startups are not VC-backable is a red herring. What actually happened is that we’ve ended up with a generation of investors who have only ever had to worry about distribution risk. A generation of investors for whom technological success seemed a foregone conclusion: throw enough engineers at the problem and success is all but assured.
Think about that for a minute. There’s an entire generation of “tech investors” who have no idea how to underwrite technnology risk.

As a result, these investors avoid investing in anything that looks or smells like hard tech and retreat to the safety of B2B SaaS, with it’s prolific, easy-to-analyze and widely-available metrics. The “you can’t get fired for buying IBM” of tech investing.
What’s worse? Many of the OG VCs who made their names investing in hard tech are now riding off into the sunset. One of many examples is Foundry, who recently announced that their current fund will be their last.
When we were raising the initial round of funding for DataHero, we were very transparent with potential investors that we likely wouldn’t achieve initial revenue with our first round. We were building the world’s first cloud-native BI platform and that was going to be “hard”. When we walked through our likely development timeline with Foundry’s four partners (Ryan, Brad, Seth and Jason), they didn’t bat an eye at the possibility that we would need a second round of funding before generating any revenue. To the contrary, they led us through a detailed discussion of non-financial milestones that we could achieve to help them to gain confidence about making multiple pre-revenue investments.
Today, it’s hard to find investors like that. Instead, this is more common:

Who’s Going to Write the Next Check?
If VCs around the world are struggling to invest in hard tech, why is Canada in such a risky position? Let’s start with another anecdote:
Several years ago — when I was still living in San Francisco — I was a mentor for one of Canada’s hard tech accelerators. The program’s mentors included numerous Canadian angel investors and VCs, all of whom (presumably) had some interest in hard tech.
One of the companies in the program was a startup that was using hyperspectral imaging to improve the efficiency of mining (back before using hyperspectral imaging was considered cool). The founder had deep experience in the space: he spent years as a mining exec before going back to school specifically to earn a PhD to solve this problem. He was completing his PhD, launching the company, participating in the accelerator and lining up his initial pilots all at the same time.
Suffice to say, as a Bay Area investor, this was an absolute no brainer — despite the fact that the path to actual revenue was likely to be a lengthy one. I commited to make an angel investment in the company halfway through the program. But to my surprise and disappointment, not a single other mentor — angel investor or VC — invested in the company (despite the fact that the founder consistently received feedback that he was one of the best to have ever participated in the program).
The most common refrain I heard as to why other mentors weren’t interested in investing in the company had nothing to do with the founder, technology, or market but, rather, was some form of “I don’t know who is going to write the next check.”
I later came to realize that what this really meant was, “I don’t know who in Canada is going to write the next check.”
Shorly after the program completed, the next checks came:

While it might be easy to dismiss this anecdote based on geography (undoubtedly, some of the investors in the program were legitimately unable to invest in an Australia-based company), I’ve seen versions of this dynamic play out over-and-over again since returning to Canada. And it ties directly to the corollary I shared above:
Hard tech startups not only require angel investors and Pre-Seed VCs who are willing to invest pre-revenue, but also Seed VCs and potentially even later VCs.
In Canada, there are almost no Seed or Series A VCs that are willing to invest in companies pre-revenue. As a result, angel investors and Pre-Seed VCs whose investor networks are predominently in Canada are unlikely to invest in hard tech companies, as they have no line-of-sight to follow-on capital.
I’ve previously written about the fact that Canadian VCs need to get out of Canada. And this is one of the big reasons why.
If early-stage Canadian investors continue to make investment decisions that are influenced primarily by the the availability of downstream capital from other Canadian VCs, any advantage that Canada has in hard tech will soon be lost.
But if more early-stage investors spend time abroad (especially in Silicon Valley), they’ll be able to form a more complete picture of the demand for companies by downstream investors. And they’ll have more confidence investing in hard tech companies that they know will require multiple rounds of funding in order to generate initial revenue.
I’m going back to SF next week. Who’s in?

5 Ways to Improve an M&A Outcome
Like fundraising, getting acquired is something most founders only do once (if ever). Here are 5 ways you can improve the outcome of an M&A process.
Lately, I’ve been having a lot of conversations with founders about mergers and aquisitions (M&A). Some founders are in hot sectors and fielding unsolicited offers from cash-rich incumbents. Others are nearing the end of their runway and looking for a “soft landing”.
Just like fundraising, getting acquired is something that most founders only do once (if ever). It’s hard to learn about the topic, as there are far fewer blog posts on how to navigate an acquisition process than there are on how to fundraise.

There is, however, Mergers & Acquisitions for Dummies 🤣
Having been through three acquisitions myself (and observed many more from the sidelines), I thought I’d share some tips.
Here are 5 ways to improve the outcome of an M&A process:
1. Have Plenty of Runway
This may seem obvious, but similar to fundraising, it’s essential that you have plenty of runway before you begin an M&A process. In some respects, it’s even more important. That’s because one of the basic stategies that corporate development professionals use when trying to acquire a company is to run out the clock. The less runway you have, the more desparate you become (and the cheaper you’re likely to be).
In fact, many corp dev teams are compensated based on how cheaply they’re able to acquire a target company.
Some acquirers are infamous for doing everything in their power to drive down the price of an acquisition, including driving startups to the edge of insolvency.
Actual footage of a VP of Corporate Development
As with any negotiation, one of the most powerful things you can do is to be in a position to walk away. So make sure you have at least 6 months of runway (or more) when you start a process. And if runway is an issue, make sure you’re fundraising in parallel to exploring potential acquisitions.
2. Get Advice from People Who Have Actually Been Through an Acquisition Process
As with many topics, most founders turn to their investors when seeking advice about navigating a potential acquisition. But guess what? The vast majority of investors have never actually been through an acquisition process.
Now, it’s true that many investors are expert negotiators (which makes sense, as it’s a core part of what we do). But M&A negotiations can be very different from fundraising negotiations. The best corp dev teams employ strategies that most VCs have never seen firsthand. So while investors are more than eager to suggest strategies for “maximizing outcome”, in my experience much of this advice is…well…basic.
Unless your investor has personally been through an acquisition or comes from a corporate development background (like Villi Iltchev at Two Sigma or Code Cubitt at Mistral), you should assume that your VCs will be giving you advice on how to play checkers while your corp dev opponents are playing chess.

When I went through my first acquisition process as a CEO and was trying to wrap my head around the (seemingly confusing and contradictory) actions being taken by the corp dev teams, my first calls were to my investors. They gave me plenty of sound and logical advice, but the most important thing they did was to make two key introductions:
To a portfolio founder who had been through 4 successful acquisitions
To a portfolio founder who had previously been in a corp dev role at a major tech company
All of a sudden, the advice I was getting went from simple parlor tricks to black magic.
So when your investors are done giving you the 101 on how an acquisition works, ask them to introduce you to the founders they know who've been through multiple acquisitions and any corp dev (or ex-corp dev) people in their network.
3. Figure Out the Real Motivation of the Acquirer
One of my favorite quotes on this topic is from Alexandra Greenhill, CEO and Founder of Careteam:
“The price you’re worth depends on what the buyer needs you for.”
When a potential acquirer shows interested in our company, founders naturally jump to conclusions about their motivations.
“They’re excited about our technology!”
“They’re trying to get into our market!”
“They’ve had the same epiphany that I had about the future…!”
And so on. But frequently, a potential acquirer’s true motivations have little to do with our ego-driven assumptions.
Early in DataHero’s journey, we were approached by the corp dev team at Pinterest about a potential acquisition. We had received a lot of press when we came out of stealth and were fielding a considerable number of inbound calls from companies hoping to white label our product. The Pinterest team needed to develop analytics and reporting capabilities in advance of releasing their advertising offering, so naturally we presumed that they wanted to incorporate DataHero as the foundation for those capabilities.
It turned out that Pinterest only wanted to bootstrap an in-house analytics team and had zero interest in any of our IP. (And they subsequently floated an acquisition offer that was priced accordingly.)
There are a wide variety of motivations that drive acquisition interest. Many will value your company lower than what you might hope for. Some will value it much higher. Uncovering the true motivation can help drive your strategy and is key to improving your outcome. Common motivations include:
Humans (individual contributors, key executives or entire teams)
Tech / IP
Revenue (this can be a direct revenue stream, access to a new market or customer segment, or a product the acquirer believes they can sell easily into their existing customers)
Cash (believe it or not, many for-stock acquisitions happen because the company being acquired has a lot of cash in the bank)
Press / Stock Price
4. Figure Out if there is a Forcing Function
Similar to the importance of unconvering the motivations driving a potential acquirer’s interst, it’s important to discover whether or not there’s a forcing function influencing the timing.
When Vancouver’s Picatic was in acquisition talks with Eventbrite, the founder sensed a level of urgency that he couldn’t figure out. He was trying to slow play the opportunity (in order to drum up competitive offers), but the Eventbrite team was pushing for a quick resolution.
Eventually, he uncovered that the urgency was tied to Eventbrite’s plans to go public — they needed to complete the acquisition in a matter of weeks. This one piece of information gave him considerable leverage with which to negotiate the acquisition of his company.
Understanding whether or not there’s an internal forcing function driving a potential acquirer’s timeline is another key way you can improve your outcome.
5. Always Take the Meeting
If someone in a corp dev role ever reaches out to you about a meeting — even if you’re not thinking about an acquisition — always, always, always say yes.
Take the meeting, but come prepared to say nothing.
This is the opposite advice I typically give when it comes to fielding inbound calls from potential investors. So why should you take corp dev meetings? Because you never know where they may lead.
Shortly after Aster Data came out of stealth in 2008, we were approached by Teradata’s head of corporate development about a meeting. We were an entirely inexperienced team and Teradata was our bogeyman — the company we saw as our #1 competitor. We were paranoid that they would try to suck each and every secret they could out of us, and were inclined to say no. But our investors insisted that we take the meeting.
“Take the meeting, and just listen.”
That meeting was the first time that Teradata attempted to acquire Aster Data.
Over the next several years, as the “Big Data” industry emerged and Teradata struggled to develop a competitive solution, we fielded multiple acquisition offers from them. Each approach was met with skepticism from our side. We were convinced that, should we ever enter a process, Teradata would extract all of the information they wanted during diligence, cancel the acquisition, and turn around and crush us with a well-funded competitive offering. (It was years later that we discovered just how inept their internal attempts to build a big data offering had been, and this was never a realistic scenario.)
In 2010, rumors were flying that Teradata’s main competitor, Netezza, was about to be acquired by IBM. That’s when they approached us with a much more serious offer. But we still didn’t trust their motivations. Sequoia’s Doug Leone — one of Aster Data’s board members — proposed a “test” to see how serious they really were: ask them to invest in our series C, with no information rights, no right-of-first-refusal and no access to proprietary information. If they were willing to do that, then we would know that they meant business.

Days after we completed our Series C, IBM’s acquisition of Netezza was publicly announced. Our own acquisition talks then began in earnest, and on Christmas Eve, 2010, we signed the LOI to be acquired by Teradata (thus kicking off the most painful, drawn-out diligence process I’ve ever experienced).

Beyond the opportunity for serendipty, the biggest reason to always take corp dev meetings is to open channels of communication. Should you ever need to spin up an acquisition process (or ramp up competitive offers), you’ll already have relationships with the people you need to speak with.
Coq Au Vin
Even if you know nothing about French cuisine, you almost certainly have had coq au vin. Originally popularized in North American in the 60s by Julia Child, this receipt is easy-to-make and full of flavor.
Even if you know nothing about French cuisine, you almost certainly have had coq au vin at some point in your life. Literally translated as “rooster/cock with wine”, this traditional French dish was first popularized in North America in the 60s in Simone Beck, Louisette Bertholle and Julia Child’s groundbreaking two-volume cookbook, Mastering the Art of French Cooking.
Making coq au vin is relatively straight-forward, though it is fairly involved. Unlike many of the recipes I share, this one requires about 90 minutes of active work — so it’s better suited for a weekend (when you can listen to an audiobook and relax), then trying to prepare it on a work day in-between calls. Start-to-finish, making coq au vin takes about 3 hours, so start around 3:00 or 4:00pm in order to have it ready for dinner.
Coq au Vin
Serves: 6 people
Preparation and active cooking: 90 minutes
Passive cooking: 90 minutes
Ingredients
2 small whole chickens, quartered (about 3 pounds each, see Notes below)
2 cups dry red wine (merlot, chianti or similar)
1/4 pound bacon, cut into ¼” lardons (strips)
8 oz pearl onions (see Notes)
8 oz small cremini mushrooms
3 medium carrots, diced
4 cloves garlic
2 sprigs thyme
2 bay leaves
2 cups low-sodium chicken stock
3 tbsp unsalted butter
¼ cup flat-leaf parsley,
Kosher salt and pepper
Tools and Supplies
Large (6.7L) Dutch oven
Wooden spoon
Kitchen tongs
Slotted spoon
1-gallon Ziploc bag
Rimmed baking sheet with wire rack
Paper towels
Preparation
We’re literally making “chicken in wine”, so the first step obviously has to be “put chicken in wine”.
Put your quartered chicken (see Notes below) into a 1-gallon Ziploc bag and add the wine. Press as much air as you can out of the bag and seal. Set aside while you prepare the rest of the ingredients, turning every 5 minutes or so to make sure every inch of chicken gets soaked in delicious wine.

Preheat the oven to 350ºF.
Dice the carrots and prepare the pearl onions (see Notes below). Assuming you have small cremini mushrooms, cut them into quarters. If your mushrooms are larger, cut them into sixths or eights (the goal is to make sure the mushroom pieces are bite-sized). Peel the garlic and smash it with the side of your knife, but do not cut.

Heat Dutch oven over medium and add bacon lardons. Cook for about 10 minutes, stirring frequently, until bacon has rendered and turned brown (adjust heat if necessary to avoid scorching). Brown streaks should appear on the bottom of your Dutch oven as you’re cooking, but you don’t want them to turn black (this is scorching / burning, which will affect the flavor of the dish).

Remove the Dutch oven from heat. Use a slotted spoon to remove the cooked bacon lardons and place on a paper towel-lined bowl or plate.

Remove the chicken from the Ziploc bag and pat dry on a plate (make sure to seal the Ziploc bag back up — we’re going to use the wine later and you don’t want it to spill!). Season chicken with salt and pepper.
Return the Dutch oven and it’s rendered bacon fat to the stove and increase heat to medium-high. Add half of the seasoned chicken, skin side down, and cook until browned (6-7 minutes). After the skin side of the first batch of chicken has browned, use your tongs to flip the chicken over and cook for another 5 minutes.

Remove the first batch of chicken from the Dutch oven and place (skin side up) on the wire-rimmed baking sheet.
Repeat this process with the second half of the chicken pieces.

Once all of the chicken has been browned on both sides and is resting on the wire-rimmed baking sheet, add the mushrooms to the Dutch oven and cook, stirring frequently until nicely browned — about 10 to 12 minutes.
Add the pearl onions, carrots and garlic and cook for 5 more minutes, stirring frequently.

Next, pour the wine from the Ziploc bag into the Dutch oven and use your wooden spoon to scrape up any brown bits.
Add the bacon, thyme, bay leaves and chicken stock and bring to a boil.

Stir the mixture a couple of times with your wooden spoon and remove from heat. Place the chicken legs (not the chicken breasts) into the Dutch oven, skin side up. The chicken legs should be partially submerged with the top of the skin visible above the liquid (the chicken skin will brown while braising). Place in the oven and cook uncovered for 1 hour.

After 1 hour, remove Dutch oven from the oven and add the chicken breasts, skin side up. Use your tongs to nestle the chicken breasts in between the chicken legs (which should be nicely browned at this point). Return to oven and cook until chicken breasts reach 145ºF, about 20 minutes.

Always use an instant-read thermometer to confirm the temperature of the chicken breasts. The size and shape of chicken can vary widely (as will your abilities as a budding butcher). As such, the time needed for the chicken breasts to fully cook can range from 18 to 30 minutes. You do not — under any circumstances — want to serve undercooked chicken.
Once the chicken breasts have reached temperature, remove from the Dutch oven and place chicken breasts and legs on a (clean) wire-rimmed baking sheet to rest.
Return the Dutch oven to your stove and set to medium-low. Simmer the liquid and vegetables for 10 minutes, until the sauce starts to thicken.

Remove the bay leaves and thyme from the sauce, then stir in the butter and season with salt and pepper. Add half of the flat-leaf parsley and stir to combine.
Return the chicken to the Dutch oven, sprinkle the remaining parsley overtop and serve.

Serving
Coq au vin can be served over pasta, rice or mashed potatoes. Plate each portion of chicken on top of your carb and spoon vegetables and sauce overtop (if your chicken breasts are particularly large, slice into pieces prior to serving).

Notes
On chicken:
Learning how to break down a chicken can save you a ton of money. It’s surprisingly simple to do and all you need is a good knife and a pair of kitchen sheers. Serious Eats has a great guide on how to butcher a chicken.
For this recipe, you break each chicken down into quarters, which leaves you with this:

If you don’t want to butcher your own chicken, then you’ll need 4 chicken breasts and 4 full legs (thigh + drumstick) for this recipe.
On pearl onions:
Pearl onions are delicious, but preparing them is a pain in the you-know-what. First, you have to cut and score them, then boil them, then peal the skins off of dozens of tiny onions (can you tell I’m not a fan?). Thankfully, many grocery stores sell frozen pearl onions that have been peeled for you.
So save yourself 20 minutes of prep work and do that.
