Chris Neumann
Investor | Founder | Advocate
How to Stick the Landing
One of the hardest parts in aerial sports — whether gymnastics, skiing or snowboarding — is sticking the landing. Yet it’s arguably the most important part of the routine. You can have 60 seconds of perfection, but if you don’t stick the landing none of it matters.

In fundraising, the “landing” is the final slide in your deck – the “ask” slide.
It acts as the climax of your pitch, highlighting how much you’re raising, why you’re raising and what you’re going to do with the money.
The “ask” slide is simple in concept, yet 90% of founders get it wrong.
Here are 5 “do’s” and “don’ts” of the “ask” slide to help you stick the landing:
1. DO Ask for Money
This seems obvious, but a surprising number of pitch decks don’t include it.
I’m always caught off guard when a founder sends me a pitch deck that doesn’t include an explicit ask for funding. In most cases, it leaves me with a negative impression: has this founder actually thought about what they need?
If you’re trying to raise money, you absolutely must include an "ask” — and be specific in the amount of money you’re trying to raise. You might have a range in your head, but you need to present investors with a single number and a plan that backs it up. This is a financial transaction, after all.

2. DON’T Present a Detailed Spending Breakdown
More than half of the “ask” slides I see use the majority of the slide real estate to present a spending plan.

This is important, but it belongs in an appendix and isn’t core to “the ask”
Guess what? I already know what you’re going to spend the money on. If you’re a SaaS business, it’s developers, marketing and sales. If you’re hardware, we can throw in some inventory. Deep tech? Probably some researchers and other R&D costs.
Yes, I’m going to eventually want to see a budget. But that’s primarily to facilitate a discussion on how you’re going to get there. It’s something that belongs squarely in an appendix slide.
When reading an “ask” slide I don’t care how you’re going to spend the money. I want to understand what you’re going to achieve with it…
3. DO Tell Me What You’re Going to Achieve
The minute that money lands in your bank account, the clock starts ticking.
For VC-backed companies, you’ll almost certainly need to raise more capital in your quest to win the world. The most important question I’m asking when I read the “ask” slide is: what are they trying to achieve with this chunk of money?
The corollary is even more important to investors: if they achieve their short-term goals, will they be able to raise the next round? Will they have de-risked the business enough that the investor who comes after me will get excited?
An effective “ask” slide is concrete:
Increase sales —> Achieve $2M in ARR
Add new users —> Add 250K new users in H2 2022 and 1M more by the end of 2023
Sign new enterprise customers —> Sign 10 new F500 companies worth at least $1M in revenue
This allows us to have a discussion on whether the goals you’re setting are the “right” ones and provides context for us to dive into your plan to achieve them.

4. DON’T Include Sales Projections
Too many “ask” slides include sales projection graphs and other business details from elsewhere in the deck. This usually happens when founders treat the “ask” slide as a conclusion and try to cram a full recap of the pitch deck into it.
It’s great if you want to have a recap slide, but it shouldn’t be combined with the “ask.”
Just like the stillness of a gymnast after sticking the perfect landing, allow the “ask” to stand on its own.
5. DO Tell Me How Much Runway this Gives You
A small but crucial detail that’s missing in a lot of “ask” slides: how long will this funding give you to achieve your goals?
As a VC, I’m working backwards and assuming you’ll need 12-18 months to reach your objectives, 6 months to do your subsequent fundraise and a quarter or two of buffer. That means you should be looking at 24 months or more of runway. (In years flush with cash, founders would often plan for 18 - 24 months of runway — but even then, the response from investors would often be: “perhaps you should raise a little more?”)
This is another one of those small bits of information that can lead to incredibly insightful conversations between founders and investors, so don’t be afraid to include it. I’m guaranteed to ask you!

Want to see a really bad example of an “ask” slide? Check out the one I made for DataHero once upon a time…
Canada Needs to Stop Competing With Itself
Canadians endlessly chase our tails worried about how we’re doing relative to each other. It drags us all down. I'm over it. And you should be too.
Last week, investors and founders from across Canada descended on Montreal for Startupfest, the city’s annual celebration of Canadian startups. As always, there were startups and supporters from across the country (Calgary pancake breakfast, anyone? 😋).

The full Panache partnership from across Canada together in Montreal for Startupfest
On my way back to Vancouver — while still basking in the glow of my week in Montreal — I spent part of my flight responding to a journalist’s inquiries for a soon-to-be-released report on the health of the BC tech ecosystem relative to the rest of Canada. Which made me think: why do Canadians spend so much time comparing themselves to each other?
In all my time living in the US, I never heard anyone from the Bay Area worrying about whether a company was based in San Francisco, Oakland, San Jose or Palo Alto. Same thing in New York. I promise you that no one there cares how many startups are in Brooklyn, Mid-Town or the Lower East Side. They’re all just repping NYC. And while certain VCs in Miami are desperate for attention, the rest of America’s tech ecosystems broadly speak as one.
But in Canada? We’re obsessed with local attribution and comparison. Is a company from Vancouver or Victoria? Toronto or Waterloo? Western Canada or Eastern Canada? We endlessly chase our tails worried about how we’re doing relative to each other. And it drags us all down.

A really good Canadian song
We obviously need to track and discuss economic progress at different levels of the country. Cities, regions and provinces each have their own economic and political realities and are accountable to their local constituencies.
But beyond that, who the hell cares?
When something amazing happens in Quebec, we should all celebrate. 🎉
A big Series A in Newfoundland? Amazing! 🙌
IPO in Alberta? Pop open the bubbly. 🍾
That’s what other countries do. But in Canada, great achievements are inevitably followed by a wave of local media decrying the fact that province X is moving further ahead than province Y, cynical social media posts filled with doom and gloom, and complaints that someone’s city, region or province isn’t getting their “fair share.”

“I’m leaving you Vancouver. I’ve fallen in love with the economic development org in Brampton.” 🤦♂️
I’m over it. And you should be too.
Canada has the lowest GDP in the G7, yet instead of focusing on growing as a country, we argue over local attribution and incessantly compare our cities and provinces. (I can’t tell you how many hours of my life I’ve lost in conversations with Vancouverites comparing themselves to Toronto.)

“The East-Coast media doesn’t care about us. All they care about is Toronto…”
But it doesn’t have to be that way.
Instead of worrying about which province is ahead this week, or which city ranks higher in some arbitrary list put together by the marketing department of a second-tier publication, let’s figure out ways to work better together. Let’s celebrate the unique accomplishments of each city, region and province, while increasing collaboration across all stages and sectors of the tech economy.
Let’s stop treating tech in Canada as a zero-sum game.
I, for one, am cheering for every single entrepreneur and investor across Canada to win. And it’s not just me. The entire Panache team is unabashedly “Team Canada,” as are many others in our country's tech community.
When any company, city or province wins, we all do. 🇨🇦

How to Lose Credibility in 5 Easy Steps
Meeting an investor for the first time is a lot like going on a first date. Both founder and investor are trying to get to know each other and see if they are compatible.
As a VC, one of the characteristics I’m most focused on during that first meeting is trustworthiness. In order to invest in you, I have to believe that you’ll be honest and truthful with me. That means I’m paying a lot of attention to how you present yourself, your business and your backstory. I fully expect that you’ll position everything in the best possible light — you’re selling, after all — but there’s a line you must be careful not to cross.
Here are 5 ways founders can lose credibility with potential investors the first time they meet:
1. Misrepresent Revenue
Too many founders misrepresent key metrics like revenue in their initial pitch.
And I say misrepresent because it is always intentional (I was a first-time founder once – I knew exactly what each number in my deck meant). Examples include:
Showing GMV instead of revenue (but implying that it’s company revenue)
Showing registrations (signups) instead of actual users
Using non-standard time periods (e.g. quarterly recurring revenue instead of monthly recurring revenue)
In all my years, I have never seen a founder do any of these as an “honest mistake.” It is always a case of someone trying to make the numbers look better than they actually are — and it’s blatantly obvious to any experienced investor.
2. Claim Credit for Something You Didn’t Do
When talking about your past experience, don’t claim credit for something you didn’t do.
“I led project X” vs. “I was part of the team on project X”
“I sold a $500,000 contract to Y” vs. “I was the sales engineer on key deals, including a $500,000 contract with Y"
…and so on.

“…and then Steve asked me to personally oversee the “iPhone” project.”
Investors – particularly Pre-Seed and Seed VCs – are betting on the team. So you can be guaranteed we’re going to fact-check. And we are very good at finding back-channel references. When I call your ex-boss or ex-coworker, will they corroborate what you told me?
3. Namedrop Someone You Barely Know
This is annoying in any situation.
“I was hanging out with X the other day and they loooove what we’re doing."
“So, I was talking to Elon the other day…”
Guess what? That person you name-dropped? There’s a good chance I actually know them (or know someone who does).
And the minute we get done our first call, I’m texting them to find out what they really think of you.
There’s zero reason to ever do this with an investor. It’s certainly not going to impress us or help you close the raise. Instead, it’s a unnecessary reason for us to potentially say no.
4. Claim Someone is Investing When they Haven’t Committed
This one usually isn’t intentional, but it can be just as damaging.
Far too many founders name drop angel investors or VCs that haven’t actually committed to the round.
In the best case, you will come across as naïve and inexperienced (which still isn’t great), but you can also come across as a liar.
Again, it’s very easy for potential investors to fact-check this. And we will.

5. List Logos of Companies that aren’t Customers
This is another case where “rounding up” can hurt your credibility.
I’ve seen too many slides with logos of companies “we’re talking to” that are presented as if they’re customers. Or companies with free users presented as though they’re paying.
Guess what? I made this mistake once. And I got called out on it.
Every. Single. Time.

At the time we were fundraising, our revenue numbers weren’t great (we were still trying to figure out our business model) — but we had an amazing list of companies on our free product. Instead of owning the fact that we had a strong top-of-funnel, we tried to round up. It cost us credibility with a number of investors we met (you can read more about the mistakes we made in that fundraising deck here).
Meeting an investor for the first time can come with a lot of pressure. You want to put your best foot forward, but you must be cautious not to trip over the line between enthusiasm and embellishment. Just like on a first date, investors are watching for potential red flags.
If I think you’re exaggerating, misrepresenting yourself or lying, chances are we’re not going on a second date.
Is Your Revenue Real?

When Canadian founders ask investors what they must achieve to raise their next round, the advice often starts and ends with revenue:
“You need to get at least $25K in MRR”
“You need a minimum of 4 new clients and $100K+ in bookings”
“You need more than $250K/month in GMV"
But when it comes to raising from top Silicon Valley VCs, top-line revenue is just the tip of the iceberg.

A captivating picture of an iceberg from a management consulting deck
The best investors, particularly at Seed and Series A, focus on growth and growth potential when making investments decisions. They’re looking for early evidence of product-market fit and indications that the founders understand the needs of their customers. They want to know that if they invest, they’re adding fuel to a rocket that’s heading in the right direction 🚀
In order to do that, they need to understand how “real” your revenue is.
What Does that Even Mean?
Many first-time founders (and, sadly, more than a few investors) believe that reaching a certain level of revenue will instantly unlock the next round of funding. They expect to succeed at fundraising the same way they did at school: get the “correct” answers on the test and you pass.

When I grow up, I’m going to be a VC! 💪
Accelerators and startup personalities have compounded this misconception with overly simplistic concepts like “one metric that matters.” These approaches encourage founders to focus on a single metric (typically revenue) to the detriment of all others.
In theory, having the entire company focus on revenue is a great idea, but in practice it’s easy to get caught up in growth practices that are unsustainable. The top-line numbers look great, but they’re built on a house of cards.

Good investors understand this, which is why they dig deep.
Here’s what they’re looking for:
Let’s Start with the Basics
Note: The examples and definitions in this article are of SaaS businesses with monthly revenue, but the concepts apply to all startups.
Evaluating revenue starts with two metrics: the actual (current) revenue and the rate at which it is growing.
Revenue
Starting at the Seed stage, VCs almost always want to see a minimum level of revenue — whether they admit it or not. Depending on your business, that might be represented as MRR, GMV, bookings or something else, but every investor has a number in mind.
Paradoxically, the important part isn’t the revenue number itself — it’s the number of customers it represents. At each stage, investors are looking at how many people/businesses need your product badly enough that they’re willing to pay for it. Yes, the actual amount of revenue you’re generating from each customer is important (and we’ll get to that later) but investors first and foremost want to see evidence of product-market fit.
Revenue = objective evidence that you’re solving a problem that matters to someone
Revenue Growth Rate
The next thing investors want to understand is how fast your revenue is growing. Silicon Valley VCs are strictly in the business of “unicorn hunting” — investing in companies that can exceed a valuation of $1B in 7-10 years — and growth rate is key to achieving that goal.
In fact, having a numeric goal allows us to reverse engineer the rate of growth required to get there…

Let’s get out the calculator
Assume that your startup currently has $25K in MRR. You are trying to raise a Seed round from an investor who expects a valuation of $1B in 7 years. Let’s further assume that to achieve this valuation you’ll need to reach $100M/year in revenue. In order to do this, you must have an average monthly growth rate of:
$25,000 MRR x X^(12 months/year x 7 years) = $100,000,000 / 12 months
X^84 = 333.3333
X = 1.072 —> 7.2% MoM growth
This means you need to increase revenue 7.2% every single month for 84 months straight to reach your goal. 😅
The practical takeaway from this example is that top investors will typically want to see consistent double-digit MoM growth from early-stage startups. They understand that growth rate will ebb and flow (it’s okay to have off months while you’re fixing bugs and getting the product right), but the potential needs to be there.
Revenue Growth Rate = objective evidence that you’re solving a problem that matters to many people
So your current revenue is healthy and you’ve got consistent 20% MoM growth. Fundraising will be a slam dunk, right?
Not quite…
The Leaky Bucket Problem
Imagine you’re trying to carry water back-and-forth in a bucket with holes in it. You fill the bucket to the top each trip, but by the time you get to your destination only part of it is still there. That’s what happens with your revenue.

Something’s wrong here…
Each month, your team works hard to acquire new customers, only to find out that by the end of the month, some of your existing customers have churned. In the early days, this is a constant battle that highlights the evolution of three core functions:
Marketing - identifies potential customers (leads) and brings them in with the promise of a solution to their problem
Sales - converts them into paying customers
Product - fulfills their needs and keeps them happy
Revenue and revenue growth rate only prove the effectiveness of a company’s sales and marketing efforts. They demonstrate that the company has identified a meaningful problem (one that users/businesses are willing to pay to solve) and has figured out how to attract and convert customers. But without supporting evidence, they don’t prove that the company is actually solving the problem.
In fact, a poor product can be hidden for months — even years — by an effective sales and marketing function. As long as sales and marketing can bring in new customers faster than existing ones are churning, from the outside things look good.
Experienced investors have seen this many times, which is why they’ll dig into your churn next.
Customer Churn Rate
The first thing investors will look at is the customer churn rate — what percentage of existing customers are you losing each month?
At scale, your churn rate should only be one or two percent. For Seed and Series A startups, investors understand and expect it to be much higher. After all, the product is still really early. It’s likely missing key features and those that do exist are held together by duct tape.

The key question investors will ask: is the churn rate getting better?
Churn rate is a proxy for the quality of a product and its ability to solve customers’ problems. A decreasing churn rate demonstrates that you understand why customers are churning and are able to address those issues.
Customer Churn Rate = the percentage of customers who realize that your product doesn’t actually solve their problem
Revenue Churn Rate
Churn rate can also be calculated from a revenue perspective — what percentage of existing revenue are you losing each month?
This is a particularly insightful calculation when customers can generate different amounts of revenue (e.g. when a product has different pricing tiers, business customers can purchase multiple licenses, etc.).
The calculation for revenue churn rate is as follows:
X = MRR at start of month
Y = New monthly revenue from existing customers (upsells)
Z = Lost monthly revenue (from customers who downgraded and/or churned)
Revenue Churn Rate = ( Z - Y ) / X
Revenue Churn Rate = how happy are the customers who stayed relative to those who left?
Negative Churn (a revenue churn rate < 0) indicates that you are upselling enough to compensate for all revenue loss. In other words, your revenue is increasing even before you take into account new customers!

Net Revenue Retention (NRR)
Net revenue retention (NRR) inverts revenue churn rate. Instead of looking at the percentage of revenue you lost, it highlights the percentage that you kept — are you getting more new revenue from existing customers than you’re losing each month?
The calculation for net revenue retention is:
X = MRR at start of the month
Y = New monthly revenue from existing customers (upsells)
Z = Lost monthly revenue (from customers who downgraded and/or churned)
NRR = (X + Y - Z ) / X
If NRR > 100%, then you’re adding more revenue each month from existing customers than you’re losing (woo hoo!).

But wait…
Startups will often point to strong NRR as proof that they’ve got everything figured out, but it doesn’t actually do that. NRR > 100% is a great thing, but it can also be misleading, particularly in the early days when numbers are small, pricing models are changing, etc. It’s a start, but there’s more to dig into.
Net Revenue Retention = how leaky is your revenue bucket?
So How Real is Your Revenue?
After looking at churn, investors will turn their attention to the customers who stayed and the revenue they’re generating. How solid is that revenue?
Customer Lifetime
The first thing investors want to understand is how long, on average, are customers sticking around?
For an early startup, this isn’t an easy question to answer. It’s likely that a number of the customers who signed up in the first few months still haven’t left. That’s awesome, but it makes measuring customer lifetime quite challenging (and has led many a founder to overestimate how good their product is).
I find it helpful to think about three distinct cohorts:
New customers who fail to onboard or quickly realize that the product isn’t for them
Customers who stay for more than one renewal period and then churn
Customers who haven’t yet churned
Customers in category (1) consist of two main groups:
Customers for whom the product didn’t match marketing (they came because the marketing spoke to them, but the actual product didn’t solve their problem)
Customers who churned during — or shortly after — onboarding (they failed to complete the tasks needed to become an “active customer”)

Most investors will look at churn rate for this group but not include them in lifetime calculations — as they were never really customers. As a subset of churn analysis, understanding this particular cohort provides an indication of how effective onboarding is (including the initial impression new users/customers have of the product) and how aligned product and marketing are.
New User/Customer Churn = how good is your onboarding and does product deliver on marketing’s promise?
The second category (customers who renewed at least once and later churned) is the next step after NRR for analyzing progress towards product-market fit. How long did customers stay on average? Is that period getting longer over time? When customers do leave, why did they churn (and how easily can the underlying reasons be addressed)?
Customer Lifetime = how long before customers reach the limit of your product?

As founders, the more you understand this category, the better. During fundraising, presenting exit interviews/surveys, cohort analysis and other supporting evidence can go a long way to convincing investors that you’re on the right path, even if the numbers aren’t great.
Average Revenue Per User (ARPU) / Average Revenue Per Customer (ARPC)
The next piece of the puzzle is how much revenue are you generating per customer (user, business, etc.)?
The calculation here is fairly straight-forward:
For B2C SaaS businesses: ARPU = MRR / number of individual customers
For B2B SaaS businesses: ARPC = MRR / number of business customers
Average Revenue Per User/Customer = how much will customers pay you each month to solve their problem?
Lifetime Value (LTV)
The lifetime value of a customer (LTV) is how investors evaluate product from a revenue perspective. How much revenue, on average, is generated from each customer before they churn?
The basic calculation for lifetime value is as follows:
LTV = ARPU (or ARPC) × Customer Lifetime
But since we don’t actually know customer lifetime yet, we can approximated by inverting the customer churn rate:
LTV = ARPU (or ARPC) / Customer Churn Rate
Customer Lifetime Value = how much do customers value your product as a solution to their problem?
Is it Sustainable?
The final question on the minds of investors digging into revenue is one that is often misunderstood: is it sustainable?

As a founder, the mere existence of this question might seem preposterous — the success of startups is very much predicated on their ability to do things that don’t scale. But when it comes to revenue, long-term sustainability is crucial.
Returning to our leaky bucket analogy, investors ultimately want to know whether or not your ongoing efforts to “fill the bucket” can lead to long-term success. Given sufficient time and resources, can this business become a billion-dollar company?
This boils down to three questions:
Is there enough water to continue filling the bucket (is the market big enough)?
Can you make the bucket better (by improving the product and achieving product-market fit)?
Can you repeatedly fill the bucket in a sustainable way (is the business model long-term profitable)?
The answer to this final question is often the difference between an oversubscribed round from top VCs and struggling to raise anything.
Cost of Acquiring Customers (CAC)
The first metric investors will focus on is your cost to acquire new customers (CAC). This is the average cost to acquire each new customer, inclusive of both sales and marketing.
Customer acquisition cost is calculated each month, as follows:
CAC = (total sales costs for the month + total marketing costs for the month) / number of new customers for the month
For purely self-service SaaS businesses, there may not be significant sales costs. However, if anyone in your company (other than customer support) is actively talking to leads as part of the sales process, you need to include those costs in your calculation.
Cost of Acquiring Customers = how must do you spend to acquire each new customer?
LTV / CAC: The Ultimate SaaS Metric
Dave Kellogg once described the ratio of Customer Lifetime Value to Cost of Acquisition as The Ultimate SaaS Metric, and in many respects it is. This ratio tells us how profitable each customer is:
Assume that the cost to acquire each new customer is $100 and that the lifetime value for each customer is $500. This means that every new customer is worth $400 in gross profit!
LTV / CAC = $500 / $100 = 5
In the early days of most startups, LTV/CAC is less than 1. This reflects both a high churn rate (since the product is still very early) and a high cost of acquisition (having neither zeroed in on the target customer nor figured out how to acquire them cheaply).
Over time, investors will expect to see this ratio improve — however, this isn’t a case where bigger is always better. An LTV/CAC ratio of 3 is considered good. Too much higher and investors will worry that you’re being too cautious in your growth (once you reach a certain level, a portion of your marketing spend should always be directed at discovering new markets, which will increase your average CAC).
Putting it all Together
By now, you should have a sense of just how deep top investors will go to understand how “real” your revenue is. They want to understand:
How fast is top-line revenue growing
How “leaky” is your revenue bucket
Is your understanding of your customers improving
Is your ability to solve their core problems Improving (is product getting better?)
Is the problem you’re solving important enough that customers will pay a meaningful amount to solve it
Is your business model long-term sustainable
Investors don’t expect you to have it all figured out, but they absolutely expect you to understand and be able to articulate your progress on each of these questions. That means that you — the founder — need to deeply understand your revenue and business model, even if the numbers are still small.
Far too many founders think it inappropriate that early-stage VCs dig into revenue numbers in such detail. Hopefully, this post helps you to understand that it isn’t so much the revenue that’s important to investors, but what it represents:
Objective evidence that you might actually be able to pull it off.

Canadian Founders Need to Get Out of Canada

Before moving back to Canada in 2020, I spent 5 years immersed in emerging startup ecosystems around the world. From Japan to Oman, Scotland to Egypt, I had the privilege of collaborating with founders, investors and other supporters of dozens of up-and-coming tech hubs.

Launching the first ever tech accelerator in Muscat, Oman
Beyond access to capital, the most impactful thing I saw move the needle in every one of these communities was access to knowledge, networks and best practices from more advanced ecosystems.
Silicon Valley founders have long come to terms with the idea that if you ask 10 different people for advice, you’ll get 10 contrasting opinions. Not so much in emerging ecosystems. In fact, the experience for many founders in smaller tech hubs is the exact opposite: ask 10 people for advice and you’ll get the same opinion 10 times. Sometimes that advice will be good and sometimes it won’t – but without any diversity of perspective, you simply can’t tell.
For founders, investors and supporters of emerging ecosystems — and, yes, Canada is still very much an emerging ecosystem — getting access to diverse perspectives from outside of your “bubble” is one of the most powerful things you can do. At the recent CDL Super Session, Rhiannon Davies, Founding and Managing Partner of Halifax-based Sandpiper Ventures, eloquently summed this up:
We know that diversity of thought is important and that cross-fertilization of ideas breeds innovation.
Thinking outside of the box is easier when not everyone comes from the same box.

Thinking outside of the box?
I’ve previously written about why “getting out of Canada” is important for investors, so now I’ll take the founder’s viewpoint.
Why Does It Matter?
When you’re first getting started as a founder, supporters in your local ecosystem mean everything. They help you get off the ground, can provide you with advice, anecdotes and direction, not to mention a shoulder to cry on should things go sideways (and they will). But their experience and advice can also be limiting, as it’s frequently through the lens of a very local experience.
If you never went away for college, then your opinions on schools in other cities are just that: opinions. Same thing in business. Unfortunately, far too many people pass off personal opinions as fact (with their conviction generally increasing with age and personal success). In tech, this often means loud declarations of “advice” based in large part on Twitter and TechCrunch.
Founders, particularly first-timers, rarely question the perspectives that come from older and more experienced founders, investors and others in their ecosystem. Even well-meaning advice (which, to be clear, the vast majority is), it can lead founders down the wrong path if they don't take into account the local context from which it stems.
Canadian founders, in particular, seem prone to this.
Here’s the thing: it’s actually not that hard to get outside perspectives. You just have to know where to look.
A Tale of Two Conferences
A few years ago, I spoke at RiseUp Summit, one of the leading early-stage startup conferences in the Middle East (think Montreal Startupfest but in Cairo).

It was really, really hot that day…
After walking off stage, my good friend and host, Sharif El-Badawi, suggested we head to the nearby food trucks to grab lunch (yes, even Egyptian conferences have food trucks). But he warned me: it would take us about an hour to get there. I was utterly confused because I could see the food trucks from where I was standing — they couldn’t have been more than 200 ft. from the stage. Sharif must have seen my perplexed look, because he chuckled and said, “You’ll see.”
A moment later, we stepped off of the stage and were immediately swarmed by dozens of onlookers from the crowd. I prepared myself to be pitched on mass by founders hoping for an investment from a Silicon Valley VC. But that wasn’t what they wanted.
Patiently, politely — but insistently — the founders one-by-one asked for my advice.
“We’re a food delivery business. For the first year, we were growing 10% MoM, but lately it’s stalled. What should we look at?”
“We’re trying to decide whether we should expand into other countries in the MENA region or if we should start looking at Europe. What would you do?”
“We’re finding it really hard to raise pre-seed funding from local investors. Can you give us advice on where we should look or what we could do differently?”
And so on.
True to Sharif’s prediction, we spent nearly an hour standing there answering questions. The founders were all profusely thankful for our time (and many made sure to track us down to ask follow-up questions during the event).
To these founders, each speaker was a resource that could potentially help them take their business further. And every single one took advantage of the opportunity.

The main stage audience at RiseUp Summit
By contrast, last week I spent three days in Toronto for Collision, the massive startup conference which this year boasted more than 35,000 attendees (including over 1,500 startups). Despite walking around with a very large, very loud “Investor” badge around my neck, only two founders approached me the entire time — both to pitch me for funding.
At this point, a bunch of Canadians will smugly respond by pointing out how great it is that we don’t interrupt people in public (inevitably followed by some anecdote involving a big Hollywood star who got to eat dinner at Cafe X without being harassed). That’s not what I’m talking about here. By all means, let Bobby Superstar enjoy his triple shot decaf oat milk latte in peace.

What I’m talking about is your business. And when it comes to your business, the best founders take advantage of every opportunity presented to them.
Get Out of Canada without Leaving Canada
Startup conferences are just one example of ways that you can get outside perspectives on your business. The internet is even better.
In a world of social networks and Zoom, you don’t actually have to leave Canada to “get out of Canada.” Heck, you don’t even have to leave your house. Today, the barrier to reaching out to people around the world, getting global perspectives and accessing global networks is almost zero.

Here are some ways that you can virtually “get out of Canada”:
Reach out on LinkedIn to founders of similar companies in other cities and swap experiences
Follow investors and advisors you look up to on Twitter, interact with their posts and slide into their DMs
Ask for introductions to investors you’d like to raise from in a year but, instead of pitching, ask for 15 minutes of their time to get feedback on your business and benchmarks for your next fundraise
Build your own audience by posting about your experiences and interact with your followers (you’ll be surprised how many people they resonate with)
If you’re a technical founder, contributing to open source projects and getting to know other contributors is a great way to build a global network
If you’re in Web3, join a relevant DAO and get to know other members
If you’re part of a global accelerator, like Creative Destruction Lab or Techstars, reach out (or ask for introductions) to mentors and founders in other cities
Ask your investors if there’s anyone they can introduce you to in other cities that could provide a new perspective on your business
The goal here is to get out of your local feedback bubble, physically or virtually. As founders, you should strive to seek out opinions, advice and benchmarks from other ecosystems. If you’re in Atlantic Canada, reach out to folks in Vancouver. If you’re in Vancouver, reach out to folks in San Francisco. And if you’re in Toronto…
…nevermind, we all know that Toronto is the center of the universe (j/k! 🤣)
You Keep Using that Word...
I can’t help but hear Mandy Patinkin’s voice in my head when some founders pitch me their startups. Not because of mistakes in language or grammar, but because many founders misunderstand how certain words and phrases are interpreted by investors.
Here are 5 of the of the most common phrases that founders and investors interpret differently.
This year marks the 35th anniversary of The Princess Bride, one of the funniest movies of all time. The most memorable line in the movie – which has spawned countless memes – comes from Inigo Montoya, who after hearing his boss Vizzini exclaim “inconceivable!” for the seventh or eighth time, declares:
I can’t help but hear Mandy Patinkin’s voice in my head when some founders pitch me their startups. Not because of mistakes in language or grammar, but because many founders misunderstand how certain words and phrases are interpreted by investors.
Here are 5 of the of the most common phrases that founders and investors interpret differently:
1. We Haven’t Spent Any Money on Marketing
See also: “All of our user acquisition is organic”
What Founders Think:
Our product is so great that users/customers are flocking to us. We haven’t had to spend any money on marketing…just imagine how awesome it will be when we do!
What Investors Hear:
We haven’t given a single thought to how we’re going to acquire users/customers outside of our personal networks.

If You Build It, They Will Come…
How To Do It better:
We haven’t done any paid marketing yet, because we were focused on building our MVP and had enough users in our [waiting list / referral list / etc.] to allow us to get meaningful user feedback. Once we finish fundraising, our #1 priority will be developing our go-to-market plan and user acquisition channels. In our early testing, the product has really resonated with [x, y and z personas]. We think we can acquire more users like that using [a, b and c strategies]. What do you think?
2. Our Pricing is Low Enough to Avoid Procurement
What B2B Founders Think:
Look how smart we are! We’re getting the most revenue possible while keeping sales cycles short. This is awesome!
What Investors Hear:
We’ve completely avoided going after bigger contracts that involve a procurement process / multiple decision makers / complex sales (in other words, we’ve been avoiding “real” enterprise sales).
This has two possible interpretations, neither of which is positive:
We still have to learn how to do enterprise sales, which is going to take time
We’re too scared to try “real” enterprise sales (which is going to cap our ACV)

How To Do It Better:
So far, we’ve intentionally priced our product below the procurement threshold so that we could gain a foothold with our target customers and prove out our MVP. We believe that there’s the potential for $x/year in revenue from some of these customers, which will obviously push us into longer and more complex sales cycles.
Coming out of this raise, our goal is to expand within those early customers while also targeting larger initial ACVs, both of which will require us to develop our “enterprise sales” muscle. What are some of the ways you’ve seen first-time founders accelerate their learnings around how to sell larger contracts into enterprises?
3. We Haven’t Started Monetizing Yet
What Founders Think:
A lot of founders seem to think that this is a “Get Out of Jail Free” card that lets them avoid any questions about revenue. If anything, it does the opposite. Unlike 5-10 years ago, today’s investors expect founders to start testing monetization strategies far earlier in their journey, particularly for B2B startups.
What Investors Hear:
We’re avoiding putting ourselves out there and finding out if we’ve actually built something people want to pay for. (This is akin to hanging out for weeks with someone you want to date, without ever getting the courage to ask if they want to go out with you.).

Some companies have valid reasons to not monetize by the time of their fundraise (e.g. products that are sufficiently complicated that a user wouldn’t reasonably be expected to pay at that point, consumer apps where monetization where network effects are key and scale is expected before monetization, etc.), but if you’re presenting a product that “solves” a customer need, complete with case studies, it’s hard to justify not charging at least some of them.
How To Do It Better:
Unless you’re just getting started, you should aim to start experimenting with monetization at least 3-6 months before your next fundraise. Even if the price is low, being able to demonstrate that someone (anyone) is willing to pay for your product is significant market validation for investors. You’ll also learn a lot about the difference between free users/companies and customers — data that can be included in your fundraising materials. For SaaS products, this can be as simple as switching from free to a 14-day trial. For enterprise customers, it means trying to go from free to paid pilots.
It’s scary, but at some point you have to put yourself and your product out there (and investors want to know that you’re willing to).
4. We Have No Competition
What Founders Think:
We’re the first ones doing this. Our product is so new/special/awesome that there’s literally no one in the world doing this!
What Investors Hear:
We don’t understand the market or our target customers. We’re not thinking seriously about the alternatives for what we do and are naively assuming that our product is magically going to win.

How To Do It Better:
In order to solve this problem today, users/businesses have to do [x, y and z], which has [a, b and c problems/drawbacks/costs]. We believe that we’re the first company to take our approach to solving this problem, but there are likely other startups looking at the same opportunity. Have you come across any others?
5. We’re Co-CEOs
This one isn’t very common, but when it hits it’s a doozy.
What Founders Think:
We work together so well as a team that we don’t need to assign labels to roles. We’re hitting all of our goals and this is awesome! We’ll figure it out later and it won’t be a big deal.
What Investors Hear:
We’re avoiding having the really hard founder conversations. (If as founders you can’t have the conversation about who’s the CEO, what else are you avoiding…?)

Note: In later-stage companies, co-CEOs isn’t entirely unusual. This works because roles and responsibilities can be clearly defined in mature organizations, which isn’t the case in startups. In early-stage startup, investors want to know who the “buck stops with.”
How To Do It Better:
Sorry to be the bearer of bad news, but on this one you have to put on your big kid pants, have those really, really hard conversations with your cofounder(s) and make a decision.
A handful of investors are okay with co-CEOs, but for the vast majority (particularly at the early stages), it’s a deal-breaker.

Take a deep breath and go for it…
Can Vancouver be the Next Austin?
Last week, I hosted the June edition of Webcouv3r, Vancouver’s monthly Web3 event. Following an engaging panel on the future of DAOs, no fewer than five people asked me some variation of the following question:
“How are we narrowing the gap between Vancouver and San Francisco?”
Since moving back to Vancouver, I’ve heard countless takes on this question and its naval-gazing cousins, “How can we get Toronto media to pay more attention to Vancouver?”, “How can we reverse Vancouver’s brain drain?” and “Why aren’t there more unicorns in Vancouver?”

Look at my belly button!
The next day, I flew down to Austin, Texas. Austin is famous the world over for music, BBQ and football.
It also happens to have a pretty good tech scene.

Downtown Austin
You know it doesn’t have? People constantly comparing Austin to other cities.
You don’t hear Austinites whining that New York doesn’t pay enough attention to them, that the government doesn’t give them enough money or that they don’t have as many unicorns as other cities. They know what makes Austin special and they’re unapologetically proud of it. When they talk about their city, they focus on what makes it unique, not what it lacks.
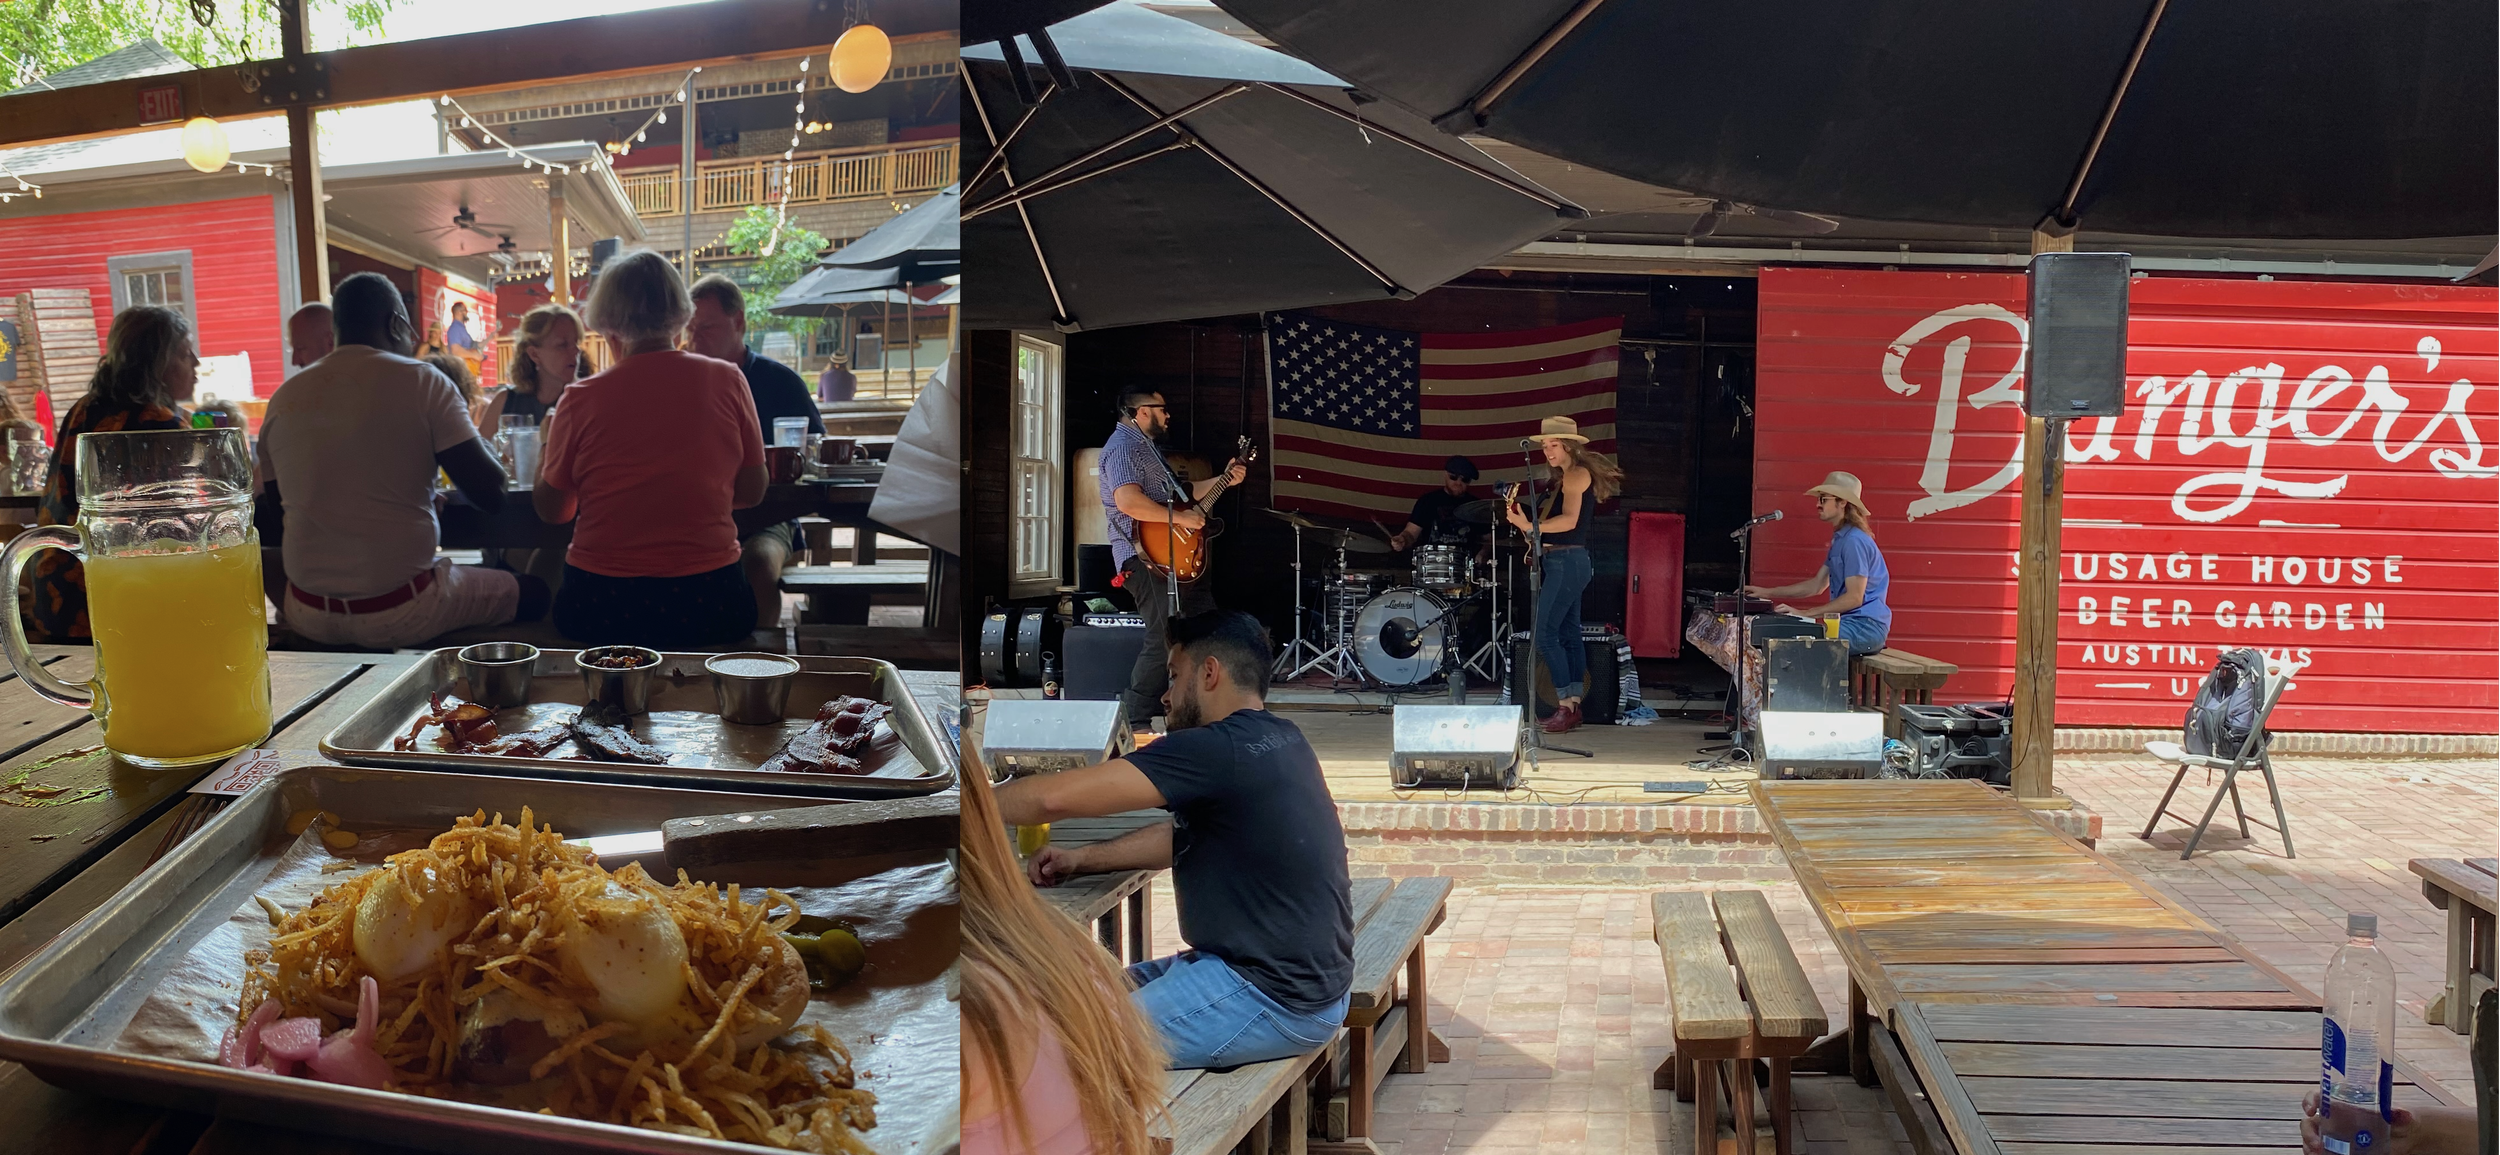
Brunch and blues
Imagine if Vancouverites could do the same thing.
Imagine if we stopped worrying about what people in Toronto think (or don’t think, because let’s be honest -- most people in Toronto spend precisely zero time thinking about Vancouver).
Imagine if we stopped complaining about a lack of government support.
Imagine if we stopped comparing.

Complaining about the government is the second most popular sport in Vancouver.
After complaining about gas prices.
That’s not to say that the there aren’t opportunities for improvement — there always are.
But Vancouver is the most beautiful city on the planet. You can ski the best slopes in the world, mountain bike in a near-mythical rainforest and swim in the Pacific Ocean. On the same day.
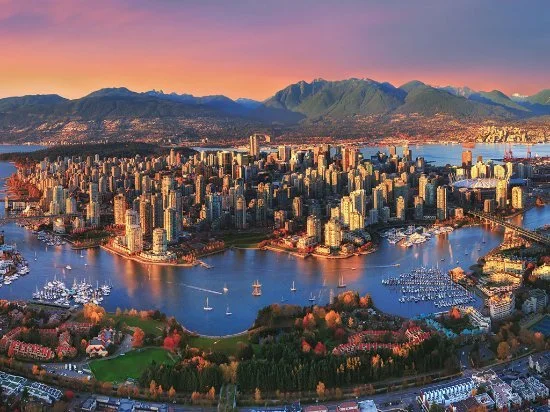
Are you kidding me?!?
Vancouver is also a small city. As such, it will never be the primary driver of the country’s economy, tech or otherwise. The first thought when you mention “Vancouver” to anyone around the world will never be “tech.”
And that’s okay.
You know what other city you can say that about? Austin.
The difference? People who live in Austin aren’t worried about it. They know know that when people think of their city, they think first and foremost about music, BBQ, festivals and all of the other weird and wonderful things that make Austin special. And if those people happen to be in tech, they’ll know it’s also a bad-ass tech city.

Kayakers on the Colorado River in downtown Austin
Vancouver has a fantastic tech scene and I genuinely believe that it has the potential to be a global leader in Web3. Some of the most consequential companies of this generation are already being built here. But even if that happens, when people around the world think about Vancouver, they’ll think first and foremost about its natural resources and lifestyle — skiing, hiking, mountain biking and all of the other wonderful things that make Vancouver special.
And that’s okay.

You can’t do this after school in San Francisco
People in tech don’t move to Austin because of its tech scene. They move there because it’s an amazing city and it has a great tech scene.
Similarly, nobody is ever going to move to Vancouver only because of its tech scene (and this is coming from someone who moved back to Vancouver after 18 years in San Francisco). People move here because it’s one of the best cities in the world to live and it has a great tech scene.
Let’s embrace that energy.
Let’s proudly make Vancouver the next Austin Vancouver.
By the Numbers
| Austin | Vancouver | |
|---|---|---|
| Population | 2.29 million | 2.46 million |
| Employees in Tech | 79,230 (7.5% of jobs) | 91,200 (8.0% of jobs) |
| Big Name Tech Conference | SXSW | TED |
| OG Tech Company | Texas Instruments | PMC-Sierra |
| New Hotness | ICON | Dapper Labs |
Hometown Band Locals Would Rather You Forget |
N/A (It's Austin) |
Nickelback |
…oh, and it case you’d like to know my answers to the questions at the top of this article:
“How are we narrowing the gap between Vancouver and San Francisco?”
We aren’t. And we never will. (And that’s okay.)
“How can we get Toronto media to pay more attention to Vancouver?”
Do something amazing that they can’t ignore.
Or, you know, stop worrying about it. 🤷♂️
“How can we reverse Vancouver’s brain drain?”
We shouldn’t try to.
It’s a great thing that ambitious young women and men are going abroad to learn and experience the world and do amazing things. Some number of them will come back (like I did) and they’ll bring with them all of that knowledge and experience that they never would have gained if they stayed here.
“Why aren’t there more unicorns in Vancouver?”
Because Vancouver is a small city.
At the end of the day, most startups fail and only a tiny fraction of them will become unicorns. Vancouver will have more unicorns, but they will always be few and far between. That’s not a critique or criticism of our local entrepreneurs or tech scene. It’s just the numbers.
And that’s okay.
Do You Still ❤️ Me?

When times are good and term sheets are flowing, founders don’t think a lot about whether or not their investors will follow-on in the future. But in times like these, when the pace of deals is slowing, it’s essential that founders know where they stand with their investors. And most don’t have a clue.
For many founders, asking an existing investor if they’re willing to follow-on is as intimidating and awkward as asking a partner if they still love you.
What if they say no…?
For others, the need to ask at all seems preposterous.
Of course, they still love me! Of course, they’ll follow-on…

As with any relationship, it’s important to check with your investors in on a regular basis. Unfortunately, the topic of follow-on investment rarely comes up during founder-investor check-ins. Only a handful of founders I’ve ever worked with have asked me about follow-on investment outside of an active fundraising process.

In startups, as in life, we usually don’t talk about money until we need more.
Let’s have “The Talk”

For each investor on the cap table, founders should know the answer to two questions:
What is your follow-on policy? (Under what conditions, if any, would you consider a follow-on investment -- and how much would that investment be?)
Where do I currently stand with you? (If I were to raise money today, would you invest?)
The answers to both of these questions can change over time — so you should check in on this periodically. VCs will generally have a consistent policy, but where you stand with them may ebb and flow. Angel investors, on the other hand, can vary wildly. Most don’t have a firm “policy” and where you stand can change both as a result of your progress and their personal financial situation.
Here are some questions that you can use as the basis for “the talk”:
Can you tell me what your follow-on policy is?
When we raise our next round, will you follow-on?
Under what conditions would you consider following on?
If we needed an injection of capital today, would you participate?
What percentage of companies do you follow-on with, and under what conditions?
Will you lead or participate in a bridge round?
If you haven’t explicitly asked your investors some variation of the above questions, consider doing so next time you speak with them (and not just with VCs, but all of your investors). Ideally, you should maintain a tally of where you stand with each investor and the total amount of capital available from existing investors under various scenarios.
The Answer Is Probably “No”
Here’s the tough part: for the vast majority of startups, under most scenarios the answer to these questions will be “no.”

The reality is that most angel investors don’t follow-on. Many VCs only follow-on when there’s a new lead investor. And even investors who do follow-on can’t do so with all of their investments.
This can seem really unfair. As founders, we long to believe that our investors will “have our backs” no matter what, but the reality is that very few investors (VCs or angels) have the ability to do that financially. Part of this is limited resources. Part of this is investment strategy.

A typical VC investment strategy
For VCs, in particular, follow-on decisions are driven in large part by a formal investment strategy that was decided long before they met you. Sometimes that strategy involves multiple rounds of investment, but frequently it doesn’t. And even when it does, it’s often only in the case of “up rounds” (rounds led at a higher valuation, typically by a new investor). So don’t be surprised if you check in with an investor, only to be told “we don’t do follow-on investments” or “we don’t do bridge rounds.” A lot of investors don’t.
For those who do, they generally only follow-on with a subset of their portfolio. A Seed VC’s investment strategy might look like this:
We will invest in 20 Seed-stage companies over three years. Of those companies, we will set aside funds to do our Series A pro rata in 10 companies and participate in extensions / bridges for up to 3.
What this means is that if more companies need bridges/extensions than the investor has the capacity for (which is often the case), the founders are competing with other companies in the portfolio for that follow-on investment.
What are you Really Saying?
When an investor with the ability to follow-on chooses not to, it means one of three things:
They have lost confidence in the company
They have not lost confidence in the company, but they don’t believe that further investment will change the outcome
They have not lost confidence in the company, but they believe that they will generate better returns by allocating the follow-on capital to a different company
If an investor tells you that they’re not (currently) willing to invest further, don’t be afraid to ask for an explanation. It’s likely to be an awkward conversation, but if done in a professional manner, it can lead to some potentially impactful insights
At one point when I was running DataHero, I spoke with our lead investor (Ryan McIntyre from Foundry Group) about their feelings on the company. He admitted that they were mixed. What followed was a very honest – and difficult – conversation, in which he shared that he did not have full confidence in me as a CEO, due in large part to how I managed board meetings. This caused me to re-evaluate certain aspects of my communication style and how I ran board meetings.
Ultimately, Foundry led both our Seed and Series A rounds.
Most investors are more than willing to explain in detail their follow-on policy and where you currently stand -- but they generally won’t unless asked. As a founder, this is crucial information and I encourage you to ask these questions of all of your investors.
We Won’t Follow-on Does Not Mean We Don’t Love You
This is a really, really important point.
Far too many founders, when told by an investor that they won’t follow-on, react with anger or frustration. Being told by an investor that they won’t invest further can feel like rejection.
You don’t love me anymore!
This is the point at which cynics react with arguments about VCs “showing their true stripes,” only investing when times are good, etc. I find this to be an incredibly unhelpful perspective, because it only reinforces the anger and resentment felt by founders going through tough times. While a “no” can certainly represent a loss of confidence by the investor in some cases, oftentimes a follow-on investment was never actually in the cards.
Regardless, an investor telling you that they won’t follow-on with additional funding does not mean that they’re abandoning you.
Investors want you to succeed – their returns depend on it. Whatever resources they were providing you before “the talk” (time, mentorship, introductions, etc.) are still available after. I’ve seen far too many founders react to the perceived slight of an investor saying no by turning away completely from the investor. That’s generally not the best course of action.
None of this is Easy
Let’s be clear – nothing about this is easy. It’s a difficult topic that strikes at the heart of the often-significant gap between the expectations of founders and investors. But it doesn’t need to be that way. Knowledge is power and, in my humble opinion, you’re far better off knowing where your investors stand in terms of follow-on investing long before you need the money.
So if you haven’t already, reach out to your investors (all of them!) and ask where they stand.

No, VCs Don't "Skip" Diligence

Every time there’s a slowdown in VC funding or a well-funded startup fails, a torrent of people rush to proclaim that investors hadn’t done their homework. It’s like clockwork. As markets have pulled back over the past few weeks, the usual suspects have come out of the woodwork with their “gotchas” and “I told you so’s.”

On Monday, the founder of Eco added some major fuel to the fire when he claimed that a recently-funded competitor had copy-pasted their entire business.

To be clear, if the claims made by Eco turn out to be true, it’s beyond unethical. It’s sketch AF. But that’s not the point of this post.
The purpose of this post is to obliterate the myth that VCs skip diligence in hot markets.

Santa can take a flame thrower to VC myths. Because Santa is 100% real.
Let’s Rewind for a Minute…
Before I get too ahead of myself, I want to be clear about what I’m referring to. When the fundraising market is hot, deals happen faster. In a strong market, more capital flows into the ecosystem, which results in increased competition to invest in the best startups. It’s also important to highlight that founders have become significantly better at fundraising in recent years. The best founders understand how to orchestrate a competitive process that maximizes their leverage and optionality.
Put these two things together and investors, on average, have less time start-to-finish to make a decision.
So What?
There’s a dangerous myth stemming from the above dynamic that permeates many founder and investor circles: in a hot market or a competitive deal, big-name investors “skip steps.”
The implication of this myth is that the only way a deal can be done in a competitive, fast-moving scenario is by cutting corners.
Here’s the thing: I don’t know a single legitimate VC that doesn’t do their homework. Not one.
Actually, I’ll put it even more bluntly: the idea that any VC worth their salt is going to write a multi-million dollar cheque without doing diligence is stupid. Saying so might get you a lot of likes on Twitter, but it’s flat out wrong.

VC Logan Bartlett poking fun at the situation
But Really…So What?
At this point, you’re probably wondering why I’m making such a big deal about this. I promise it’s not because I desperately need a gold star.

Look at meeeeeee! I did my diligence 😄
The fact is, buying into and propagating this myth is dangerous for both founders and investors.
Why It’s Dangerous for Founders
When founders buy into the myth of investors skipping diligence, it provides an excuse to not look in the mirror.
“Company X raised $5M and our product is way better than theirs, so…”
Far too many founders rely on this myth to justify continuing down a path akin to banging their head against a wall. They continue to fundraise with a misguided belief that they can somehow “trick” investors into not noticing their gaps. If they just tell the story differently or meet an investor that “gets it,” the problems in their business won’t matter.
That’s just not the way it works. (Want to see a concrete example? Check out my own Seed deck from 2013).
To succeed at fundraising — especially in a market like the one we’re in — it’s essential that founders be self-aware and recognize when fundamental issues are causing investors to lean away. Although it frequently takes 100 “no’s” to get a “yes” when fundraising, often the solution is to pause and address the underlying issues that investors see as risks.
Why It’s Dangerous for Investors
Investors….well, frankly, investors should know better.
It blows my mind how frequently I hear Canadian investors talk about Silicon Valley VCs getting caught up in FOMO or cutting corners to win deals.
Please.
Do you really believe that partners at the most successful, most sophisticated firms in the world are skipping steps to win deals while noble, disciplined Canadian VCs are the only ones doing things the right way?

If you believe that, I’ve got something to sell you…
It’s an arrogant perspective, but why is it dangerous?
For the exact same reason it’s dangerous for founders: it provides an excuse to not look in the mirror.
Believing that competitors skip steps is a great excuse for investors to not improve. “They’re lazy, so why do I need to get better?”
You might now be wondering why I would call this out. While I certainly might benefit in the short term from this type of behaviour, it’s not long-term good for me, because it’s not long-term good for the Canadian ecosystem. For Canada to thrive, we need everyone across the ecosystem to continue to get better — founders and investors alike. That means not resting on our laurels and not giving into convenient myths.
If VCs Aren’t Skipping Steps, What’s Happening?
The same thing that happens in every startup when there’s a deadline: all hands on deck.
In a startup, when there’s a big product release or a customer emergency, the whole company rallies to get it done. The same thing happens in top-performing VC firms. Partners, associates and analysts rally around hot deals so that they can complete the necessary diligence in time.
This doesn’t mean that the firm will research every possible aspect of a startup. It also doesn’t mean that investors aren’t prone to FOMO (they certainly are). What it does mean is that they will prioritize the diligence they feel is necessary to gain conviction around the deal. The best VC firms can do this very, very fast.

For non-deep tech companies, technical diligence has become less important to many pre-seed and seed investors
This ability to prioritize diligence and rally behind hot deals is a skill that Canadian VCs, for the most part, haven’t had to develop because we haven’t historically had the same level of competition as in the US.
We’re starting to see meaningful evolution in Toronto, but the majority of investors I’ve encountered still parrot the myth of cutting corners.

NGMI
What About Eco?
As of this post being published, that story is still in development. There are a lot of knee-jerk reactions that the VCs who invested in their competitor didn’t do their homework, should have known about Eco, etc.
But here’s the thing: the competitor hadn’t yet launched a public website (fairly common for Pre-seed and even Seed companies). Which meant unless the investors had personally seen (and remembered) Eco’s pitch deck, there would be no way to discover the supposed copy-and-paste.

The Genius of Creative Destruction Lab
If you’re a founder in Canada — or are involved in the Canadian tech scene in any way — then you’re familiar with the letters CDL. The Creative Destruction Lab helped create more than $19 Billion in equity value. And it's completely changed the Canadian tech landscape.
Last Thursday night, I sat in a dining room in St. John’s, Newfoundland and Labrador, the eastern-most city in North America. On a jagged cliff overlooking the unforgiving Atlantic sea, a group of CEOs and investors from across Canada dined on moose (seriously) to celebrate the conclusion of two days of meetings. But we weren’t there to meet with each other. Everyone in the room had spent the past 48 hours focused on a shared goal: mentoring 30 of the most promising startups in Atlantic Canada.

Signal Hill, where Guglielmo Marconi received the world’s first transatlantic wireless signal in 1901
If you’re a founder in Canada — or are involved in the Canadian tech scene in any way, shape or form — then you’re familiar with the letters CDL. The Creative Destruction Lab is more recognized across Canada than any other accelerator, save maybe Y Combinator. In 10 years, the program has helped create more than $19 Billion in equity value. That’s right, $19 Billion.
And it costs founders nothing to participate. 🤯

Awkward selfie with Adam Keating, CEO of St. John’s-based CoLab (Panache portfolio company and CDL Atlantic graduate, who recently announced a $17M Series A)
CDL’s model - a cross between a traditional accelerator and Shark Tank – was dreamt up not by a serial entrepreneur or well-known investor, but by a business school professor who was pissed off that Canadian PhD students kept getting hired away by Silicon Valley companies. Ajay Agrawal was determined to change the status quo. His audacious experiment to create a “marketplace for judgement” has completely changed the Canadian tech landscape.

The “Main Room” at CDL Montreal
I first attended CDL in Toronto in 2017 while I was with 500 Startups. And like so many people before and after me, I was blown away by what I saw. Billionaire CEOs, top investors and world-renowned subject matter experts sitting in a single room, laser focused on mentoring first-time founders.
Soon after, I found myself flying back and forth between San Francisco and Montreal for the CDL “AI Stream.” Two years later, I began adding regular trips to my hometown of Vancouver for CDL “Prime.” The year following, it was CDL-Atlantic, a rotating program held across Canada’s four maritime provinces. And my experience was far from unique.
Creative Destruction Lab’s approach to mentorship has tapped into a desire that many of us in business and tech have to do more. To make Canada better. Yes, many of the people involved in CDL find some manner of business value in participating (investors see deal flow, corporates meet potential vendors and everyone benefits from the networking), but that’s not the driving reason why so many CDL “Associates” fly across the country (and, increasingly, around the world) every 8 weeks.
As the program has continued to expand, so has the impressive list of CDL Fellows and Associates, which not only includes prominent CEOs and investors but also astronaut Chris Hadfield, Turing Award winner Yoshua Bengio, economist Joshua Gans and many more.

Astronaut Chris Hadfield mentors a group of founders at CDL Toronto
And CDL’s ambitions haven’t stopped with startups. They’ve added a program specifically designed to get more high school girls into entrepreneurship, created streams for everything from space to cancer research, and expanded beyond Canada’s borders to the US, UK, France and Estonia. Of course, there have been some growing pains along the way, but the core mission of CDL — to “Build Something Massive” — continues to strike a chord with many across the Canadian ecosystem.
Being back in person for CDL after two years of Covid — two weeks ago in Montreal and last week in St. John’s — reminded me of how special Creative Destruction Lab really is and what a game-changer it’s been for Canada.
I can’t wait until next year.
Applications are currently open for CDL’s 2022/23 cohort. Click here to learn more and apply.
The Sky is Falling! ...or is it?

In recent weeks, public markets have fallen dramatically, high-flying startups have had significant layoffs, and VC talking heads are rushing to proclaim that the good times are over. But is the sky really falling? And, if so, what should you do about it?
First a bit of an explanation of what’s going on:
In recent weeks, public markets have fallen by more than 20%. I won’t explain why (since that’s a whole other rabbit hole), but it’s causing a domino effect deep into Startupland:


When public markets pull back, companies that were planning to IPO put those plans on hold. This causes late stage investors (Series C and later) to change their behaviour for the two reasons highlighted above:
Their investment decisions are driven in large part by calculations around time-to-IPO, and that math is now unclear
They must determine whether or not they need to redirect additional capital to existing investments in order to prolong their runway and spend time supporting those founders as they navigate a new reality
The change in late stage investor behaviour cascades down to earlier investors (Series A and B) as their pace of investment slows down. Rounds take longer, are less competitive and result in lower valuations (which is less exciting to both startups and their investors). Eventually, this comes all the way back to the early stage market.
“But Chris!” you ask, “I keep hearing about how VCs have all sorts of dry powder.”
It’s true — in recent years, VCs have raised more money than ever before. But here’s the thing…that money isn’t actually in our bank accounts 🙈

Unlike startups, when VC funds raise money, we get commitments from investors (not actual 💰). The money is later wired as installments over time — typically 3 - 4 years. Those commitments are normally solid, but when public markets fall quickly cash flow can become an issue for individual investors and corporations alike. Believe it or not, it isn’t uncommon in a downturn for VCs to “call capital” from investors, only to have some of them default on their commitments.
This isn’t something that’s normally talked about because, even when it does happen, it usually isn’t a big issue. But over the past few years, there’s been an explosion of new funds, especially in the sub-$25M range (solo funds, operator angels, rolling funds, etc.). Unlike established funds like Panache, new VCs depend almost exclusively on individual investors and, as a result, are disproportionately impacted by the uncertainty caused by economic downturns. This can lead to liquidity issues, causing those funds to slow down their pace of investment.
So what we’re seeing play out across the investor landscape right now is akin to what happens if you’ve been driving your car at top speed in the pouring rain (a bit reckless, right?). Suddenly, you see brake lights from a slowdown up ahead and quickly pump the brakes to avoid crashing, with everyone else around you doing the same. Eventually, we’ll all come to a stop, take a breath, and get going again, but right now the cars are still skidding around.

So what does this mean for you, my dear founder?
1. Don’t be Cute
First off, this isn’t the time to be cute. While it’s entirely possible that this will blow over, all signals indicate that the downturn we’re currently witnessing will be measured in months, not weeks. So if you’re currently in the middle of a fundraising process, I recommend that you close your round as soon as possible. Don’t play games, get the money in the bank.
2. Hold Off on Fundraising
If you were thinking about fundraising but have the runway to delay, consider holding off until the fall. The current uncertainty will, at a minimum, cause rounds to take longer (leading to less competition and lower valuations for most companies), so you’re better off waiting until everything settles down.


If fundraising wasn’t on your radar to begin with (either because you recently raised or are cash flow positive), then tune out the noise, put your head down and get to work. It may even be an opportunity to get aggressive while others are pulling back.

3. Extend Your Runway
Every founding team should talk candidly about things they can do to extend their runway. Most founders today (and many investors, for that matter) have never been through a prolonged economic downturn. In a real downturn, not only can it be harder to raise funding, but customers can downgrade or, worse, simply stop paying.
When the 2008 financial crisis happened, a major US bank with whom we had a 7-figure contract called us up and matter-of-factly stated that they were not going to pay us. They knew it was a breach of contract but they also knew we could not afford to sue them.
Damn.
These things really happen and, when they do, they happen fast. So take the time to think about ways to extend your runway and get ahead of the market. That can mean cutting costs. It can mean enticing monthly customers to pre-pay for annual contracts. It doesn’t mean you should panic, but in a downturn, cash is king.
So what are we doing at Panache?
We haven’t slowed down our investing, that’s for sure. As Pre-Seed / Seed investors backed by some of Canada’s largest institutional LPs, we’re relatively isolated from shifts in public markets and continue to invest in promising companies across the country (in fact, we signed our latest investment yesterday).
However, we’re also taking the time to check in with all of our portfolio founders as they navigate this new reality.
Last week, we did a full top-to-bottom review of the 100+ companies in our portfolio to understand where each company is in terms of runway. We then reached out to all of those with 9 months or less to see if there’s anything we can do to help. Over the coming weeks, we’ll hold calls with founders across Canada to share our perspective on what’s happening and what actions (if any) they might want to consider.

The fact remains that no one knows how long this downturn will last. Are the brake lights up ahead a brief slowdown or a serious traffic jam?
My personal mantra is “hope for the best, plan for the worst” and while we wait to find out, this is a great time to do just that.
How to Pitch Like an American
Americans are born confident. So much so that the rest of the world often mistakes it for arrogance. But in many aspects of life, American confidence — born of a deeply held belief that success is manifest destiny — is an unfair advantage.
In fundraising, it’s a game-changer.

Americans are born confident. They pretty much come out of the womb oozing confidence. So much so that the rest of the world often mistakes it for arrogance. But in many aspects of life, American confidence — born of a deeply held belief that success is manifest destiny — is an unfair advantage.
In fundraising, it’s a game-changer.
As Canadians, we’re taught from a young age to be humble. We’re famous the world over for apologizing for everything.

In most contexts, our national propensity to say ‘sorry’ ends up little more than the butt of well-meaning jokes. But in the context of pitching, our collective humility is often mistaken as weakness, particularly by U.S. investors.
Why?
The average investor meets dozens of founders each week. For investors based in Silicon Valley, the vast majority of those founders are — you guessed it — American. VCs are only human (believe it or not) and humans are prone to pattern match. If I meet with confidence-oozing founders who pitch as though their success is preordained every single day, when I talk to anyone who doesn’t exert that same level of confidence, they will likely come across as weak, inadequate or lesser.
Sure, you can argue that as an investor, I should know better, but the reality is that most VCs look to invest in companies that feel inevitable. Projecting confidence is a big part of that.
Here are 3 ways that even the most mild-mannered Canadian can project confidence when pitching:
1. Answer First, Explain Second
When asked a question, most Canadians (and, in fact, most people from across the Commonwealth) respond using the format <explanation>, <answer>. As in:
Investor: What is your revenue?
Founder: Well, we just started monetizing a few months ago,…
By the time you eventually answer the question, I’m convinced that you’re making excuses. So even if the answer is awesome, I’ll have already discounted it. Instead, answer the question directly, then add any context:
Investor: What is your revenue?
Founder: We’re currently at $1,500 MRR. We just started monetizing a few months ago,…
Even in written form, the second version clearly comes across as more confident than the original.
2. Answer First and Don’t Explain
Want to project even more confidence? Hold off on providing any explanation until/unless the investor asks:
Investor: What is your revenue?
Founder: We’re currently at $1,500 MRR.
For a lot of people, this is really hard. The need to justify answers and provide additional context can be almost overwhelming, but keep your mouth shut! If the investor wants to know more, she’ll ask (I promise).
In many cases, you’ll be surprised to find that investors don’t actually care about the details you often dive into. Most people neither want nor need all that context. Being concise projects confidence. For founders who feel like they talk too much, this is a great strategy for staying out of the weeds, which is especially important in first meetings.
3. Be Proud of Every. Single. Answer.
Many founders I’ve talked to feel like fundraising is a school test: if I give the right answers, then I’ll pass the test and the investor will give me money. But that’s not how it works.
Yes, VCs look at metrics like revenue when making investment decisions, but they also know that in order to make a billion dollars you have to start with one.

For most investors, there is no “right” answer to the questions they ask. I’ve passed on startups making millions in ARR with the same conviction that I’ve invested in pre-revenue companies. The questions I ask help me to understand where you are in your startup journey, in order to figure out if your company (at its current stage) is a match for my investment thesis.
What I am definitely looking for is confidence in your answers. That means being proud whether you’re at $100 MRR or $100,000 MRR. Whether you’ve just signed your first pilot agreement or closed your 100th customer. The more confident you are in sharing your journey with me (both in terms of where you’ve been and where you’re going), the more confidence I will have in you. And I need to be confident in you in order to invest.
Be Hungry and Humble
This isn’t to say that confidence is everything. There’s a fine line between confident and cocky.
In my experience, the best founders are “hungry and humble.” They have supreme confidence in themselves, their team, and the opportunity they’re going after, a hunger to win, and the humility to learn and absorb new information along the way. In other words, the confidence of an American and the humility of a Canadian.
Hmm…on second thought, go out there and pitch like a Canadian. An Olympic gold medal-winning Canadian.

Wow, Did My Pitch Deck Suck
Long before I was a VC, I cofounded DataHero, the world’s first cloud BI company. I recently came across one of our old fundraising decks and boy, did it suck! Let’s look at all the mistakes we made in that deck.

Since becoming an investor, I’ve reviewed thousands of startup decks and helped hundreds of founders prepare their pitches. But long before I was a VC, I cofounded DataHero, the world’s first cloud BI company. I recently came across one of our old fundraising decks and boy, did it suck!
Let’s take a trip down memory lane and look at all the mistakes we made in that deck.
I’ll review the deck in two passes:
A Slide-by-Slide Review
An Overall (Holistic) Review
After that, I’ll conclude by sharing what the outcome of the round was.
Note: This deck is for a $3.5M “Series A” that we raised in late-2013, following a $965K “Seed” round in 2012. By today’s standards (for both company stage and round size) this would be considered a Seed round (with the prior fundraise our Pre-Seed).
As such, the feedback and recommendations in this post are from the perspective of a Seed investor reviewing a Seed deck.
Here is the full deck for DataHero’s 2013 fundraising round. Flip through it and then we’ll review it in detail…



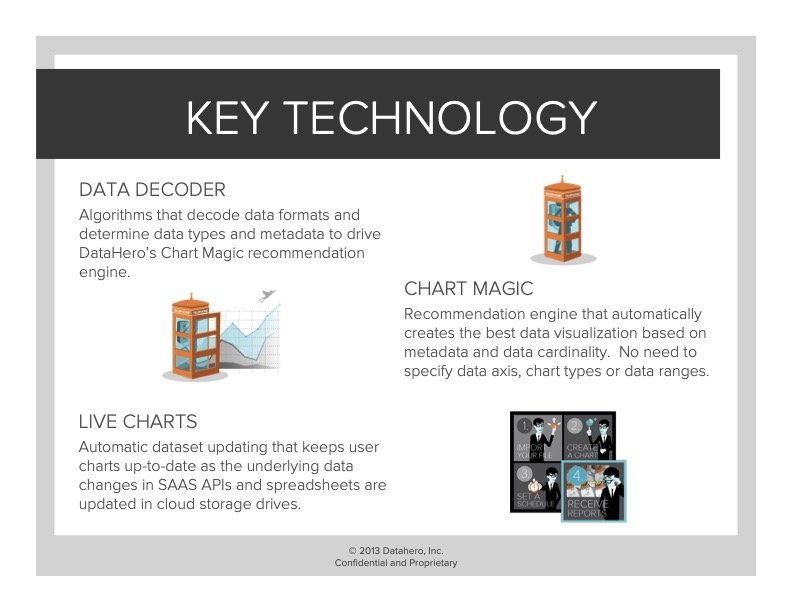


Slide-by-Slide Review
Let’s start off by going through the slides one-by-one:
Title Slide

DataHero was founded at a time when tongue-in-cheek interfaces were quite popular (e.g. MailChimp had monkeys all over). Our branding was designed around superheroes, with a mid-century look.
The title slide showcases the art style (which we thought was important given our focus on UI/UX) and the background suggests that DataHero is some sort of an analytics product.
The one mistake in this slide is that we used our marketing tagline instead of describing our product and/or market, so it’s not clear what exactly DataHero is or who it’s for.
Slide #1

What did we put on our very first slide…? Another title slide! 🤦♂️
Having a subject title slide like this might make sense if you’re presenting at an academic conference or BigCo™️ event, but in a pitch deck it’s completely unnecessary/redundant.
(If we wanted our names as cofounders at the start of the deck, we could easily have put them in the actual title slide.)
Slide #2

Here’s the real first slide. The opportunity to grab the reader’s attention, like an explosion right out-of-the-gate in an action film.
So what did we do? We shared a company timeline — something that should generally be the second-to-last slide in a deck.
Oh…and the timeline didn’t have any user- or revenue-related achievements.
An effective first slide needs to have impact. It could describe the problem being solved and its scale, present compelling traction metrics, or show impressive customer logos. But it has to draw the reader in and make them want to learn more.
This…ain’t it.
Slide #3
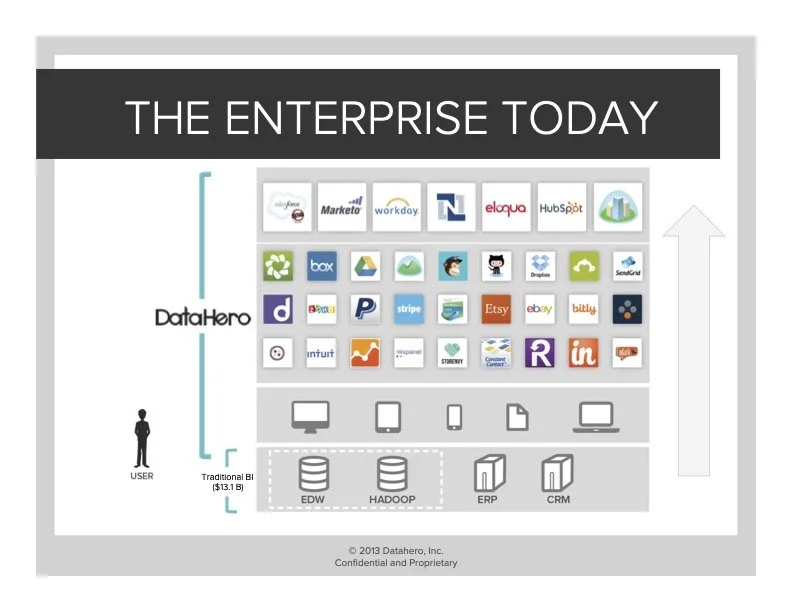
This, on the other hand, is a pretty effective slide.
It frames the problem we were solving by showing the data sources that traditional BI solutions worked with (at that time, primarily on-premise databases and other software) and contrasts that with the many SaaS services BI software couldn’t connect to.
If I were to do anything different with this one, I’d try to find some numbers to quantify those services in some way (how many users do they have? how much do companies spend on them, etc.). We implied that it was a big market by including the size of the traditional BI market, but at that time it was still a leap of faith to quantify the opportunity for DataHero.
Slide #4

This is a strong, concise product statement.
The only way to improve it would be to add market sizing, such as:
“DataHero will be the platform that enables 5 million enterprise users to visualize their cloud data”
or
“DataHero will be the platform that enables enterprise users to visualize 100 PB of data locked away in cloud services”
Slide #5
This is another strong slide that answers one of the most important questions early investors have: “Why are you the team to win this market?”
In the case of DataHero, we were building a product focused on a new market: business users who relied primarily on cloud services and needed to better understand the data stored within those systems. We felt that our combination of a CEO with a background in enterprise data software, a well-known UX expert and a creative director who led design at a Sequoia-backed company through IPO perfectly positioned us to develop the right product for this market.
This slide resonated strongly with potential investors.
Slide #6

This was a placeholder slide for demos during in-person / virtual meetings.
There’s obviously no reason to include this slide in a deck being emailed to investors. That said, were we to remove it, we would have needed to add more screenshots of the product (which we should have done anyways, since this is the only screenshot in the entire deck…).
Slide #7

This is a relatively decent “what does your product do” slide, but in hindsight it would have been better if we had replaced the cutesy cartoons with actual screenshots and/or a flow chart describing the user journey.
Slide #8

User/customer quotes are great, but they’re always a bit suspect when they don’t include the name of the company where a user works.
I can’t recall why we didn’t include Ali’s company name here - likely we thought it was too small or unknown. Now that I’m on the other side of the table, I see it through a different lens: you should always include customer names / logos whenever possible (even if you don’t think it’s a “big” name), because it’s an actual customer and you can/should project pride around that!
Everyone has to start somewhere.
Slide #9

Ok, so I just said that user/customer quotes are great…
…but there’s no reason for them to span two slides.
These should be combined into a single slide (with company logos added to each).
Slide #10

This is the first slide in the deck that references traction.
As an investor, the fact that it took so long is going to make me a bit skeptical, especially given that the timeline slide told me that the public launch occurred at least three months prior. We should have gotten to this sooner.
As for the slide itself, one of the biggest questions we faced when raising our Pre-Seed was “would end users pay directly for a data product?” (the number of successful bottoms-up SaaS products was still relatively small at that time). The title was meant to answer that question. The thing is, almost none of the investors we spoke with about our Seed round had met us before - so we were answering a question that they didn’t ask.
As such, they interpreted this slide as us claiming that we had “proven” a market, when it was obvious that we weren’t anywhere close to product-market fit.
All registered users proves is that you’re good at marketing. It says nothing about what happens after signup - is the product actually what people are looking for..?
Slide #11

At first glance, this is a really strong slide. It’s a list of amazing logos of companies that were using our product.
Unfortunately, they represented free users, not paying customers (at the point we raised our Seed round, we had just started to figure out monetization and how to effectively separate our free and paid products).
That said, to a potential investor, this is likely an impressive enough list to result in a first meeting - if only to dig in deeper. At the time, several investors told me that this slide was what resulted in us getting a meeting. The problem was, when they inevitably asked us how many of these companies were paying customers, we would sheepishly say “zero…” which wasn’t a great look.
Slide #12

This is a relatively strong case study slide, with one exception: it’s also talking about free users rather than paying customers. And the wording makes that fact glaringly obvious to an experienced VC.
As an investor, anytime I see a case study slide without any reference to revenue or licenses, alarm bells go off. 🚨
This slide is effective at showing that “land-and-expand” was working for DataHero as a product, however (unbeknownst to us at the time), it also makes clear that we weren’t in control of it — it wasn’t yet working from a sales perspective.
All that said, at the Seed stage, this is still okay — because pricing can be fixed.
Slide #13

Ugh…another slide with “proven” in the title 🤦♂️
I’m not sure why we made this slide the way we did, but in our minds it was important to emphasize how cheap/scrappy/cash-efficient we were.
As a concluding/timeline slide, the bullet points are solid. As a team slide, this is underwhelming (because we don’t include any logos of where our employees previously worked).
Going back to my comment on slide #5 about investors wanting to know why you’re the team to win, anytime you show your team it’s essential to include key details about them. A picture is worth 1,000 words and the best way to do that is to add logos of prior employers, schools, etc.
Slide #14

Conceptually, this go-to-market strategy makes sense.
But as an investor, I’m screaming “where are the numbers?!?” The product has been in market for at least 3 months, slide #10 has fairly impressive registration numbers (at least, for those days), but there’s still nothing concrete about user behaviour, retention or — heaven forbid — revenue.
As an investor, the fact that we’re now on slide #14 and I haven’t seen anything on unit economics is setting off all sorts of alarm bells that nobody is actually using this product (and they’re certainly not paying for it).
Slide #15

This is an interesting product slide, but I immediately want to learn more:
Which integrations were most popular?
What are the retention/revenue metrics for each?
What did you learn by attempting to attract a “diverse base of business users?”
For in-person meetings circa 2013, this was great (because we had answers to all of those and it would steer the conversation in a certain direction). By 2022 standards, this slide needs more depth.
Slide #16

There is literally no reason why this should be a separate slide (vs. combining it with slide #15).
Slide #17

This slide really frustrates me - as it breaks one of the cardinal rules of pitch decks: don’t mix two separate topics on a single slide.
The first section talks about predictors of usage (which hints at our retention / monetization strategy), while the second is about feature requests (or at least it reads that way - it was actually a really awkward way of explaining why the majority of our users didn’t connect a cloud BI product to a…you know…cloud service).
Oh…and still no depth to the numbers.
Some charts and substance around retention would have been great here. Also using plain english to explain that the 75% of users who weren’t connecting to SaaS services were doing so because they were uploading Excel files (from corporate data stores, services we didn’t support yet, etc.) and visualizing them.
Slide #18

Oh, look! Another roadmap slide.
All of this makes sense, but it’s frankly pretty in the weeds and could easily be combined with slide #14.
Slide #19

But wait! You haven’t seen enough roadmap slides yet? Let’s add one more… 🤦♂️
…and what is this one is entirely focused on? Product. Nothing about user numbers, revenue, or any other business metric. Just features and functions.
Interesting stuff to be sure, but by this point as an investor, I’m likely convinced that there are zero active users, zero revenue and I’m skeptical that there’s any plan whatsoever for sales and marketing. Typical technical/product founders building a product without talking to customers…
(The worst part is, we had tons of data from talking to early users and customers, but we weren’t showing it!)
Slide #20

Slide #20.
The second-to-last slide in the entire deck is the first and only time we used the word “revenue”.
FFS.
And even then — this slide shows projections for 2014 and beyond, but there is still no information whatsoever on the revenue DataHero had achieved to-date.
Looking back at my records, at the time of our fundraise our revenue was pretty paltry (we had about 20 paying customers generating around $500/mo in revenue), but it was something. To think that we could “hide” it from potential investors was beyond naive. Even for an early startup, you have to talk about revenue.
In our case, while our revenue was minimal, we actually had a strong free user base and had learned an incredible amount around usage patterns (hinted at in slide #17). The revenue was a lagging indicators because we had the wrong “premium” features at the time — something that’s fairly common for early startups. We should have leaned more into the data we had, rather than shying away from the revenue we felt that we didn’t have.
Slide #21

The final slide: the ask!
…this slide makes me cringe every time I look at it.
It makes two big mistakes:
It doesn’t include anything about what we’re going to achieve with the fundraise (how many users will we attract, how much revenue will we generate, etc. with the funding)
It positions $3M / $3.5M as already secured.
The former is a very common mistake in pitch decks. Founders talk about what they’re going to spend the money on, but not the milestones they’re going to achieve with it. Investors want to know what your plan is for the next 12 - 18 months to understand how you will de-risk the business and position it for a subsequent raise.
The latter point is one where I know we made a big strategic mistake.
Foundry Group, who led our first round, had shared their conviction in DataHero and offered to take down the entire seed round. We wanted to test the market, but didn’t know how/if to leverage Foundry’s offer with other investors.
We thought that we could gain leverage by bragging that “our existing investors think DataHero is so awesome they’re willing to put another $3M in!” but by including it in the deck the way we did, I believe a significant number of investors passed without a meeting because they presumed the lead to be secured. They thought we were looking for a relatively small amount of money to close the round (which wouldn’t achieve their ownership targets) and passed immediately.
Overall Review
Now that we’ve gone through each slide one-by-one, what are the key takeaways?
The Good
Despite the title of this post, there were certainly some things we did right:
The design of the deck was clean and did a good job of reflecting our brand and approach. (There continues to be a healthy debate around whether or not a pitch deck needs to “look good” — I am firmly of the belief that if UI/UX is a key part of your value proposition, the answer is 100% “yes.”)
We did a good job of answering the question “why are you the team to solve this problem?”
We presented the opportunity effectively by contrasting the world today (BI for on-premise data stores) with the world of tomorrow (BI for cloud-based services).
We presented the key features in an easy-to-understand manner while making clear that there was real tech under-the-hood.
We had strong customer quotes in support of the product.
The Bad
By far the biggest overall issue with our pitch deck was the complete lack of metrics. Despite the fact that we were only a few months into market and had almost no revenue, we had a significant amount of data around usage patterns and user retention. At a minimum, we needed a revenue slide (since every investor immediately asked about it), but in reality we could have done a lot to support our progress towards product-market fit by including user data — and we had a ton of it. By committing the sin of omission, we left potential investors free to assume the worst: that we were a heads-down product-centric startup that was good at getting registrations, but not at building a product users actually wanted.
In hindsight, the lack of screenshots was another obvious omission. DataHero was a gorgeous product with a UI that blew away every other BI tool at the time, yet we leaned on illustrations instead of showcasing the product itself.
A third missing piece was a competitive slide. We alluded to legacy competition in slide #3, but there’s no mention of any other analytics tools for SaaS services (DataHero was the first horizontal cloud BI tool, but there were service-specific tools already in market at the time, such as Baremetrics for Stripe).
Ironically, we had all of these slides — we just held them back them for after the first meeting. What we didn’t realize at the time (which I now clearly know), is that by holding back key parts of the story, we lost a lot of potential investors who never opted in to meet us.
In addition to the points above, the overall flow of the deck could be significantly improved. We should have led with the problem statement and market instead of starting with history to make sure we were hitting hard from the start. Revenue/traction definitely should have come earlier and with far more depth. Investors want to know what you’ve achieved (no matter how early in your journey you are), so don’t bury the lede!

This tweet from Paul Graham sums it up nicely
Finally, the deck was way too long. A good Seed deck should be 10 - 12 slides long (14 slides max). In our case, a number of the slides could easily have been combined, which would have made the deck far more concise and impactful. If all the user data we didn’t include made the deck too long, we could have put those slides into an appendix without sacrificing flow.
The Ugly
Including Foundry’s verbal commitment on the slide deck was a monumental error on our part. Instead of having the intended effect of demonstrating strong support from our existing investors, it gave the misconception that the lead investor was already decided and we were only looking to fill out the round.
So What Happened?
In October 2013, we launched our fundraising campaign, with our investors supportively sending out introductory emails to everyone on our target list. A significant majority declined those introductions, which I now believe to be in large part due to (a) the lack of metrics in our deck and (b) the manner in which Foundry’s verbal commitment was framed.
We still met with a good number of investors, several of whom went deep into diligence. Ultimately, the fact that we were so early into monetization at the point of fundraising was a challenge for net new investors (particularly given the amount we were looking to raise). After a few weeks, we pulled the plug on our process and finalized the internal round with Foundry leading:
DataHero Raises $3.1M and Revamps its Analytics Service
- GigaOm, December 10, 2013
Canadian VCs Need to Get Out of Canada
As a Canadian investor, I get to meet incredible founders from Victoria to St. John’s every single week. But as much as I enjoy crisscrossing this magnificent country, for me to be an effective investor, it's essential that I get out of Canada.

As a Canadian investor, I get to meet incredible founders from Victoria to St. John’s every single week. Some of the most ambitious people on the planet are building world-changing companies in the country I love and I’m privileged to have a front row seat. But as much as I enjoy crisscrossing this magnificent country (both virtually and – finally! – on airplanes again), for me to be an effective investor, it’s essential that I get out of Canada.
Already this year, I’ve been to San Francisco, Miami, Atlanta and LA. By the summer, I’ll have added Austin, Los Angeles, Tokyo and a second trip to San Francisco. Why do I do this? If my job is investing in Canadian startups, how can I possibly justify spending so much time gallivanting around the world?
Because it’s the only way for a VC based outside of Silicon Valley to be truly effective.
It shouldn’t come as a shock for me to point out that Silicon Valley is the only ecosystem in the world where investors see global deal flow. But think about the implications of that statement:
The best founders from all over the world travel to the Bay Area (physically or virtually) to raise capital. As a result, Silicon Valley investors can sit back confidently knowing that they’ll see the best that the world has to offer. When they make investment decisions, they do so with a global perspective.
For the rest of us, we need to put the work in.
That work comes in the form of travel. I love to travel and it makes me a better person in numerous ways. But it makes me a better investor in at least three:
Better Investment Decisions
If I only meet Canadian founders and only talk to Canadian investors, then my entire perspective on tech is based on what’s happening north of the 49th parallel. But my job is to invest in Canadian companies that can dominate on a global scale.
The Olympics have taught us that while we can own the podium in some sports, the best in Canada often don’t make the finals. The same is true with startups. That’s not a knock against Canadian founders. It’s the reality of competing in global markets. As an investor, I need to know what’s going on in the rest of the world in order to understand how good the “best in Canada” really is.

In both Olympics and startups, Americans often dominate the podium
Having a better understanding of the global tech landscape provides all sorts of advantages as an investor:
I can go all-in on an under-the-radar startup because I’m confident there’s nothing close anywhere in the world
I can pass with conviction on a “hot” local startup that other investors are tripping to get into because I know that there are three well-funded competitors in other countries that are still in stealth mode
By tapping my network to diligence startups in others countries, I can see opportunities to invest where others are scared away by “too much competition”
I can more accurately incorporate the likelihood of subsequent funding into my investment decisions, because I understand what downstream Silicon Valley investors believe will be hot/cold in the next 18 months
Better Founder Advice
For most founders, investors are a key source of mentorship and advice (I certainly believed that my investors knew everything back when I was a founder). One of the most crucial areas that investors have impact in is helping founders understand what milestones they need to achieve to raise the next round.
The problem is, if your goal is to raise your next round from Silicon Valley VCs (which is the case for the most ambitious founders the world over), then you need to know what Silicon Valley investors are looking for. Unfortunately, too many Canadian investors authoritatively tell founders that they need to achieve X, Y and Z to raise their next round, when the only downstream investors they’ve spoken with are down the street.
I can’t tell you how many Canadian founders I’ve met who dutifully marched towards the milestones their investors so confidently laid out, only to discover that they were nowhere close to what Silicon Valley VCs were actually looking for. Never mind the number of times I’ve heard a Canadian investor dismiss a large US-led round as being nothing more than FOMO or a company “raising a Series A on Seed metrics,” — as if the most sophisticated investors in the world were simply being duped.
The entire Silicon Valley ecosystem - startups and investors alike - evolves at a rate unlike anything else in the world. The best Canadian investors recognize this and are constantly In Silicon Valley. The lazy ones regurgitate media talking points instead of taking the time to understand the changing dynamics at play.

I was 4 rows behind Boris on this flight 👀
Better Investor Introductions
Job #1 for every VC is to help their portfolio companies raise their next round.
As important as mentorship and hands-on help is, the single biggest impact investors have after writing the check (cheque?) occurs during fundraising itself, helping companies prepare their pitch, making warm introductions to downstream VCs and championing portfolio companies through the process. In Silicon Valley, this is burned into the psyche of every investor, which is why they spend 1/3 of their time networking with other investors.
In Canada, not so much.
When I lived in Silicon Valley, I regularly met with Canadian founders who were trying to raise money in the US and was shocked by how many told me that their well-known, well-respected VCs provided zero warm introductions to Silicon Valley investors. Are you serious?!?
Today, there are nearly 2,000 active VC firms of various shapes and sizes between San Francisco and San Jose. The landscape is constantly changing, with new funds popping up literally every week. If I want to help startups raise their next rounds, then I have to meet as many of those investors as I possibly can, which means getting on a plane.

One of 4 dinners I had with investors on my last trip to SF
To be clear, my primary focus is — and will continue to be — meeting Canadian founders and investing in Canadian startups. This quarter alone, I’ll travel from my home in Vancouver to Victoria, Toronto, Montreal and St. John’s.
But for me to serve those founders best, it’s absolutely essential that I get out of Canada.
Why Did I Come Back to Canada?
Since moving from San Francisco to Vancouver in late 2020, I’ve been asked one question over and over: “Why did you come back to Canada?

Since moving from San Francisco to Vancouver in late 2020, I’ve been asked one question over and over: “Why did you come back to Canada?”
The short answer is that the Canadian tech ecosystem is at a generational inflection point and I want to be a part of it.
The longer answer is that through my nearly 20-year journey in Silicon Valley, I’ve developed a unique expertise in helping international startups access US capital. I believe not only that Canada is on the precipice of greatness, but that I can help accelerate the global potential of the next generation of Canadian startups.
In 2002, I moved to the Bay Area for grad school and became immersed in the Silicon Valley tech scene. My professional journey started at Motorola (back when the Razr was the hottest phone on earth and the iPhone was nothing more than an Apple fanboy’s dream), followed by two incredible startup adventures as the first employee at big data pioneer Aster Data and the CEO/cofounder of DataHero.

Aster Data, 2006 (Redwood Shores, CA) — Like my pink shirt?
After DataHero was acquired in 2015, I joined 500 Startups, where I invested in data and AI startups around the world on behalf of the firm’s flagship accelerator. Seeing the immense opportunities in bridging the gap between Silicon Valley and global startup ecosystems, I left to found Commonwealth Ventures. The goal of Commonwealth Ventures was both simple and groundbreaking: to increase the rate at which international startups could raise capital from Silicon Valley VCs with a starting assumption that they would never relocate to the US. At a time when the majority of US VCs still expected international founders to move to Silicon Valley as a condition of investment, this was unheard of.
And we were incredibly successful. Through a combination of mini accelerators (“fundraising bootcamps”), hands-on services and a powerful mentor network, in less than 3 years we helped international startups raise over $100M in Seed and Series A funding from US investors.
So why did I forgo this global opportunity to focus exclusively on Canada? Here’s the thing: 90% of that funding was raised by Canadian startups.
Even to a proud Canadian, this was a stunning result that I didn’t see coming. It turned out that two fundamental shifts were at play:
The Canadian startup ecosystem, which for years had been slowly but surely growing, was finally reaching escape velocity — with compelling new startups emerging faster than almost any other country in the world
US VCs had overwhelmingly become comfortable investing into Canadian domiciled companies
The second point represented a tectonic shift from only a few years prior, when most US investors still required Canadian companies to reincorporate in Delaware (and, thus, forgo significant tax breaks and grant opportunities).
With such an incredible opportunity staring me in the face, whatever thoughts I had of building Commonwealth Ventures in San Francisco crumbled like Jimmy Garoppolo on a fourth quarter drive. It was clear to me that the real opportunity was to focus exclusively on helping Canadian startups close the funding gap with their American competitors. Less than a year later, Commonwealth Ventures was acquired by Panache Ventures, Canada’s leading pre-seed and seed stage venture fund.
And, thus, began the next chapter in my startup journey, back where I started.